
Market News
Avenue Supermarts shares down 22% in 6 months: Store growth, valuation emerge as key investor concerns
3 min read | Updated on October 06, 2026, 09:03 IST


SUMMARY
While revenue growth remained healthy in Q2 FY27, the pace of store additions stayed muted, raising questions around the company’s near-term growth trajectory.
Stock list
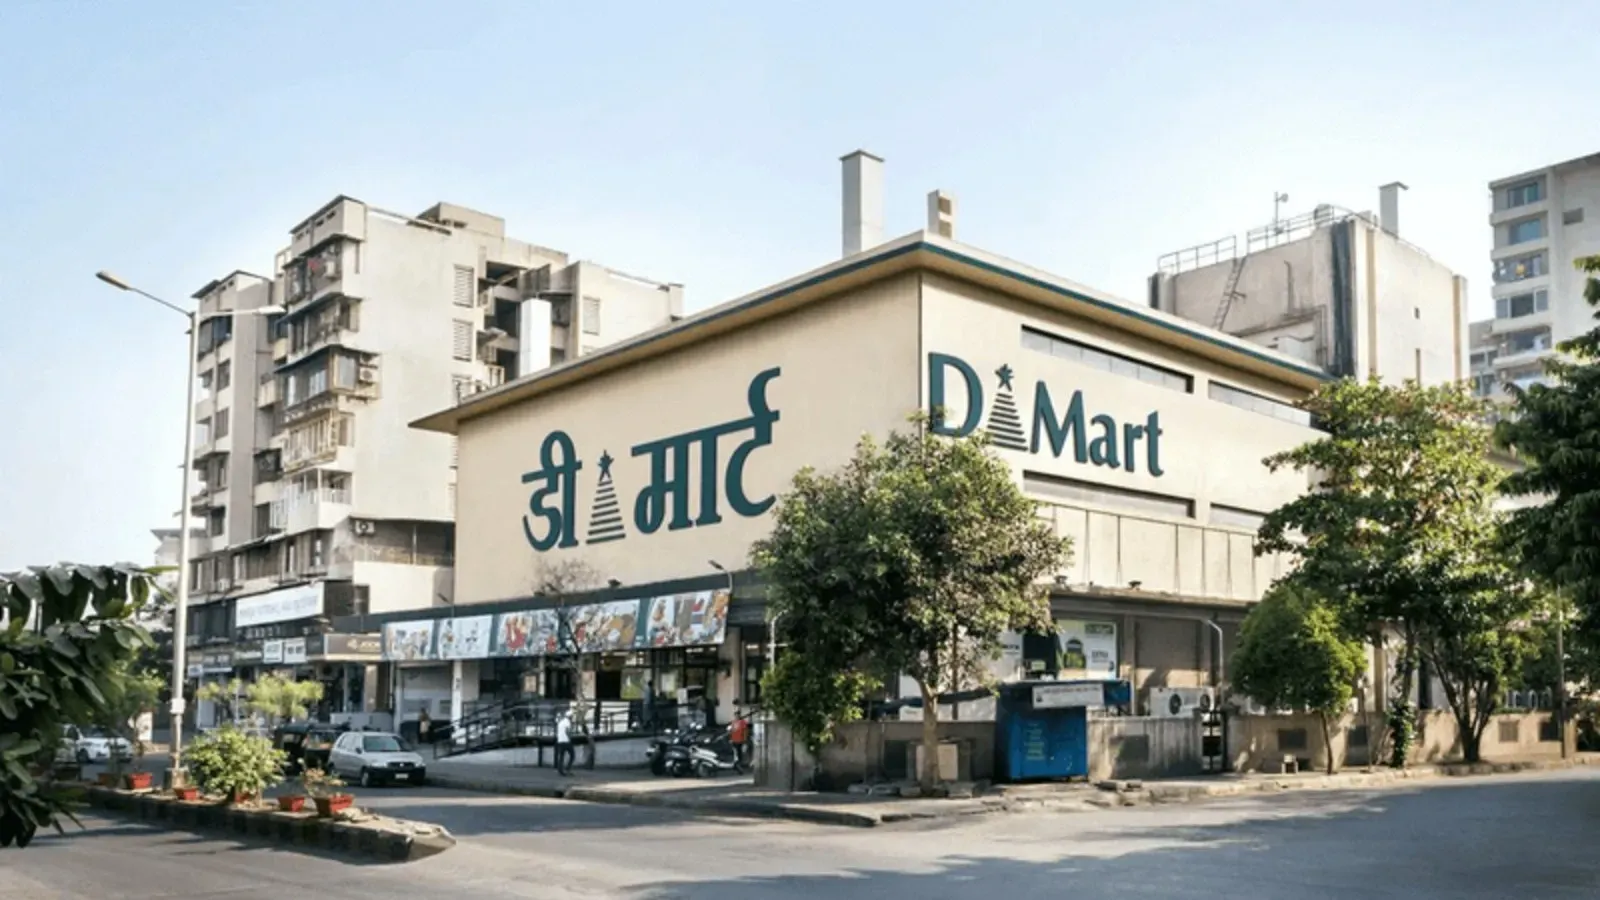
Avenue Supermarts added 18 stores in H1 FY27, compared with 17 stores in the year-ago period. Image: Shutterstock
Avenue Supermarts shares have declined around 22% over the past six months (as of Monday, Oct 5 closing level), with the stock failing to find much support even after the company’s Q2 FY27 business update.
While revenue growth remained healthy, the pace of store additions stayed muted, raising questions around the company’s near-term growth trajectory.
Avenue Supermarts added 18 stores in H1 FY27, compared with 17 stores in the year-ago period, indicating that the pace of expansion has remained broadly flat.
This remains a key factor for investors to track, as store additions are an important driver of DMart’s revenue growth. At the same time, CLSA expects the company’s pivot towards private labels, store expansion, and inflation to support growth going ahead.
Valuation remains another key area of debate. CLSA retained its positive stance, citing the company’s topline performance and potential growth drivers.
In contrast, CITI has pointed out its cautious view on the company’s valuation. The divergent analysts' views highlight the key question for investors: whether Avenue Supermarts’ future growth can justify its premium valuation.
What investors need to understand
NSE data show that DMart’s adjusted P/E stands at 81.34 times, indicating that the stock continues to command a premium valuation. This means investors are already pricing in strong future earnings growth.
With store additions remaining broadly flat in H1FY27 and competition from quick-commerce players intensifying, the key question is whether the company’s future growth can justify the premium valuation.
P/E (price-to-earnings) ratio shows how much investors are willing to pay for every ₹1 of a company’s earnings. For example, a P/E of 81 means investors are paying ₹81 for every ₹1 the company earns.
D-Mart Q2 FY27 update
Avenue Supermarts, which owns and operates the retail chain D-Mart, reported an 18.4% rise in standalone revenue from operations to ₹19,206.18 crore for the second quarter ended September 30, 2026 (Q2 FY27).
The company had reported revenue from operations at ₹16,218.79 crore a year ago, Avenue Supermarts said in a regulatory filing on Saturday.
"Standalone Revenue from operations for the quarter ended (QE) September 30, 2026, stood at ₹19,206.18 crore," the company said in its update at the end of the quarter.
The total number of stores of the Damani-family-promoted retail chain stood at 518 as of September 30. This also includes its Sanpada, Navi Mumbai, Maharashtra store, which is currently closed to customers due to reconstruction.
On a quarter-on-quarter basis, D-Mart's revenue climbed 4.7%. Its revenue was ₹18,343.49 in the June quarter.
Promoted by Radhakishan Damani and his family, D-Mart retails basic home and personal products across markets, including Maharashtra, Gujarat, Andhra Pradesh, Madhya Pradesh, Karnataka, Telangana, Chhattisgarh, NCR, Tamil Nadu, Punjab and Rajasthan.
What the trend indicates
Retail companies reported high double-digit revenue growth in the July-September quarter of 2026, despite the festive season shifting from Q2 to the October-December quarter this year.
Major retailers such as Avenue Supermarts (DMart), V-Mart Retail and V2 Retail posted significant revenue growth during the quarter, while companies continued to expand their retail footprint by opening new stores across markets.
With the festive calendar shifting, a larger part of festive-led retail demand is expected to be reflected in Q3 FY27.
Related News
About The Author
Next Story

