
Personal Finance News
Not updating her PAN address cost this senior citizen ₹5,000, but ITAT still gave another chance in an ancestral property case; here's why
5 min read | Updated on October 09, 2026, 13:56 IST


SUMMARY
The ITAT order matters to co-heirs selling inherited property and to senior citizens who have moved home, because it deals with an everyday problem.
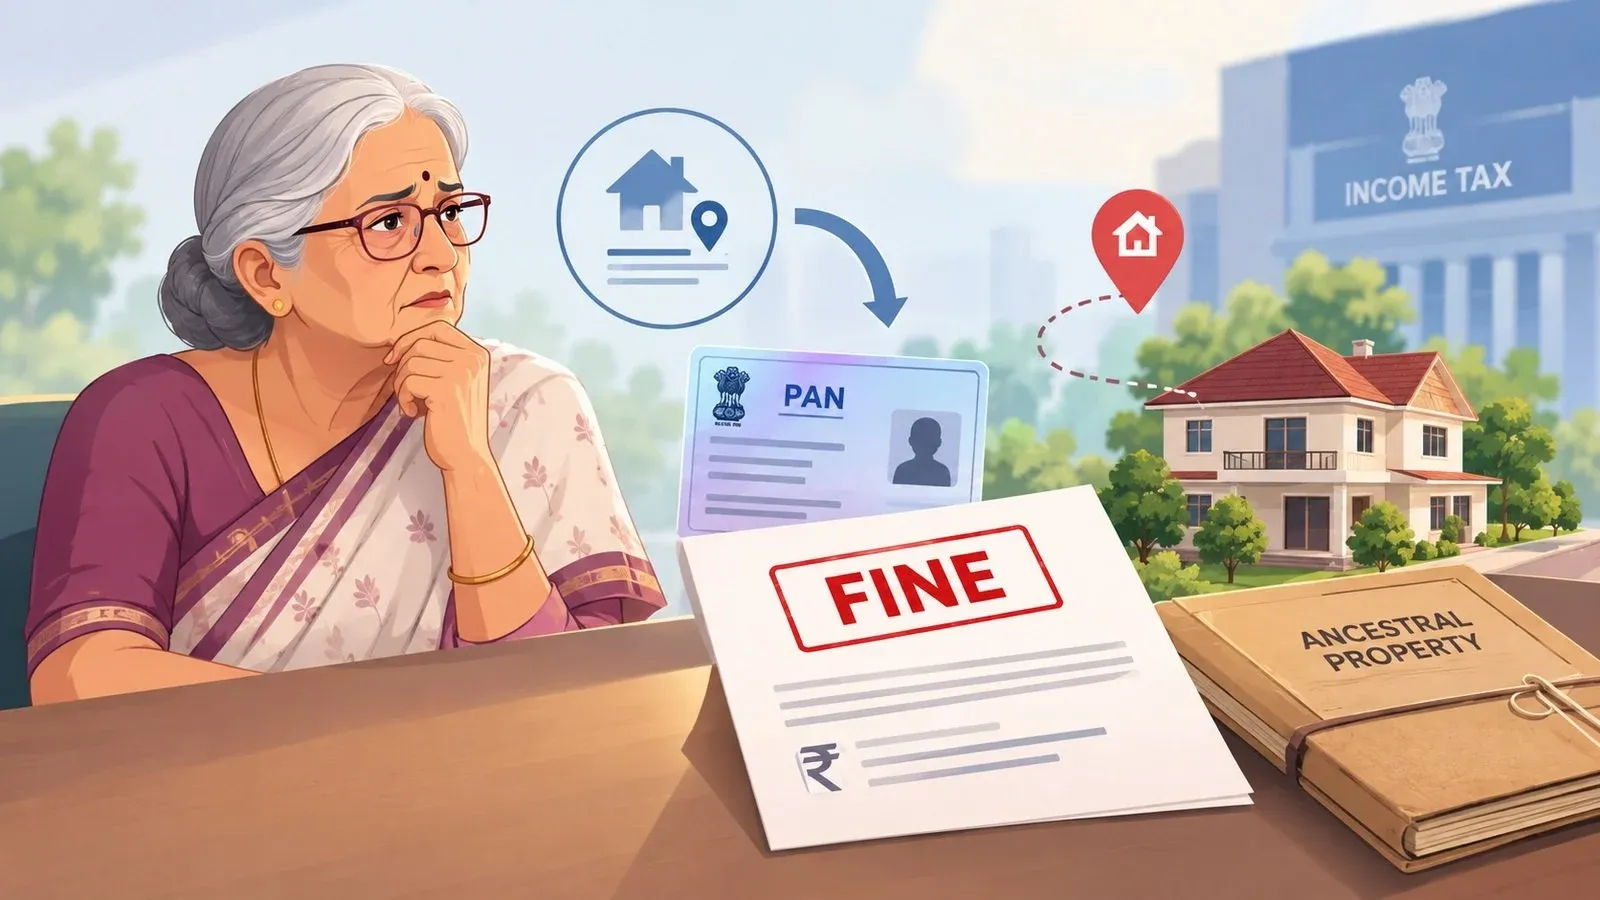
When Malek appealed to the CIT(A), she was 136 days late. | Representational image/AI generated
This article explains what happened in this case as per the ITAT order dated September 24, 2026 and key lessons from it for taxpayers.
Case history
Waheda Malek, a senior citizen, had inherited her share of the ancestral property. She and the other co-heirs executed a Deed of Conveyance dated 20 June 2016 for a total consideration of ₹1,15,00,000. The value adopted by the Stamp Valuation Authority for the same property was ₹4,35,97,000.
On the back of information relating to the sale, the assessing officer reopened the assessment under section 147 by issuing a notice under section 148. Malek could not comply with the notices issued during the reassessment, including those under sections 148A, 148 and 142(1). The officer then completed the assessment ex parte on May 26, 2023 under section 147 read with section 144, making the additions set out in the order [cite:fad46adb3:p2].
When Malek appealed to the CIT(A), she was 136 days late. She filed an application seeking condonation. Her explanation was that the statutory notices and the assessment order had been sent to her earlier address at Wadala, Mumbai, whereas she had shifted to Andheri (West). Being an elderly housewife not conversant with income-tax proceedings, she said, she was unaware of the case and learnt of the assessment order only later, after which she took professional advice and filed the appeal.
The CIT(A) did not accept the explanation and declined to condone the delay while dismissing the appeal without touching the merits.
What the ITAT said
Before the tribunal, her counsel stressed that she held only a 25% share in the inherited property. Her share of the actual sale consideration was ₹28,75,000. Also, the delay was neither intentional nor deliberate.
The tax department's representative argued that a taxpayer is expected to keep her address updated and that the delay was rightly not condoned.
However, the tribunal sided with the assessee on the delay, while noting her lapse.
From SC's decision in Collector, Land Acquisition v. Mst. Katiji & Ors., the ITAT drew the principle that "sufficient cause" should receive "a liberal, pragmatic and justice-oriented construction". Refusing to condone delay can shut out a meritorious matter at the threshold.
From SC decision in N. Balakrishnan v. M. Krishnamurthy, it took the point that the length of delay is not decisive and that the acceptability of the explanation is; and that "rules of limitation are intended to prevent dilatory tactics and not to destroy the rights of parties, and that where the explanation does not smack of mala fides or a deliberate dilatory strategy, a liberal approach may be adopted in advancing substantial justice."
Applying these, the tribunal observed that the assessment had been completed ex parte but the Revenue had not shown she gained anything by letting the limitation period expire. And nothing established mala fides or a deliberate strategy to prolong matters.
However, the tribunal was candid about her own failing: "the assessee cannot be said to be entirely free from lapse, particularly since the assessee was expected to exercise due diligence in keeping her address updated and in responding to statutory proceedings."
But that lapse, it held, "cannot by itself justify shutting out the assessee's statutory appellate remedy without examination of the issues raised on merits".
The tribunal condoned the 136-day delay, but she has not won the tax case yet
The ITAT did not decide the dispute over the ancestral property sale. As the CIT(A) had dismissed the appeal at the threshold, the grounds challenging the additions were never adjudicated, so the tribunal set aside the CIT(A)'s order and restored the matter for a fresh decision on merits, with a reasonable opportunity of hearing for Malek and an expectation that she cooperate and file her documents.
However, that relief came at a price. The restoration is subject to a cost of ₹5,000 imposed on the assessee, to be deposited in the Prime Minister's National Relief Fund, with the receipt placed before the CIT(A) within 30 days.
Takeaways
The ITAT order matters to co-heirs selling inherited property and to senior citizens who have moved home, because it deals with an everyday problem: notices and orders going to the address on the tax record while the taxpayer is living somewhere else.
However, the tribunal's order confirms that such a lapse, while not blameless, should not shut a taxpayer out of a hearing on the merits.
For co-heirs and senior citizens, the address on the tax record should not be seen as mere formality. Keeping the e-filing profile and PAN address updated could serve as the cheapest insurance one can get in a situation like Malek. But if a notice does miss you, this order shows that the door to a merits-based hearing can still be reopened.
Related News
About The Author
Next Story

