
Personal Finance News
A wrong PAN entry in a SpiceJet employee's ITR left a Delhi man facing a tax demand on income he never earned. Here's how he got relief after 14 years
3 min read | Updated on October 01, 2026, 16:16 IST


SUMMARY
The ITAT looked at both returns and noted a mistake apparent on record while filing the return of income of one Mr. Rohit Maan, who had wrongly filled the PAN of the assessee while filing his return of income.
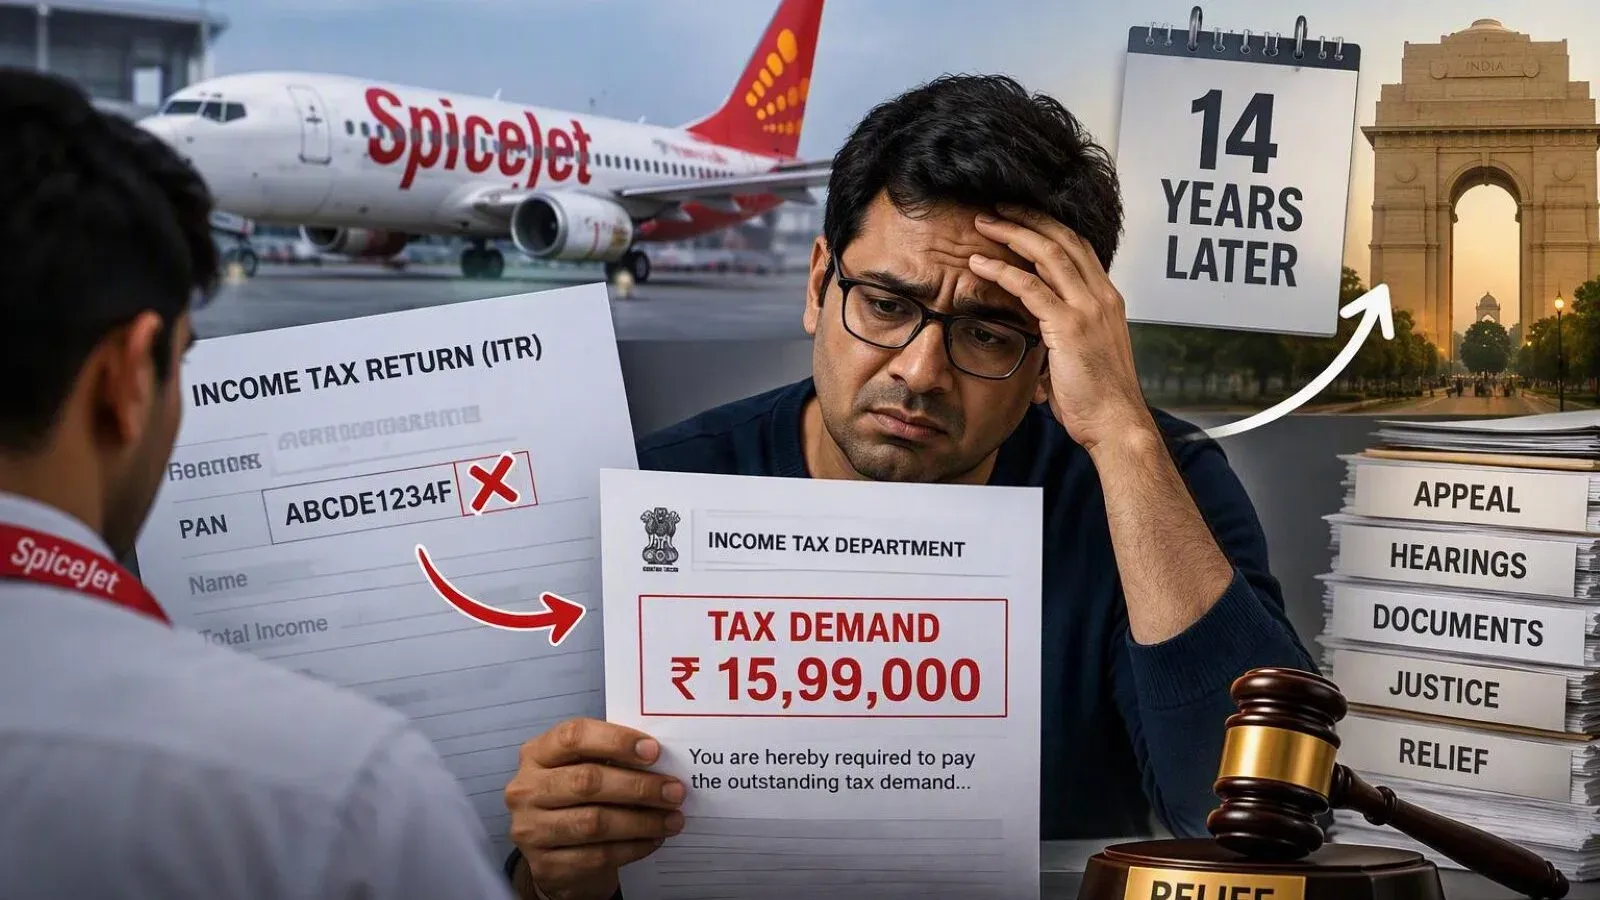
ITAT said wrong taxpayer cannot be put to difficulty on the technical grounds. | Representational image/AI generated
Rajesh Maan of Delhi faced a tax demand on an income he had never earned. Someone else had filed a return with his PAN on it, resulting in a case that lasted 14 years.
In an order dated September 9, 2026, the Income Tax Appellate Tribunal (ITAT), Delhi, deleted the tax demand while holding that a wrong taxpayer cannot be made to suffer on technical grounds for a mistake that was never his.
Case history
The history of the case, as recorded in the order, is as follows:
Rajesh Maan had an actual income of just ₹2,15,649. But one Rohit Maan, who had a total income of ₹15,99,880, filed his return for AY 2011-12 by wrongly mentioning Rajesh Maan's PAN.
The Centralised Processing Centre (CPC) processed that return, and raised the demand Rajesh Maan's PAN. Meanwhile, Rohit Maan also realised his mistake and revised the return with the correct PAN. However, the tax department still processed the wrong return.
Rajesh Maan knew none of this. The order records that he discovered the demand only when recovery proceedings were initiated. After following up with the income tax department, he filed an appeal before the CIT(A). But he was late.
The CIT(A) dismissed the appeal purely for the delay of 4,442 days without venturing into merits of the case, according to the order.
Before the tribunal, Maan's counsel placed on record the two decisive documents: the ITR of Rohit Maan that had been filed with the wrong PAN, and Rohit Maan's corrected ITR. The tax demand, he submitted, did not relate to the assessee at all, and the delay deserved condonation because Maan had no idea that the demand even existed.
However, the departmental representative countered that such a huge delay could not be condoned without proper explanations.
What the ITAT said
The tribunal looked at both returns and noted "a mistake apparent on record while filing the return of income of one Mr. Rohit Maan, who had wrongly filled the PAN of the assessee while filing his return of income". It also recorded that Rohit Maan was an employee of Spicejet, whose Form 16 was filed in the paper book, and that he had subsequently revised his return.
On the issue of delay, the tribunal said, "No doubt there is substantial delay in filing the appeal but the demand raised by the Revenue is not belongs to the assessee and when the liability is not belongs to the assessee, in our view, the same cannot be invoked or recovered any tax unduly from the wrong assessee even though there is substantial delay in taking remedial measures".
The tribunal also said that "wrong taxpayer cannot be put to difficulty on the technical grounds".
For taxpayers, there are two lessons from this case:
-
Always check your Form 26AS or AIS periodically for incomes that are not yours. While a case of wrong PAN may not be possible these days, there can be wrong entries in your AIS which can become a big trouble in future.
-
If you receive a demand that you truly doesn't deserve to pay, a relief can come even after a decade of delay.
Related News
About The Author
Next Story

