
Market News
Week ahead: US Fed policy decision, oil prices, NSE IPO among key market triggers to watch

5 min read | Updated on September 15, 2026, 08:03 IST


SUMMARY
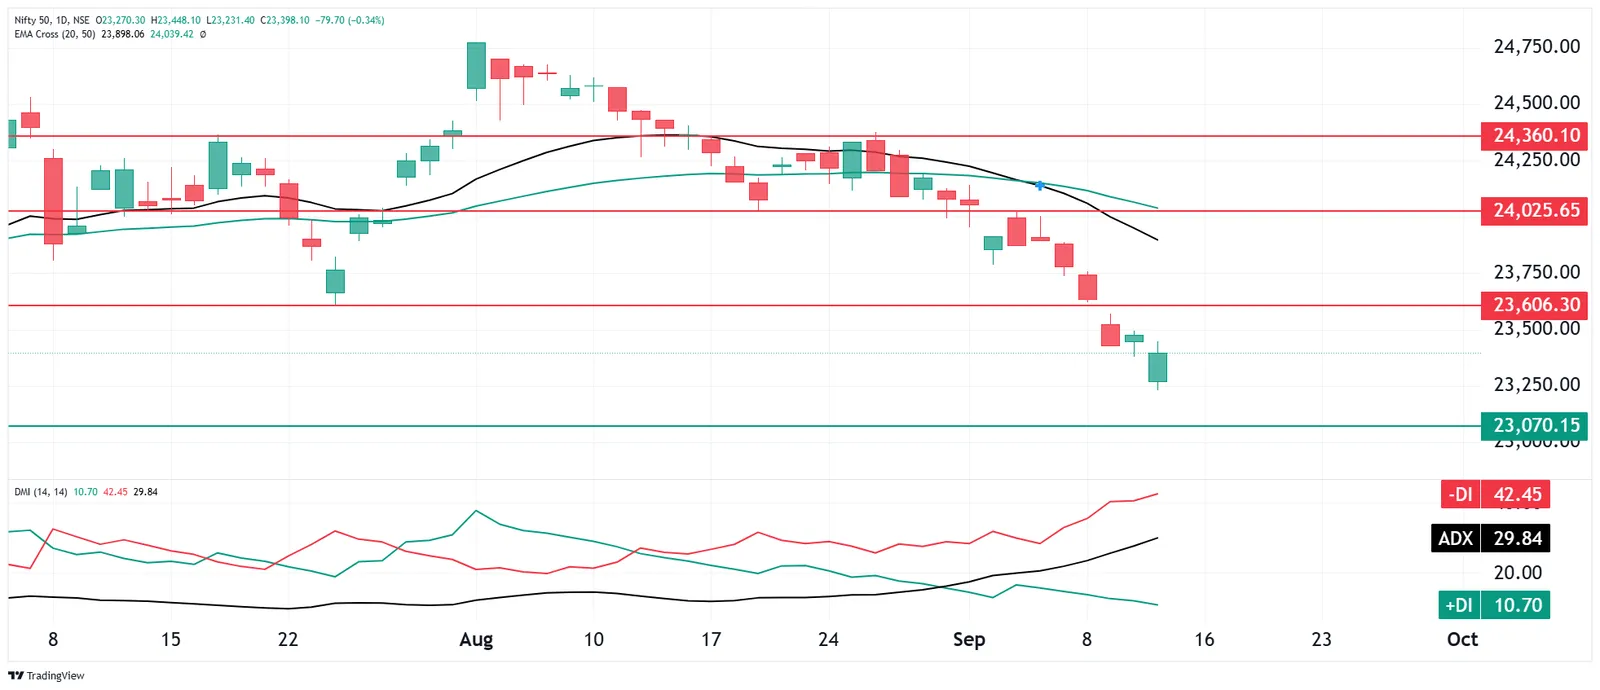
In the week ahead, the US Fed and Bank of Japan policy decisions, the NSE IPO and elevated crude-oil prices will guide markets. Global technology stocks will also remain in focus after Sam Altman and Elon Musk backed Anthropic CEO Dario Amodei’s call to slow the development of advanced AI models and allow safety measures to catch up. NIFTY50 remains bearish below 23,606, with major support near 23,070.
FIIs sold shares worth ₹1,795 crore during the week.
Indian equities declined for a fifth consecutive week. NIFTY50 fell 2.1% to 23,398, while the SENSEX declined 2.3 % to 74,781. Both benchmarks have lost around 4.8 % over five weeks.
The pressure came from the sharp rise in crude oil prices following fresh attacks on energy infrastructure and shipping routes in West Asia. A weaker rupee, rising global bond yields and growing expectations of a U.S. interest-rate hike added to the selling pressure.
Sectoral weakness was broad based NIFTY Realty was the biggest loser, falling 6.5 percent, followed by NIFTY IT with a 5.7% decline. Metal lost 2.4%, while Oil and Gas fell 2.2% despite the sharp rise in crude prices. PSU Bank, Media and FMCG declined nearly 2% each. Auto, private banks, financial services, pharma, healthcare and consumer durables also ended lower, showing that selling pressure was spread across the market.
The NSE IPO will be the sector’s biggest trigger in the coming week. The ₹22,569 crore issue will open on September 17 at a price band of ₹1,700 to ₹1,785 per share. The issue is entirely an offer for sale, so NSE will not receive any proceeds.
The Federal Reserve will hold its policy meeting on 15 and 16 September, with the decision due after the Indian market closes on Wednesday.
U.S. payrolls increased by 1,62,000 in August, while Consumer inflation then rose 0.4% month-on-month and 3.4% year-on-year. Core inflation increased 0.3%. Following the inflation report, futures markets placed the probability of a 25-basis-point rate hike at nearly 90%. A hike would lift the federal funds target range from 3.50–3.75% to 3.75–4.00%.
On Friday, the Bank of Japan policy decision on Friday is widely expected to raise its policy rate by 25 basis points from 1 percent to 1.25%. Higher Japanese rates could strengthen the yen and reduce the attractiveness of the yen carry trade, potentially creating volatility in global equities.
Market breadth
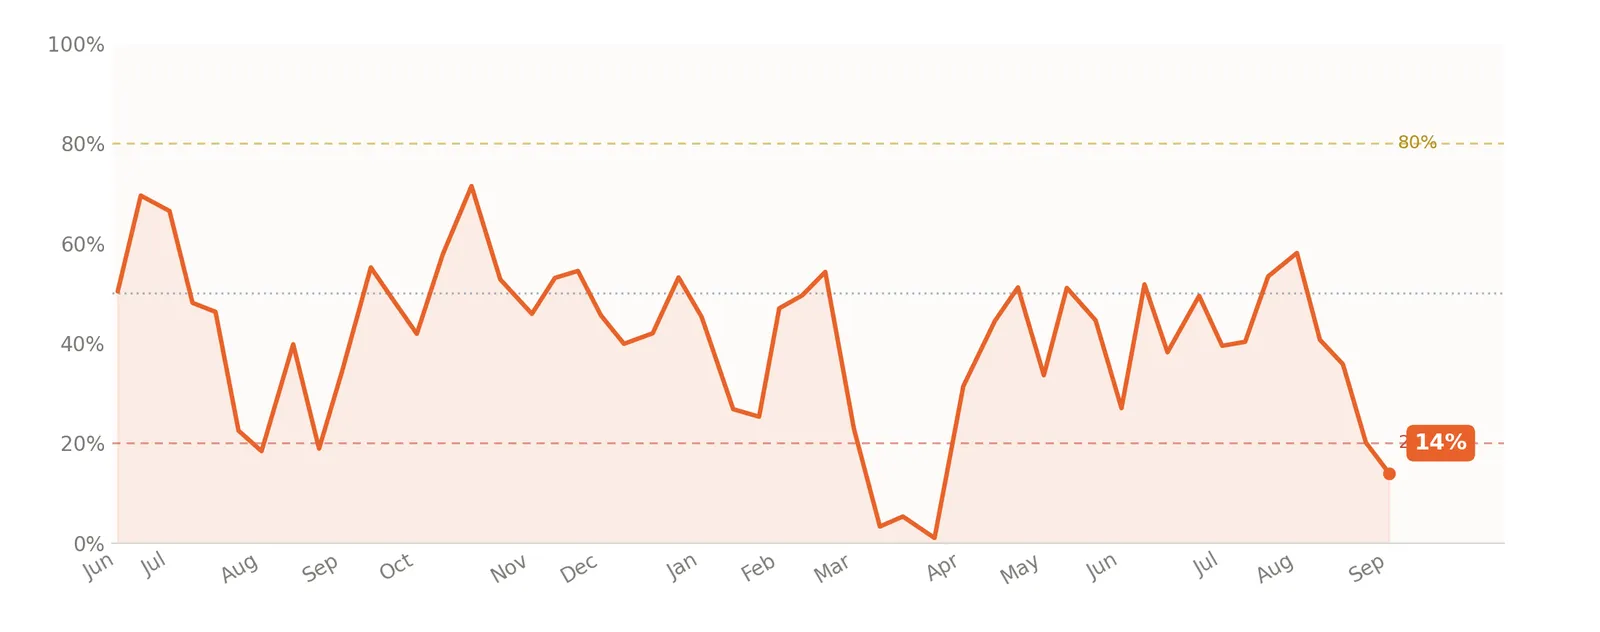
The breadth of the NIFTY50 index weakened further, with only 14% of its stocks trading above their 50-day moving average, down from 20% in the previous reading. The indicator has fallen below the 20% mark, confirming that selling pressure is spread across most index stocks. Such a low reading can support a short-term rebound, but breadth must recover above 50% to indicate a meaningful improvement in market participation.
Foreign investors positioning
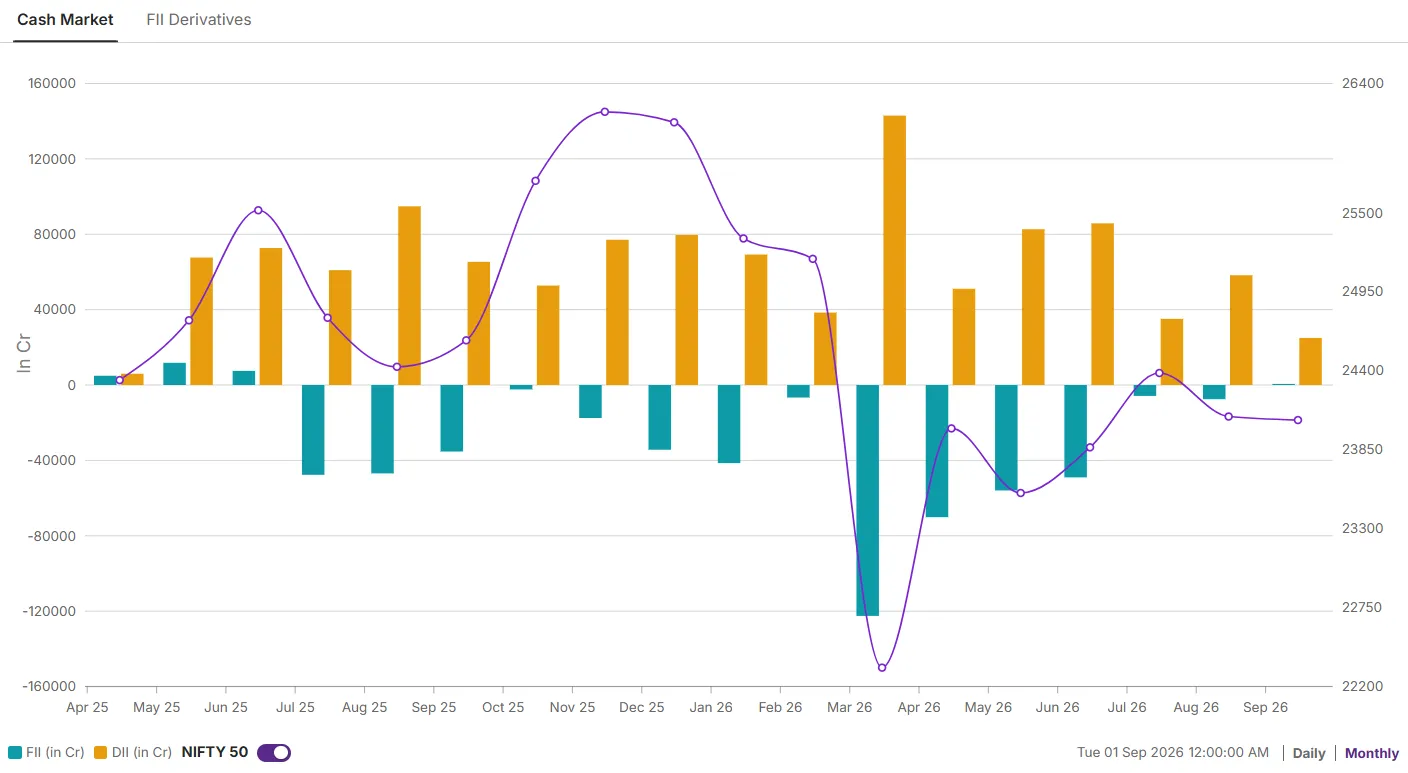
Foreign institutional investors sold shares worth ₹1,795 crore during the week. However, they remain marginal net buyers of ₹578 crore in September so far. This indicates that foreign flows have weakened during the latest market decline but have not yet turned negative for the month.
Domestic institutional investors continued to provide strong support, purchasing shares worth ₹6,419 crore during the week. Their sustained buying helped absorb foreign selling and limited the decline in the benchmark indices.
NIFTY50 outlook
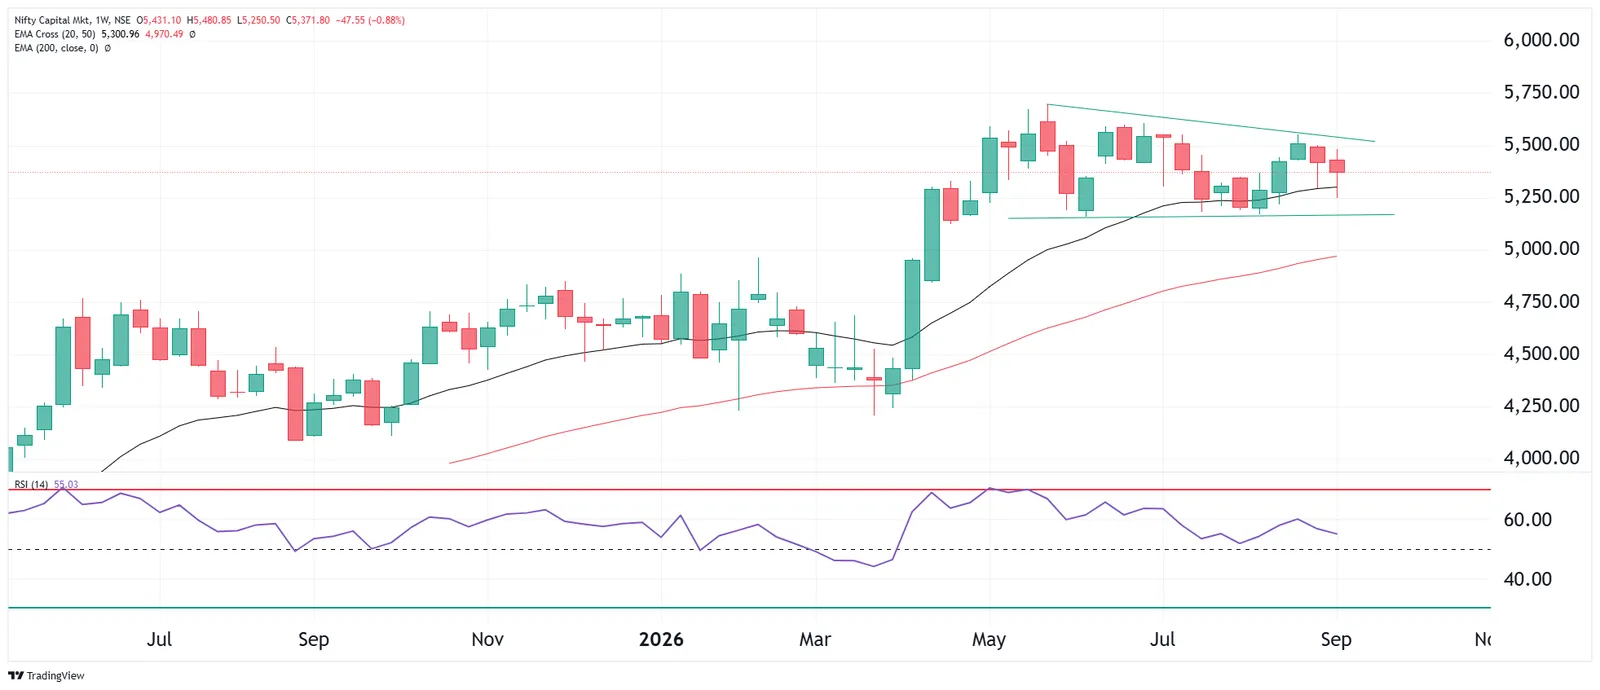
The NIFTY50 index remained below the important 23,606 support and its 20-day EMA and 50-day. With ADX rising to 29.84, the downward trend remains strong. However, Friday’s recovery from the intraday low shows some buying at lower levels, but it is not yet a trend reversal.
If NIFTY50 remains below 23,606, weakness could extend towards the next major support near 23,070. A recovery above 23,606 could trigger a relief rally towards the 23,900–24,040 moving-average zone. The index must sustain above this zone to show signs of stabilisation.
Disclaimer:
Derivatives trading must be done only by traders who fully understand the risks associated with them and strictly apply risk mechanisms like stop-losses. We do not recommend any particular stock, securities, or trading strategies. The securities quoted are exemplary and not recommendatory. The stock names mentioned in this article are purely to show how to do analysis.
About The Author
Next Story

