Personal Finance News
A Singapore-based NRI paid tax on ₹17.15 lakh LTCG from mutual funds, then discovered a rule making them exempt. What ITAT held
5 min read | Updated on October 19, 2026, 14:51 IST


SUMMARY
The ITAT ruling is relevant any non-resident Indian who pays tax in India and only later discovers a treaty benefit or a favourable decision
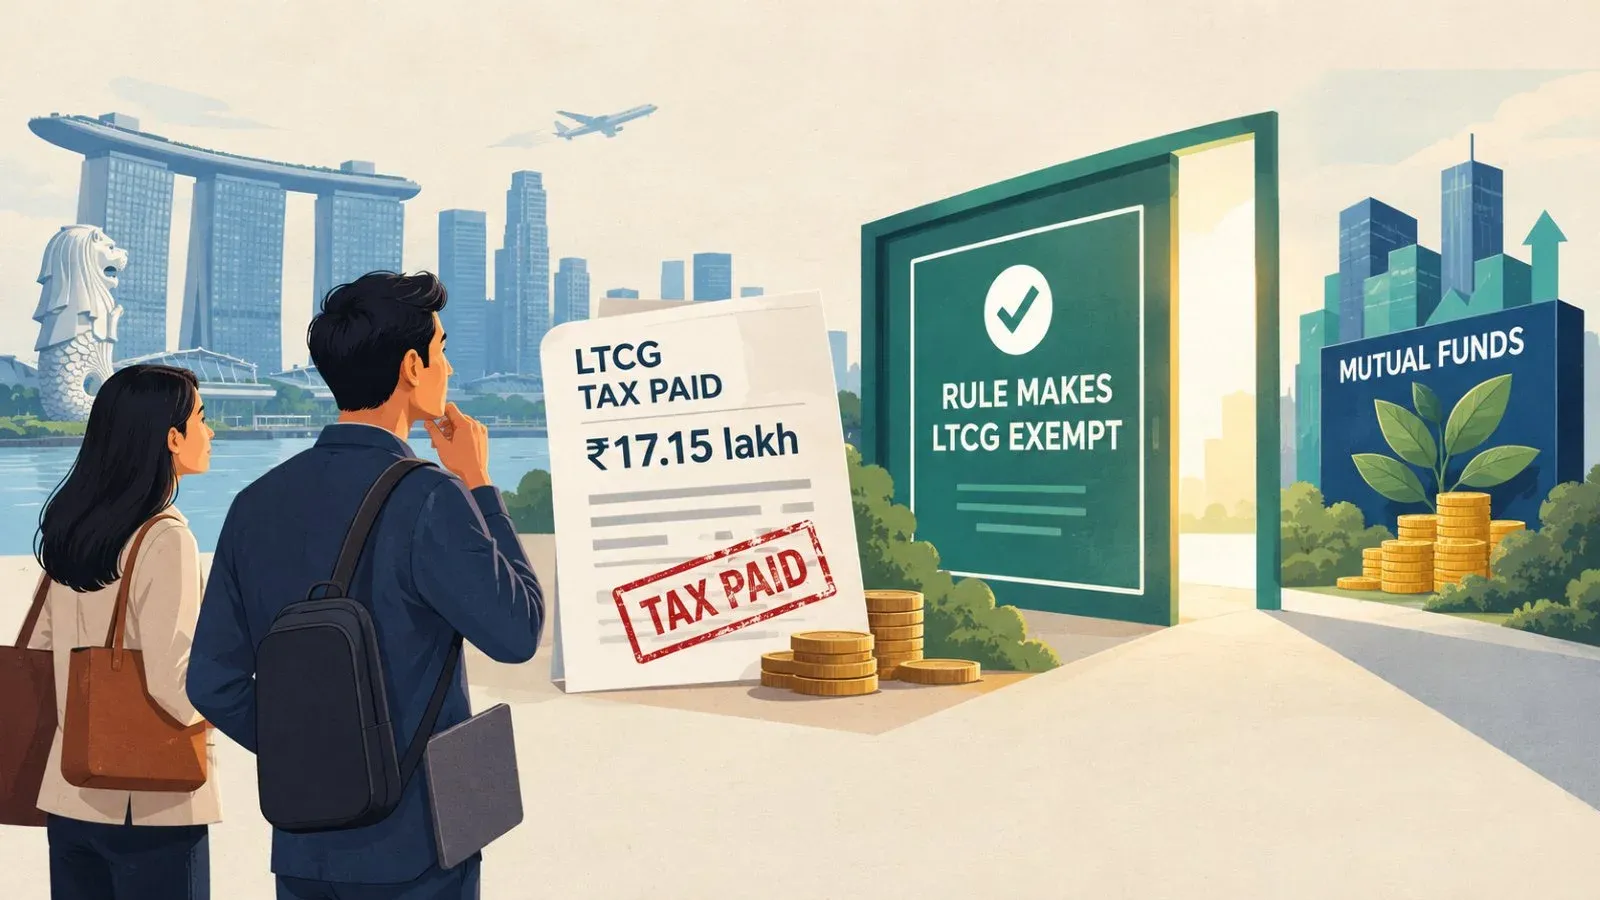
The tribunal noted that the NRI taxpayer had shown the capital gains as taxable in his return and later learn about the exemption rule. | Representational image/AI Generated
A non-resident Indian working in Singapore sold mutual fund units during the year and, in his return for assessment year 2024-25, offered the resulting long-term capital gain (LTCG) of ₹17,15,446 to tax in India. Months later after filing his return on June 26, 2024, he learnt of a tribunal ruling holding that such gains as exempt under the India-Singapore Double Taxation Avoidance Agreement (DTAA).
Based on the ITAT order dated October 12, 2026, this article explains key details of the case and takeaways for non-resident taxpayers.
Case history
Varun Hemant Keskar, an individual non-resident working in Singapore, and held a tax residency certificate for 2023-24 from the Singapore authorities. He filed his return under section 139 on June 26, 2024 in the capacity of a non-resident, declaring income of ₹17,73,990, which included capital gains of ₹17,15,446 on the sale of mutual fund units and other income.
The return was processed by the CPC on September 6, 2024, accepting the returned income as it was, without any adjustments. The capital gains were subjected to tax, producing a tax liability of ₹1,70,372, which was adjusted against his TDS credit.
Keskar then appealed, contending that the gains were not taxable in India by virtue of Article 13(5) of the India-Singapore DTAA, relying on a decision of the Mumbai ITAT in Mrs. Anushka Sanjay Shah v. ITO
The CIT(A) dismissed the appeal as not maintainable, on a jurisdictional point. Reading section 246(1)(a), it held that an appeal against an intimation under section 143(1) lies only where the assessee objects to the making of adjustments. Here, it found, the return had been processed purely on the data the assessee himself furnished, no adjustment under section 143(1)(a) had been made, and there was no variation or disallowance that could be called an adjustment.
"The grievance raised by the appellant does not arise out of any adjustment made by CPC, but arises from his own omission to claim DTAA benefit in the return of income," the CIT(A) held. Its view was that the remedy lay in a revised return under section 139(5), if within time, or in an application for condonation of delay under section 119(2)(b), and that "the appellate jurisdiction cannot be invoked as a substitute for these statutory remedies".
What the ITAT said
The tribunal took a different view of the appellate authority's powers. It noted that Keskar, a non-resident, had shown the capital gains as taxable in his return, and had later learnt of the coordinate bench's decision in Anushka Sanjay Shah, where the tribunal treated the impugned capital gain as exempt under Article 13(5) of the India-Singapore DTAA. He had then asked the CIT(A) for the same benefit.
The ITAT placed reliance on the Bombay High Court's judgment in CIT v. Pruthvi Brokers & Shareholder, where a new claim not made in the return was allowed. That judgment, in turn, explained the Supreme Court's decision in Goetze (India) Ltd: the issue there "is limited to the power of the assessing authority and does not impinge on the power of the Income-tax Appellate Tribunal under section 254".
The tribunal also noted its own recent decisions allowing claims raised for the first time before the CIT(A), including Prathibha Jagadish Unawane v. ITO and Makarand Prabhakar Abhyankar v. ADIT, CPC.
"Respectfully following the judgement of Hon'ble Bombay High Court in the case of Pruthvi Brokers & Shareholder (supra), we find force in the argument of Ld. Counsel of the assessee," the tribunal held.
The tribunal did not itself declare the capital gains exempt or order a specific refund. It set aside the CIT(A)'s order and directed Keskar to furnish a revised computation of his capital gain income before the jurisdictional assessing officer, who is to "re-compute the tax liability afresh and as per fact and law in the light of coordinate bench decision passed in the case of Mrs. Anushka Sanjay Shah (supra) and grant the refund, if any, arising to the assessee after due verification of documents".
The officer must give a reasonable opportunity of hearing, and the assessee has been directed to respond to the notices and produce his documents without seeking adjournments.
The takeaway
This ITAT ruling is relevant any non-resident Indian who pays tax in India and only later discovers a treaty benefit or a favourable decision. It confirms that an appellate authority can entertain a fresh claim not made in the return, and that the tax officer's inability to do so does not bind the appellate forums.
However, the relief can be procedural first. In other words, the assessee must go back with a revised computation and evidence, and the substantive benefit under the treaty will be applied only after verification.
Related News
About The Author
Next Story