
Personal Finance News
Insurance sold as fixed deposits, ULIPs pushed on the risk-averse: IRDAI's list of mis-selling and the proposed new rules to catch it
5 min read | Updated on September 25, 2026, 17:27 IST


SUMMARY
IRDAI said the reforms seek to strengthen safeguards against compulsory bundling of insurance with other financial products and services and address mis-selling through greater accountability.
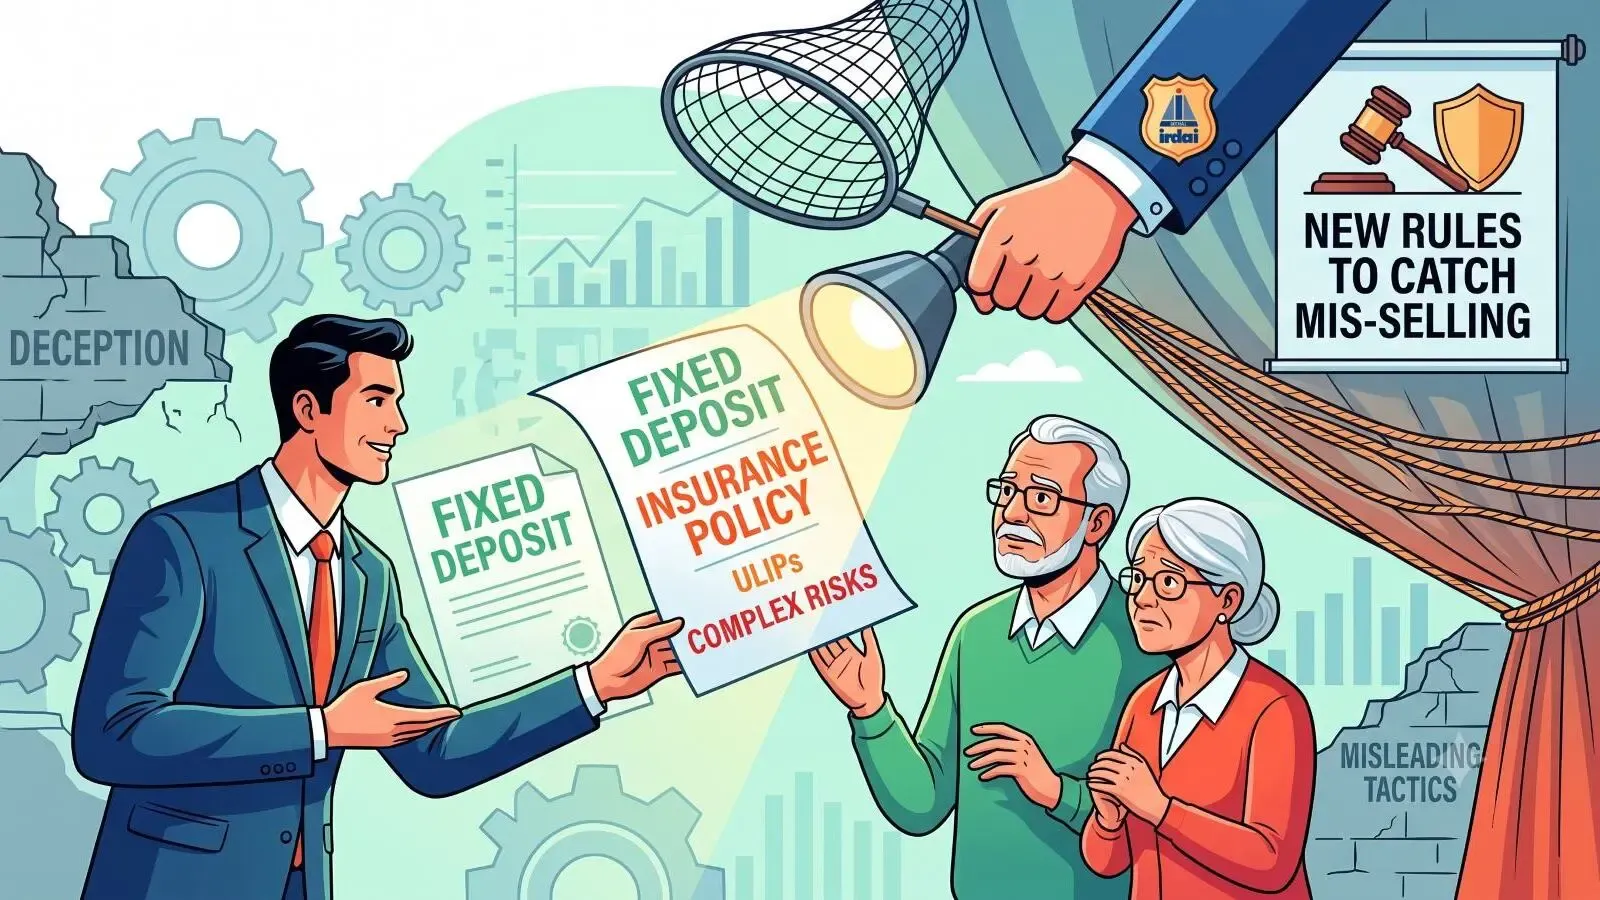
IRDAI flags mis-selling, proposes ways to curb it. | Representational image
For every rupee paid out as a death claim, nearly five rupees left insurers as surrender. The regulator read this pattern as a symptom of how policies are sold. Only 48% of life policies survive to the 61st month, while policies bought directly online show persistency of 71%, indicating that where a conscious and informed purchase is made, the policy tends to stay, the paper said. At some insurers, persistency falls as low as 8% by the 10th year.
“Unfair business practices have been a leading category of customer complaints. Amongst the various forms of such unfair practices, mis-selling is not uncommon and has significantly impacted public's trust in the insurance sector. This has also been a major cause of pre-mature surrender of life policies,” the consultation paper, released on Wednesday, September 23, 2026, said.
It added that "Persistency trends are also a clear reflection of significantly large pre-mature exits and possibly indicating poor solicitation”.
Where the ₹6.3 lakh crore of life insurance benefit payments went
| Benefit paid | Amount | Share |
|---|---|---|
| Surrender pay-outs | ₹2.33 lakh crore | 37% |
| Maturity benefits | ₹2.23 lakh crore | 35% |
| Annuity/pension and other | ₹1.26 lakh crore | 20% |
| Death claims | ₹0.47 lakh crore | 7% |
Getting out early of a life insurance policy is also the most expensive way to exit.
According to the paper, a participating policy surrendered in the very first year returns 33% to 57% of the total premium paid, and non-participating products return 31% to 64%.
Even in the fifth year, surrender values range between 61% and 84% of premium paid.
What you get back if you surrender, as a percentage of total premium paid
| Year of surrender | Participating products | Non-participating products |
|---|---|---|
| Year 1 | 33% to 57% | 31% to 64% |
| Year 2 | 35% to 61% | 37% to 69% |
| Year 3 | 51% to 65% | 44% to 74% |
| Year 5 | 61% to 74% | 64% to 84% |
The paper reveals that when policyholders complain, they often win. The paper term this as “an indicator of poor service quality”.
General insurance grievances rose from 78,347 in FY23 to 1,37,361 in FY25, with nearly 69% relating to claims.
In FY26, 63% of complaints disposed of on the Bima Bharosa portal were settled in favour of policyholders; 75% of claims disposed of at the Ombudsman's level went the customer's way, as did 54% of cases decided in consumer forums and courts.
What IRDAI has proposed
The paper has proposed a detailed suitability framework for every insurer and distribution entity.
“For life insurance sales above a defined ticket size, a documented needs and suitability analysis should be mandatory and supported by an appropriate audit trail,” it said, making clear that “mere customer consent or signature should not absolve the insurer or intermediary responsibility of selling an unsuitable product”.
IRDAI has proposed to ban volume-linked rewards for sellers.
“It is proposed to explicitly include all forms of remuneration, direct or indirect, monetary or non-monetary, within the definition of commission for regulatory purposes, and prohibit any volume linked or reward linked incentive for bank or NBFC staff selling insurance,” the paper said, noting that “sales incentives in the form of foreign or domestic trips, luxury gifts, milestone bonuses and contest rewards are currently common across the channel and create a direct conflict of interest with customer suitability”.
Every policy would also carry the traceable identity of the person who sold it. The paper proposes to tag the functional identity of the sales person with the policy sold, “and placing the information on incidences of mis-selling in public domain as a part of performance of the concerned person”. This will help prospective customers take “informed decision knowing the mis-selling history of the sales persons”. The paper added, “Mis-selling incidences should also lead to commission claw-back by insurers.”
The consultation paper also spells out what would count as mis-selling, with illustrations that include “selling insurance products as fixed-income deposits or high return investment products”, “selling ULIP products to customers who are risk-averse or beyond their working age without explaining mortality charges and risks to their capital and uncertainty of returns”, and “inducing customers to withdraw from an existing insurance policy or cancel the same with an offer for a new product on a misleading promise of better returns”.
In a press release accompanying the paper, IRDAI said the reforms “seek to strengthen safeguards against compulsory bundling of insurance with other financial products and services and address mis-selling through greater accountability”, including “linking the identity of the individual with the policy sold, placing information on mis-selling incidents in the public domain, and providing for commission claw-back in cases of mis-selling”.
The regulator has invited public comments on the proposals until October 25, 2026.
Related News
About The Author
Next Story

