
Personal Finance News
A 10-year-old can open a post office savings account. At 18, one missed step can freeze it
5 min read | Updated on November 20, 2026, 16:46 IST

SUMMARY
Minors are excluded from internet banking and from mobile banking, along with Joint A account holders, persons with mental illness or intellectual disability, and illiterate depositors.
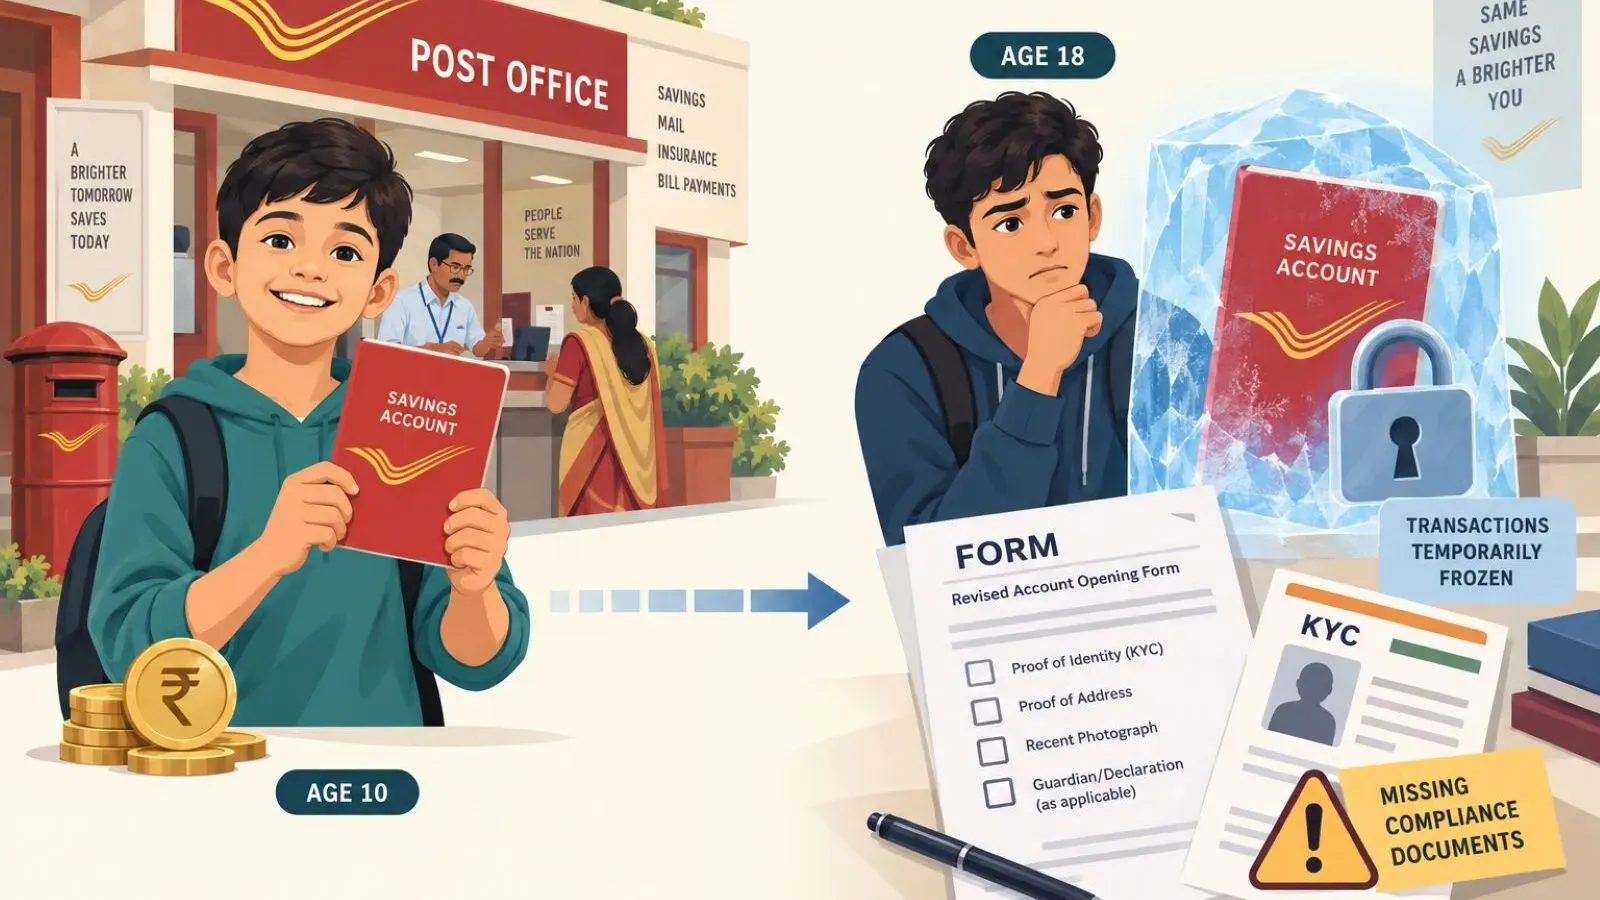
The age threshold for minor savings account in post office is not a mere formality. | Representational image/AI generated
What the manual allows
The manual’s chapter on savings accounts lists the categories that can be opened in the core banking system. One of them is "(e) a minor who has attained age of ten years, in his/her own name". The same paragraph says, "Single accounts can be opened by an adult or a minor of the age of 10 years or more."
This age threshold is not a mere formality as a later rule in the manual says that "no minor, however, has the right to open an account in his/her own name, unless and until he/she has attained the age of ten (10) years on the date of opening of the account."
| Route | Who operates the account | Key conditions |
|---|---|---|
| Child aged 10 to 18, in own name | The minor | Birth certificate mandatory; guardian's presence needed at opening only if the guardian is opening it |
| Child below 10, or any minor through a guardian | The guardian, until the minor attains majority | Guardian must be father or mother, or the person legally entitled to care of the minor's property; guardian's presence is mandatory at opening |
| Minor with an adult as joint holder | Not permitted | "A Joint Account in the name of a Minor and an adult shall not be opened" |
The guardian route for POSB account
Where a parent opens the account for a child, the system creates two customer records: one for the minor and one for the guardian, and the passbook carries a printed line: "To be operated through minor's guardian during minority of the depositor. The minor will attain majority on………….".
The majority date is calculated from the date of birth on the birth certificate.
Where the child operates the account himself or herself, the passbook carries the date of birth and the date of attaining majority.
A birth certificate is compulsory for a minor account. The manual says that if only the year of birth is known, July 1 of that year is taken as the date of birth. Where only the date is missing, the 16th of the month is used.
A minor who already holds a savings account in his or her own name cannot simultaneously have a guardian-operated account opened in the same name.
The rule that catches families at 18
The manual says, "Any minor of the age between 10-18 years, who opens account in POSB without guardian, has to submit revised account opening form (SB-AOF) on attaining the age of 18 years with fresh KYC documents. Otherwise, all transactions of such accounts will be frozen from the day he/she attains the age of 18 years."
For accounts opened through a guardian, the young adult must similarly fill in an account opening form, attested by the guardian or a person known to the post office, and present identity and address proof and a photograph. The system does the rest automatically.
"Once the minor attains majority, the status of account will automatically be shown as 'freeze' in FINACLE CBS Application," a note in the manual says, and the mode of operation is then changed to "self" so that the account holder can operate the account independently.
A declaration is also required to be signed. The account holder has, or will have within one month of turning 18, not more than one account in his or her own name at any post office.
The penalty for a false declaration is severe, including forfeiture of interest from the date of attaining majority to the date of closure of the extra accounts. Since an individual can hold only one single savings account across all post offices, a child who already had an account and then opens another on turning 18 runs into this rule directly.
What a minor's account cannot do
Minors are excluded from internet banking and from mobile banking, along with Joint A account holders, persons with mental illness or intellectual disability, and illiterate depositors. The account can still be run at the counter, and the manual allows a minor's single account to be opened with or without a cheque book, subject to the eligibility conditions for that facility.
Where a minor account fits
For a family already saving for a daughter, the Sukanya Samriddhi Yojana at 8.2% remains the higher-yielding option, but it locks money until she is 21. A minor's savings account is the opposite instrument: a liquid and low-yielding option, but useful for teaching a child to handle a passbook, an ATM-free account and a monthly allowance. A PPF account opened by a guardian, or a recurring deposit in the minor's name, sits between the two.
Related News
About The Author
Next Story

