
Market News
Week ahead: Oil prices, US 10-Year Treasury yield and NIFTY50 monthly expiry in focus

5 min read | Updated on September 27, 2026, 11:27 IST


SUMMARY
In the week ahead, investors will also track the US 10 year Treasury yield after it moved above 5% and Brent crude after it settled above $104 a barrel. The NIFTY50 index enters the week after a seventh consecutive weekly decline, with breadth in a washed-out zone, FIIs selling heavily and the index trying to defend the 23,070 support area.
Key things to watch in markets in the week ahead. image: Pixabay
Indian equities ended the week lower for the seventh consecutive time, marking their longest losing streak since 2020. The NIFTY50 index fell by 0.8% to reach 23,140, while the Sensex declined by 0.5% to reach 73,895. The week began with bargain buying as crude oil and US Treasury yields eased. However, the recovery weakened as IT selling, foreign outflows, and expiry-related volatility returned.
On Thursday, the decisive move came as the NIFTY50 index fell 1.6% and the Sensex lost 1.6%, with Brent crude moving above $100 a barrel and the US 10-year Treasury yield surging beyond 5%. Proposed changes to insurance commission rules put pressure on banks, NBFCs, insurers, and distribution platforms.
Meanwhile, the broader markets remained weak. The Nifty Midcap 150 fell by around 2%, while the Nifty Smallcap 250 dropped by approximately 0.7%. This showed that the pressure was not limited to index heavyweights. Although the domestic liquidity continued to cushion the decline, elevated crude prices, rising global bond yields and persistent foreign selling kept risk appetite subdued.
Sectoral performance was mixed relative to the 0.8% decline in the NIFTY50. The major outperformers were Realty (+2.9%), Pharma (+1.1%), FMCG (+1.04%), Metal (+0.2%), PSU Bank (-0.2%) and Auto (-0.5%). PSU Bank and Auto were classified as relative outperformers because their decline was less than that of the NIFTY50. Energy matched the benchmark with a weekly decline of 0.8%. The main underperformers were Banks, down 1.3%, Financial Services, down 1.6%, and IT, down 2.4%.
Uncertainty contributed to a 1.6% fall in Financial Services and a 1.3% decline in NIFTY Bank during the week. The market reaction on Thursday was severe. PB Fintech plunged 36%, while Max Financial Services fell 9.8%, HDFC Life declined 6.1% and ICICI Prudential Life lost 4.2 %. Among NBFCs, L&T Finance dropped 9%, Bajaj Finance 5.5 %, Cholamandalam Investment 5% and Bajaj Finserv 4.1%.
However, after oil markets closed on Friday, US President Donald Trump announced that he had rejected Iran’s proposal to reopen the Strait of Hormuz and end the fighting within seven days. This statement undermined expectations of an immediate diplomatic breakthrough, which could see part of the geopolitical risk premium restored when oil trading resumes.
Market breadth
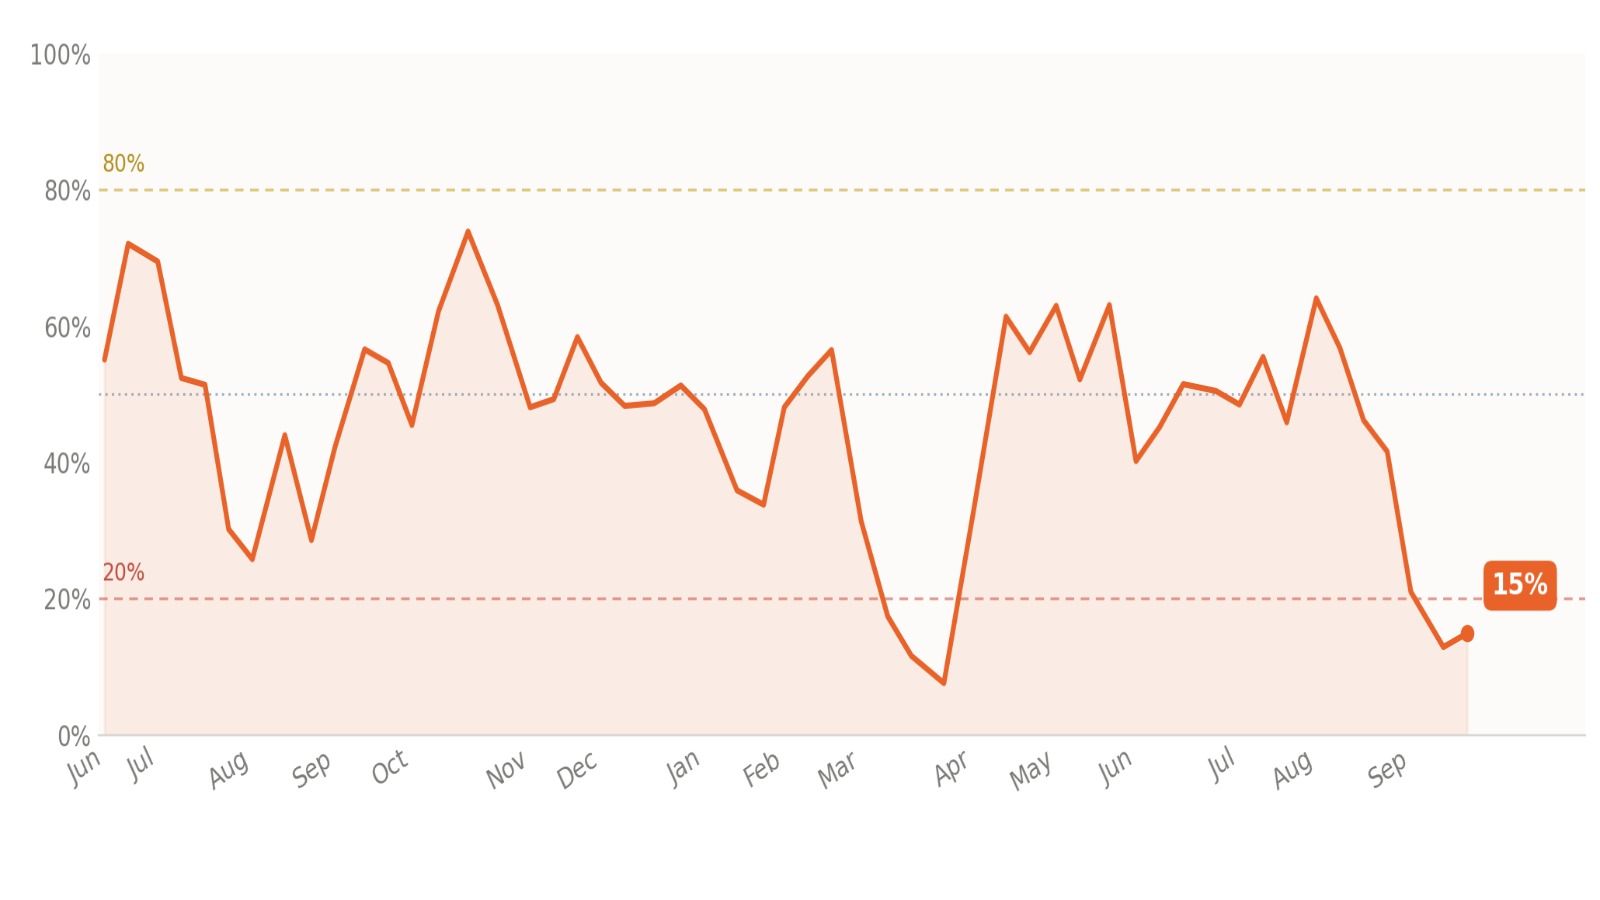
Market breadth remains deeply weak. Only 15% of NIFTY50 constituents were trading above their 50 day moving average, below the chart’s 20 % washed-out threshold and far below the 50% neutral line. Participation has deteriorated sharply from more than 60% in early August. Such an oversold reading can support a tactical rebound, but a durable recovery will require the share of stocks above the 50 day average to move back above 20% and then broaden towards 50%.
Foreign investors positioning
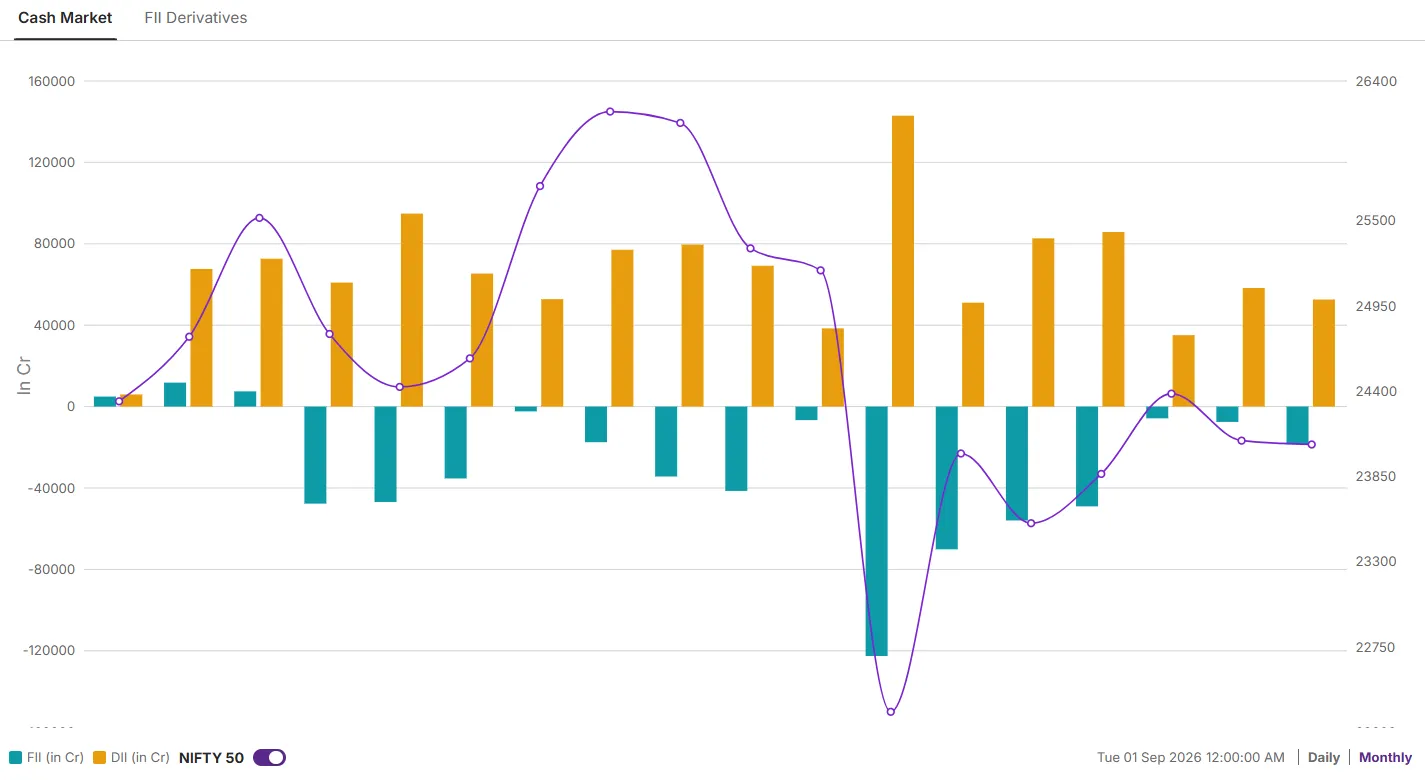
Cash-market flows remained sharply divided. During the completed week from September 21 to 25, FIIs sold a net ₹11,490 crore, while DIIs bought ₹16,398 crore. The pressure intensified on Thursday and Friday, when FII sales totalled ₹8,721 crore, DII purchases of ₹7,139.35 crore absorbed part, but not all, of that selling.
For September to date, FIIs are net sellers of ₹18,530 crore, compared with DII purchases of ₹52,616. FII selling has accelerated from ₹7,531 in August.
NIFTY50 outlook
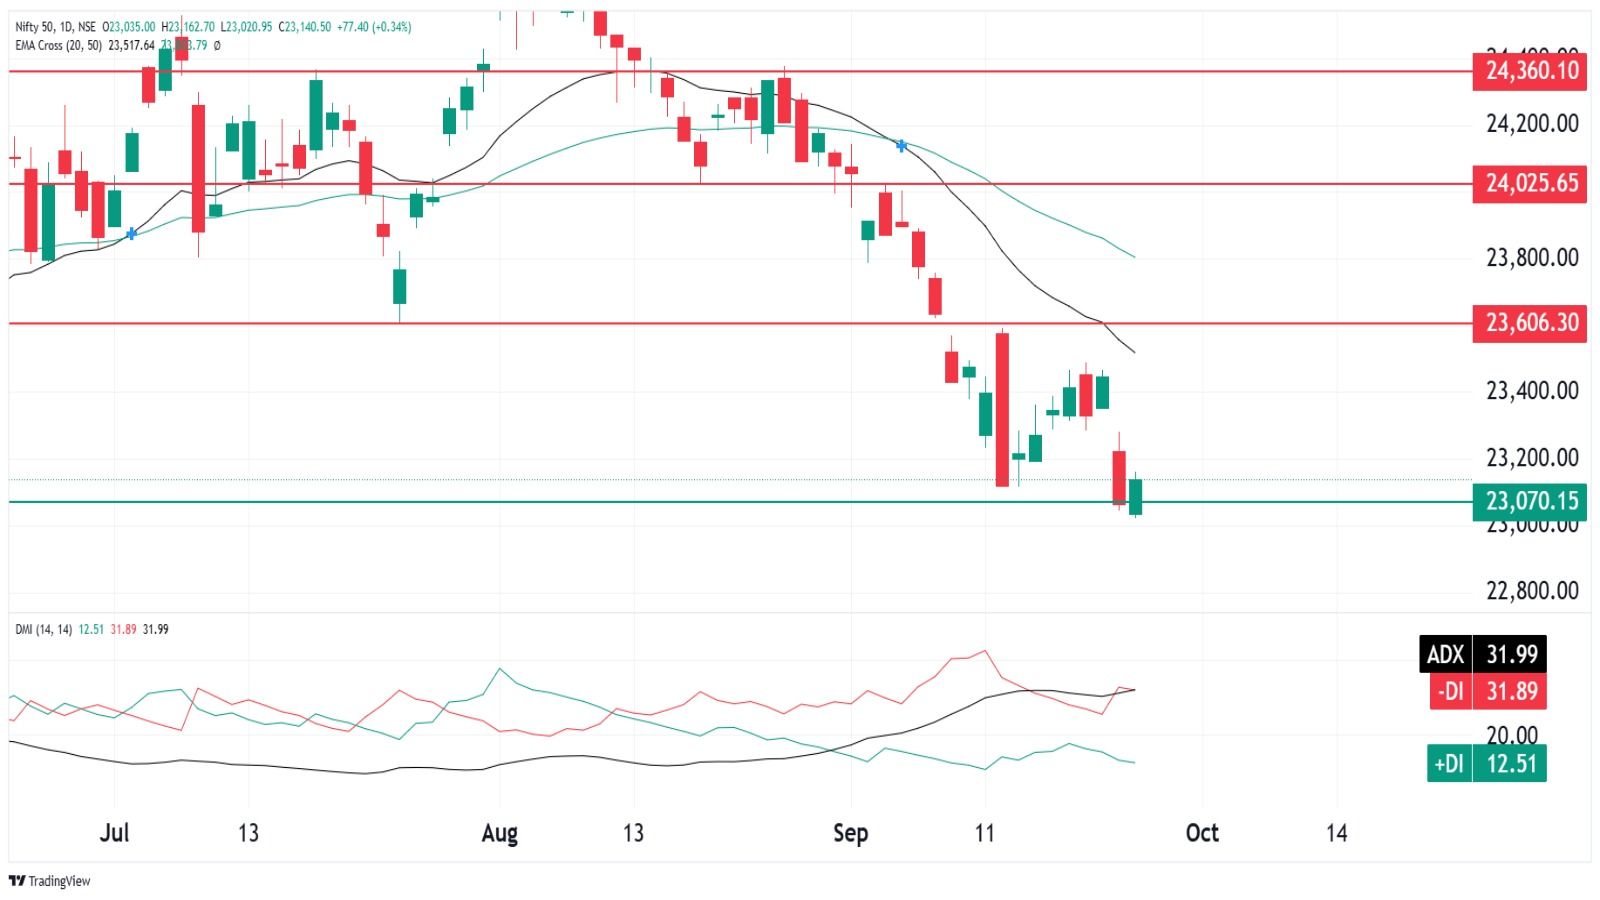
The NIFTY50 index remains in a clear short-term downtrend despite Friday’s rebound. The index is trading below its falling 20 day and 50 day EMA 9, while the sequence of lower highs and lower lows remains intact. Momentum also favours the bears as the ADX is at 31.99, suggesting that the prevailing downtrend still has strength.
The immediate support is 23,070, which the index tested during the week and narrowly defended on Friday. If this level holds, a relief move can first test the 23,518 to 23,606 band. A sustained close above 23,606 would improve the near-term structure. If 23,070 breaks decisively, the psychological 23,000 mark becomes vulnerable and the bearish trend is likely to resume.
Disclaimer:
Derivatives trading must be done only by traders who fully understand the risks associated with them and strictly apply risk mechanisms like stop-losses. We do not recommend any particular stock, securities, or trading strategies. The securities quoted are exemplary and not recommendatory. The stock names mentioned in this article are purely to show how to do analysis.
About The Author
Next Story

