Market News
Hyundai Motor India shares gain 6% despite a 24% YoY fall in Q2 net profits; turnaround potential ahead?
4 min read | Updated on October 29, 2026, 10:31 IST

SUMMARY
Hyundai Motor India shares surged on October 29 despite subdued profit growth in the Q2 earnings report. Here's what investors need to know about the turnaround potential of the automaker.
Stock list
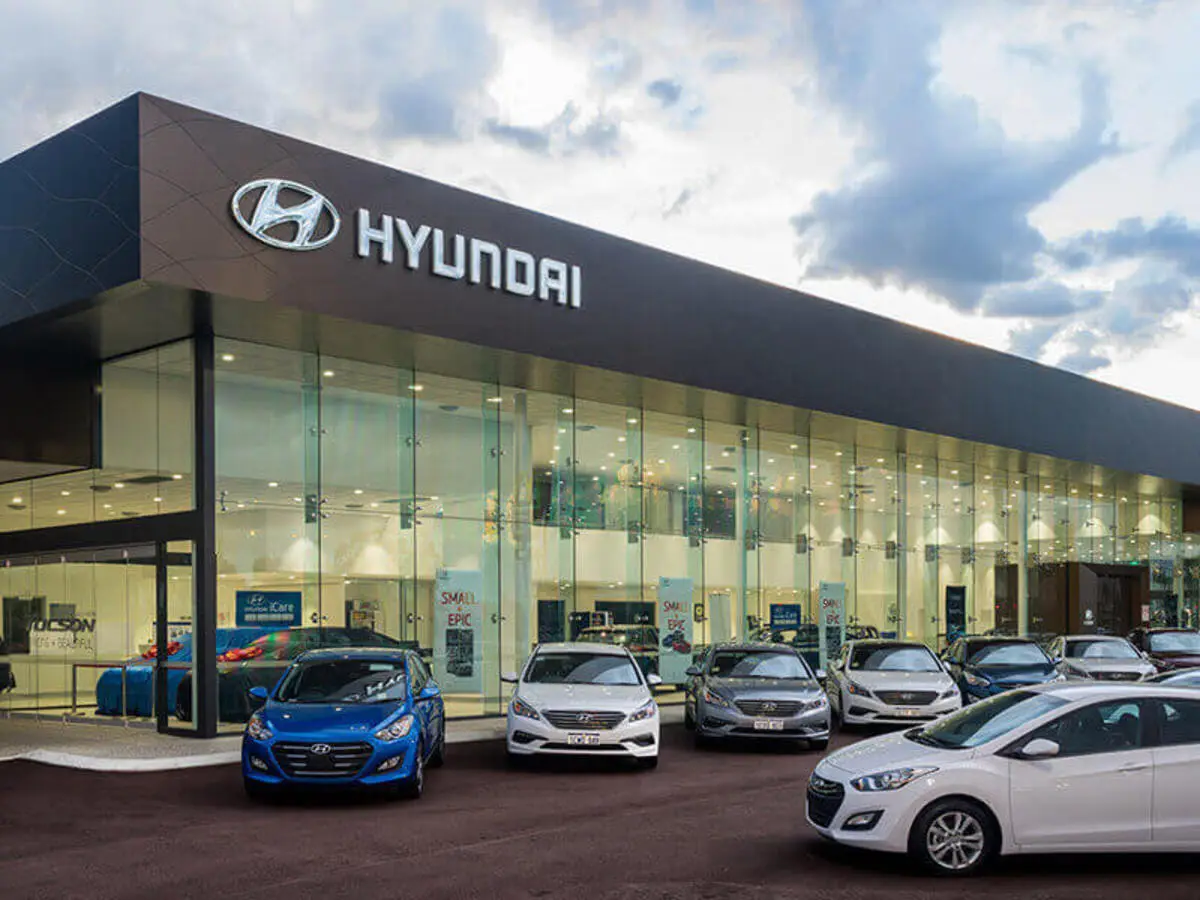
Hyundai Motor India shares jumped nearly 6% to hit an early market high of ₹1,973.80 on Thursday, October 29.
Hyundai Motor India shares surged around 6% after the opening bell on Thursday, October 29, as investors focused on the strong overall sales growth and the potential for a turnaround in the second half of FY27, despite a 24% fall in its consolidated net profits in the July to September quarter results.
NSE data showed that Hyundai Motor India shares jumped nearly 6% to hit an early market high of ₹1,973.80 apiece on Thursday’s market, in comparison to ₹1,866.90 apiece at the previous equity market close.
After hitting the early highs, the stock retracted some of its gains, trading 4.4% higher at around ₹1,949 apiece on October 29, as per the exchange data.
The elevated trading activity indicated the trigger for momentum gains in the early market hours on October 29, as investors focused on the management outlook highlighting a plan for margin recovery in H2 FY27.
The automaker’s management in its conference call with analysts also said that there are several key tailwinds, including the company’s Tamil Nadu initiative, price action, and export mix, which are set to power margin growth in the upcoming period.
Why did Hyundai’s Q2 profits fall?
In the Q2 earnings, Hyundai Motor India posted a 24% fall in its consolidated net profit after tax (PAT) at ₹1,196 crore in the July to September quarter (Q2) earnings report, in comparison to ₹1,572 crore in the corresponding quarter of the previous fiscal year, as per the exchange filing.
The data further showed that the automaker’s revenue from core operations advanced 18.5% year-on-year (YoY) to ₹20,696 crore in Q2 FY27, compared to ₹17,461 crore in Q2 FY26.
Although the company’s revenues surged 18.5% in the September quarter, the profits were pressured down by the sharp rise in the cost of raw materials and overall expenses in the same period due to the impact of the geopolitical crisis in West Asia.
Company filings showed that Hyundai Motor India’s overall expenses increased 24% YoY, largely due to a sharp 29% surge in raw material cost to ₹15,731 crore in the period under review.
The surge in the raw material cost also in turn impacted the overall operating profit of the company and the EBITDA margins in the September quarter. All of these factors combined impact the financial performance of the automaker in the Q2 results.
Turnaround potential ahead?
Hyundai Motor India’s management indicated a turnaround potential ahead as the automaker is set to witness tailwinds from the state government incentive scheme in Tamil Nadu, double-digit export growth potential, impact of the September price hike, and cost reduction initiatives, among other key factors.
“Looking ahead, we see H2 as a period of accelerated momentum for us,” said Tarun Garg, managing director and CEO of Hyundai Motor India. “We are also fully geared up for the launch of dedicated mass market EV in Q4 FY27.”
Market experts said that the Q2 earnings were largely in line with the estimates as the automaker has a potential for double-digit volume growth over next two years due to the new models in the market.
“2Q margins in-line with consensus; new model cycle to drive double-digit volume growth over next two years,” said Nomura analysts.
Citibank also retained its FY27 domestic volume growth guidance of 8–10% with expectations of models like Hyundai Bayon and upcoming mass-market EV launched to drive the company’s growth.
The company management also said that the commodity prices in the global market remains a near-term profitability risk for the company amid the risk of supply disruption looming over the exports business.
“We expect sharp recovery in H2FY27 margins, volumes and market share,” said Morgan Stanley analysts.
Related News
About The Author
Next Story