
Market News
Week Ahead: Jio IPO, Infosys earnings, Trump waives Russia sanctions and Crude oil in focus
5 min read | Updated on October 18, 2026, 12:39 IST


SUMMARY
In the week ahead, heavyweight earnings in India and the US, the Jio Platforms IPO and RBI meeting minutes will guide sentiment. Meanwhile, crude above $100 remains a risk for India after an IT-led market recovery.
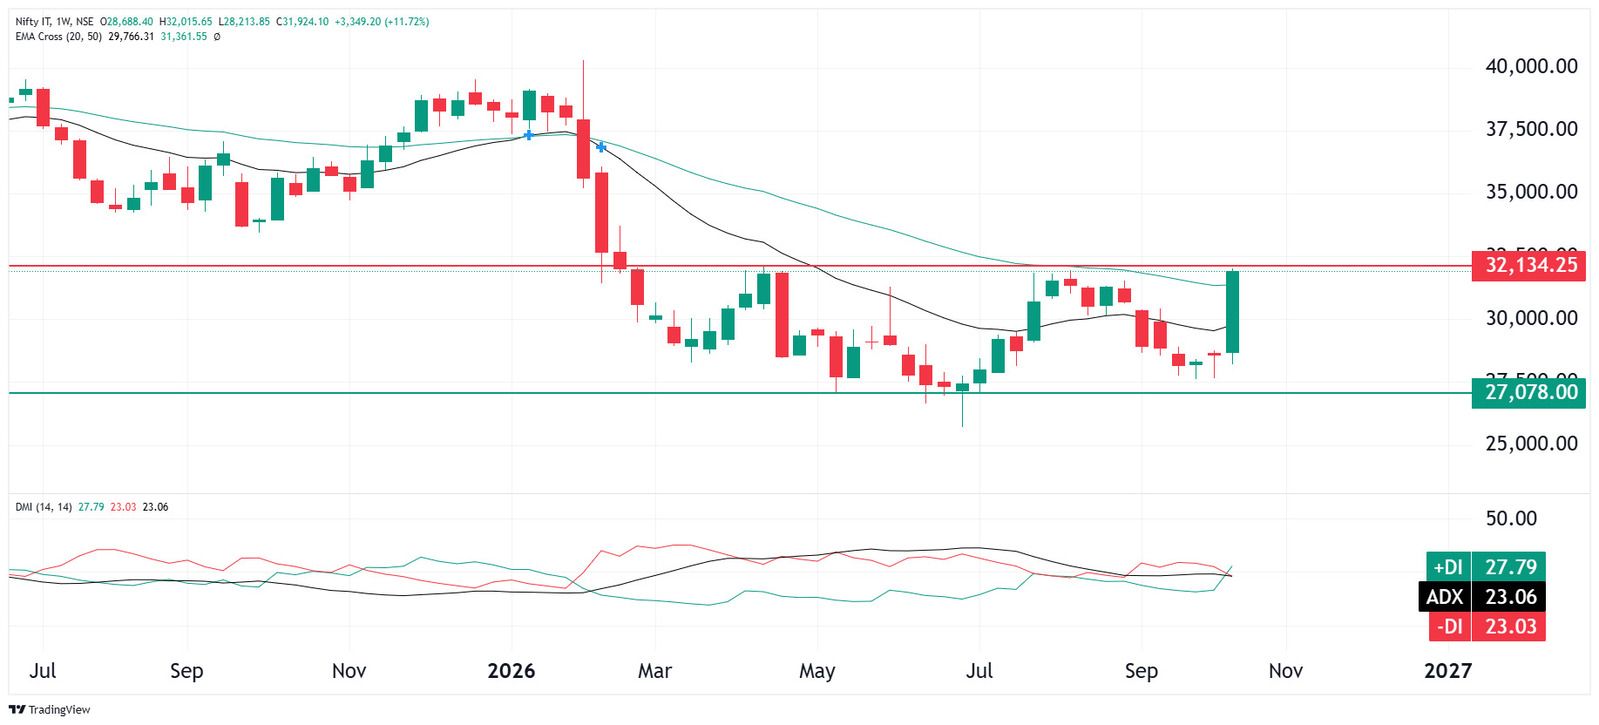
IT services will remain in focus after the NIFTY IT index rallied 11.7% during 12–16 October, its strongest weekly gain in nearly 18 years.
Indian equities rose for a second consecutive week. The NIFTY50 index gained 2.7%, to close at 23,146, while the Sensex advanced 3.1%, to 74,729. Better-than-expected revenue from major IT companies and a shift towards traditional software shares during the global AI-stock sell-off supported the recovery. Tech Mahindra, TCS, HCLTech and Infosys were among the prominent weekly gainers.
The recovery was concentrated in large-cap stocks. The NIFTY Midcap 150 gained 0.6%, while the NIFTY Smallcap 250 slipped 0.3% over the week, both lagging the NIFTY50 index. Friday’s gains came despite an initially weak session, with IT strength helping the benchmarks finish near the day’s highs. Higher oil prices and inflation continued to cloud the outlook.
Sector performance remained uneven. IT rose 11.7% and Automobiles gained 3.7%, outperforming NIFTY50’s 2.7% advance. Realty rose 2.7%, Oil and Gas 2.0%, Financial Services 1.68%, metals 1.10% and banks 1.06%, but all underperformed the benchmark. FMCG fell 0.5% and Pharma declined 0.6%.
Infosys’s results on 23 October will be the next major test for the sector. Attention will be on revenue guidance, new deal wins and management commentary on AI-related work. Barring the Persistent Systems (-1.7%), all the other stocks ended in green with Tech Mahindra (+8.5%), Wipro (+6.0%) and TCS (+4.9%) being the lead gainers.
US bond demand will remain important after the official 10-year Treasury yield fell to 5.09% on 16 October, from 5.24% on 9 October. Sustained easing in yields could help equity valuations and emerging-market sentiment. Separately, a US waiver of key Russia-related sanctions and tariffs, reported on 17 October, could reduce the immediate risk of new penalties affecting buyers of Russian energy, including India.
The offer consists entirely of fresh shares, with no sale by existing shareholders. Up to ₹27,500 crore of the proceeds is earmarked to repay or prepay borrowings of subsidiary Reliance Jio Infocomm.
Market breadth
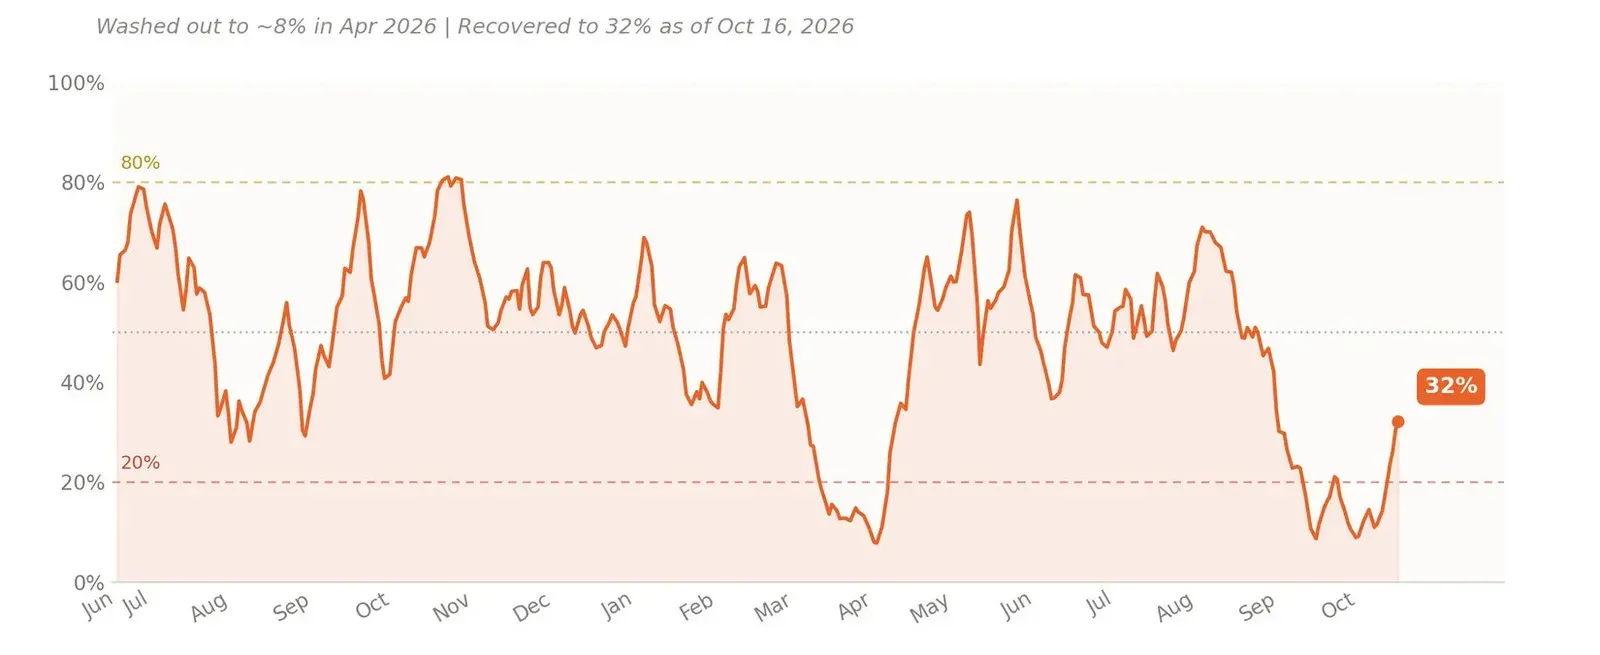
Market breadth improved, with 32% of NIFTY50 stocks trading above their 50-day moving average as of 16 October. This represents 16 out of 50 stocks, while the remaining 34 stocks, or 68%, were below or at that average. The move back above the chart’s 20% line shows that more constituents are joining the recovery. However, the reading remains below 50%, meaning most stocks have yet to regain their medium-term average.
Foreign investors positioning
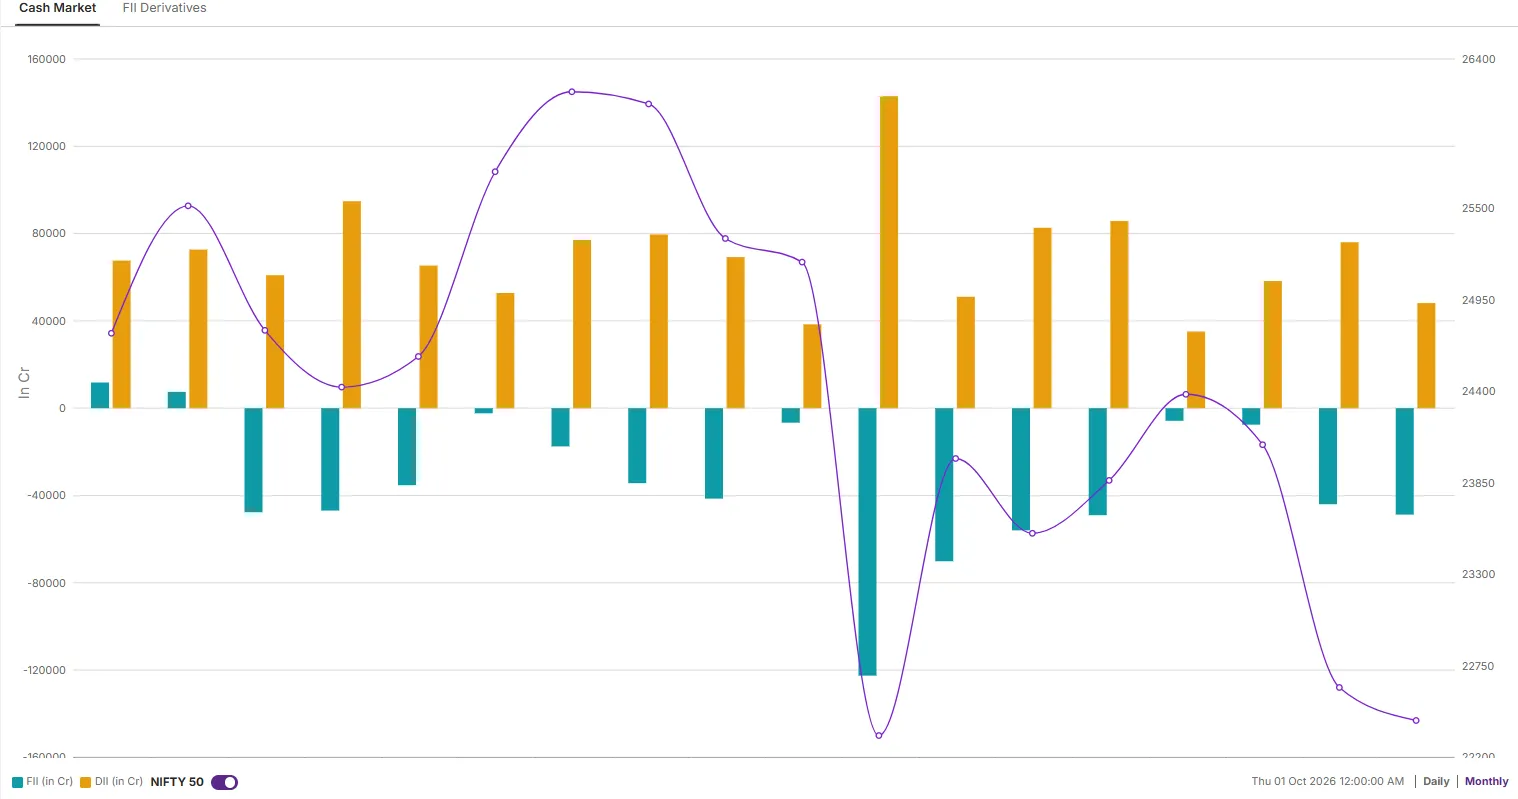
Foreign investors remained net sellers in the cash market, with October month-to-date selling of ₹48,769 crore. Continued outflows show that foreign investors have yet to turn sustained buyers despite the recent recovery in benchmark indices. Meanwhile, domestic institutions bought ₹48,168 crore over the same period, nearly matching foreign selling. This left the two investor groups with combined net selling of ₹601 crore.
NIFTY50 outlook
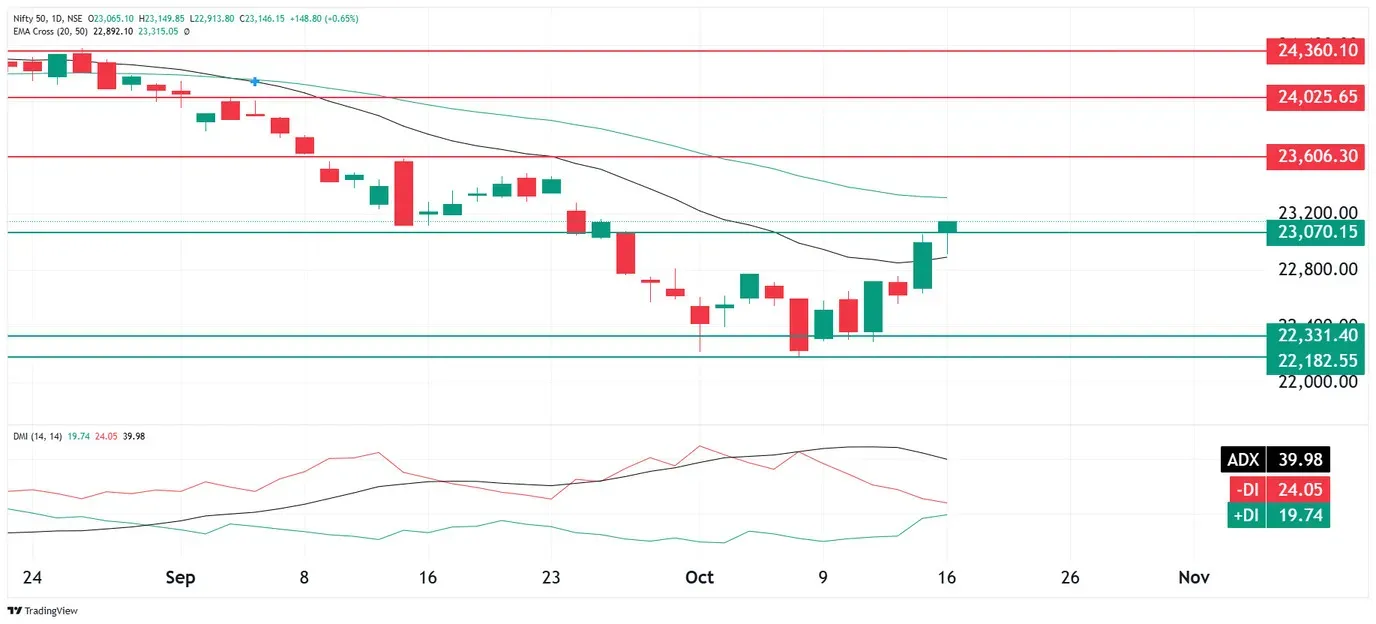
The NIFTY50 index extended its recovery, reclaiming the 20-day EMA. This improves the near-term structure, although the index remains below the falling 50-day EMA. Selling momentum has eased, the chart therefore supports an improving recovery, with a broader trend reversal still awaiting confirmation.
The 23,070 zone is the immediate support, followed by the 20-day EMA near 22,890. The deeper support zone lies at 22,331–22,183. On the upside, 23,315 is the first hurdle, followed by 23,606. If NIFTY50 sustains above the 50-day EMA, the recovery could extend towards 23,606. If it slips below 23,070, a retest of 22,890 becomes likely. A failure to hold that moving average would weaken the recovery.
Related News
About The Author
Next Story

