
Market News
Week Ahead: Fed minutes, Nvidia earnings and India’s inflation outlook in focus

5 min read | Updated on November 15, 2026, 09:30 IST

SUMMARY
In the week ahead, US retail sales, Federal Reserve minutes and Nvidia’s results will shape global sentiment, while India’s wholesale inflation release will test the domestic rate outlook.
In India, the October wholesale inflation is scheduled for Monday, November 16. | Image: Shutterstock
Indian markets extended their weekly advance, but lost momentum following the sharp rally of the previous week. The NIFTY50 added 0.4% to reach 25,144, while the SENSEX increased 0.7%, reaching 81,592. Sustained foreign buying and bank earnings supported the market during the holiday-shortened week.
However, Friday’s cool-off followed an increase in crude oil prices from their midweek lows, as well as October's retail inflation figure of 6.09%, which is above the RBI’s upper tolerance limit of 6%. This unexpected increase in inflation raised concerns about further monetary tightening by the RBI.
Meanwhile, broader markets outperformed the headline indices. The Nifty Midcap 150 gained 1.5%, and the Nifty Smallcap 250 advanced 1.9%. Sectorally, PSU banks led the way, supported by better quarterly results and credit demand. It gained around 7.5% as investors continued to respond to its earnings. The IT sector lost 3.1%, bringing an end to a six-week winning streak, as investors reassessed the global AI trade. The capital markets, media, banking and realty sectors also outperformed the NIFTY50's 0.4% return gaining around 2% to 5%. The auto, infrastructure, oil and gas, and FMCG sectors rose, but underperformed.
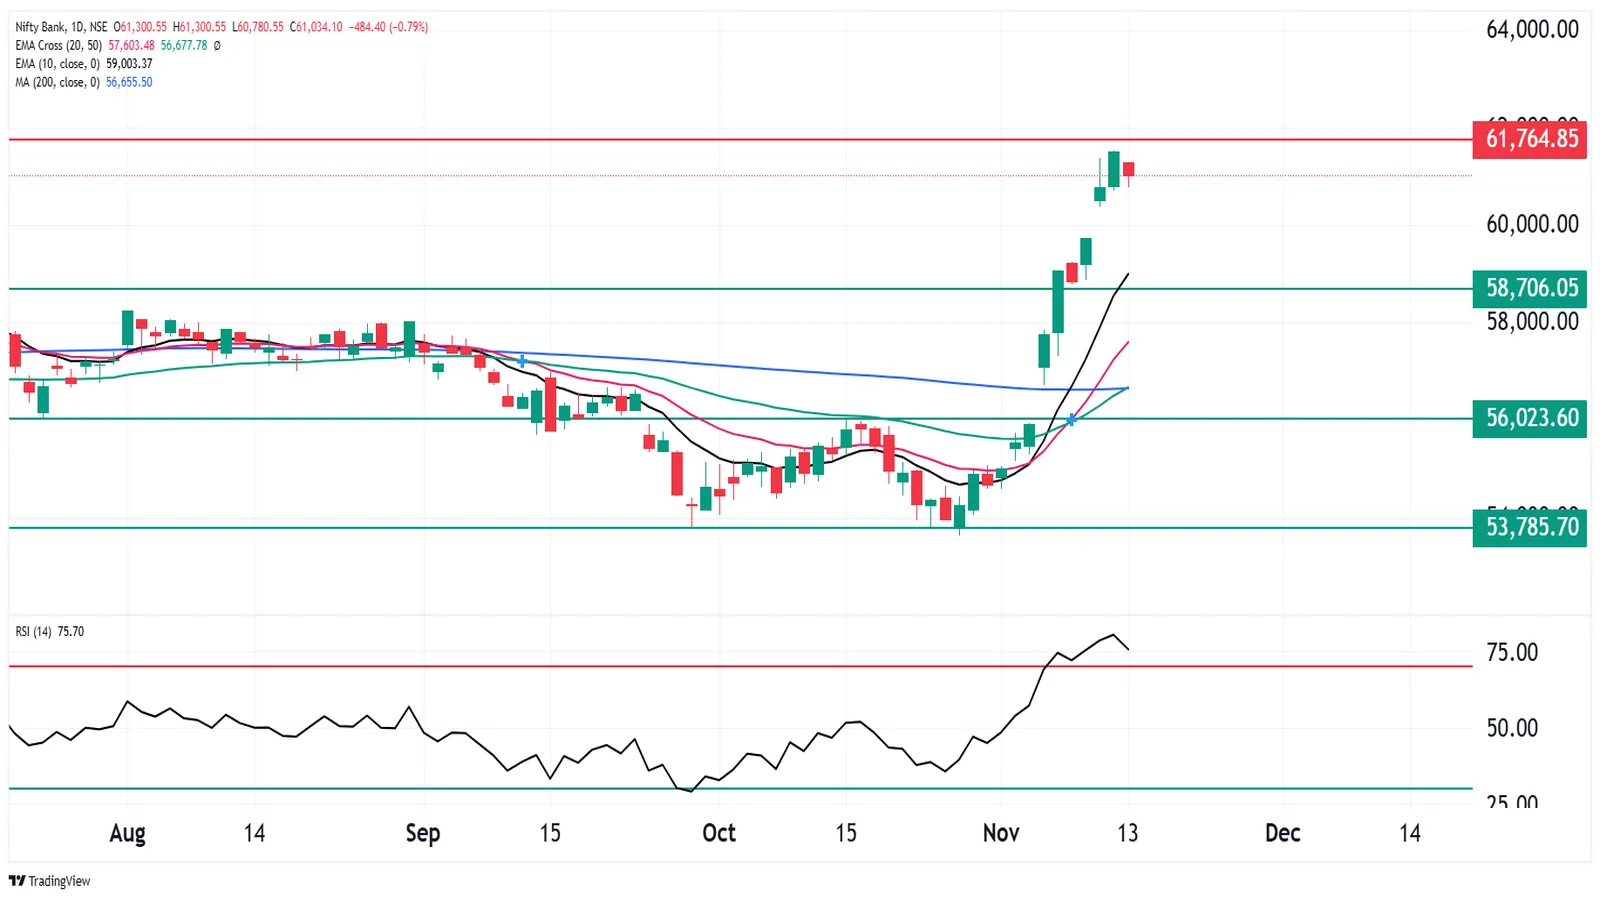
🛡️Spotlight: Banking shares gained as renewed foreign buying combined with stronger September-quarter interest income, improving asset quality and better loan growth. Recent downside move in crude prices through much of the week also improved sentiment towards the Indian economy. SBI received further support after management reiterated its loan-growth outlook in investor meetings. The buying extended across public and private lenders. PNB gained 12.8%, Bank of Baroda 9.4% and SBI 6.0% during the week, while HDFC Bank rose 2.0% and Kotak Mahindra Bank 1.7%.
The Nifty Bank gained 3.3% to 61,034, outperforming the NIFTY50’s 0.4% rise and finishing just 1.1% below its all-time high of 61,764. Both banking segments participated, with Nifty PSU Bank up 7.5% and Nifty Private Bank up 1.6%. The next test is whether buying continues near the record peak. October inflation of 6.09%, above the RBI’s upper tolerance limit, has increased concern about further rate hikes and contributed to Friday’s pullback.
🗓️Key events in focus: In India, the October wholesale inflation is scheduled for Monday, November 16. The market participants expect it around 12.1% year on year, compared with 11.39% in September. Following the 6.09% CPI reading, the main question is whether fuel and manufacturing prices signal further pressure on consumer inflation and margins.
Meanwhile, in the United States, the October retail sales and industrial production are due on Tuesday, November 17. Thursday’s initial jobless claims are expected at 1.97 lakh, against 2.00 lakh. These releases will show whether activity is moderating sufficiently to ease inflation pressure.
The Minutes of the October 27–28 Fed meeting are due on Wednesday, November 18. Investors will look for the conditions that could prompt another rate increase, while recognising that the minutes predate the latest inflation figures. Fed speakers and the response of US yields will also matter for the dollar and Indian equity flows.
📈📉Earnings blitz: In United States the Nvidia reports earnings on Tuesday, November 17, after the market close. Demand, margins, customer spending and guidance will be central after the company’s leadership change. Disney and Home Depot also reports on November 17. Walmart releases results on Thursday, November 19. The consumer companies will help test household spending and pricing power against elevated energy and borrowing costs.
🛢️Crude oil: January Brent settled at $95 a barrel on November 13, down 2.5% from $98 a week earlier. December WTI closed at $88, down 2.5% from $90. Growing supply and softer demand expectations outweighed the late-week rebound caused by attacks on Saudi infrastructure and tankers. The IEA’s November report said global supply rose by 23 lakh barrels a day in October to 10.54 crore barrels a day. It expects demand to fall by 27 lakh barrels a day in 2026 and the market to return to surplus in the fourth quarter. This supports a softer crude outlook, although diesel and freight costs remain elevated.
Market breadth
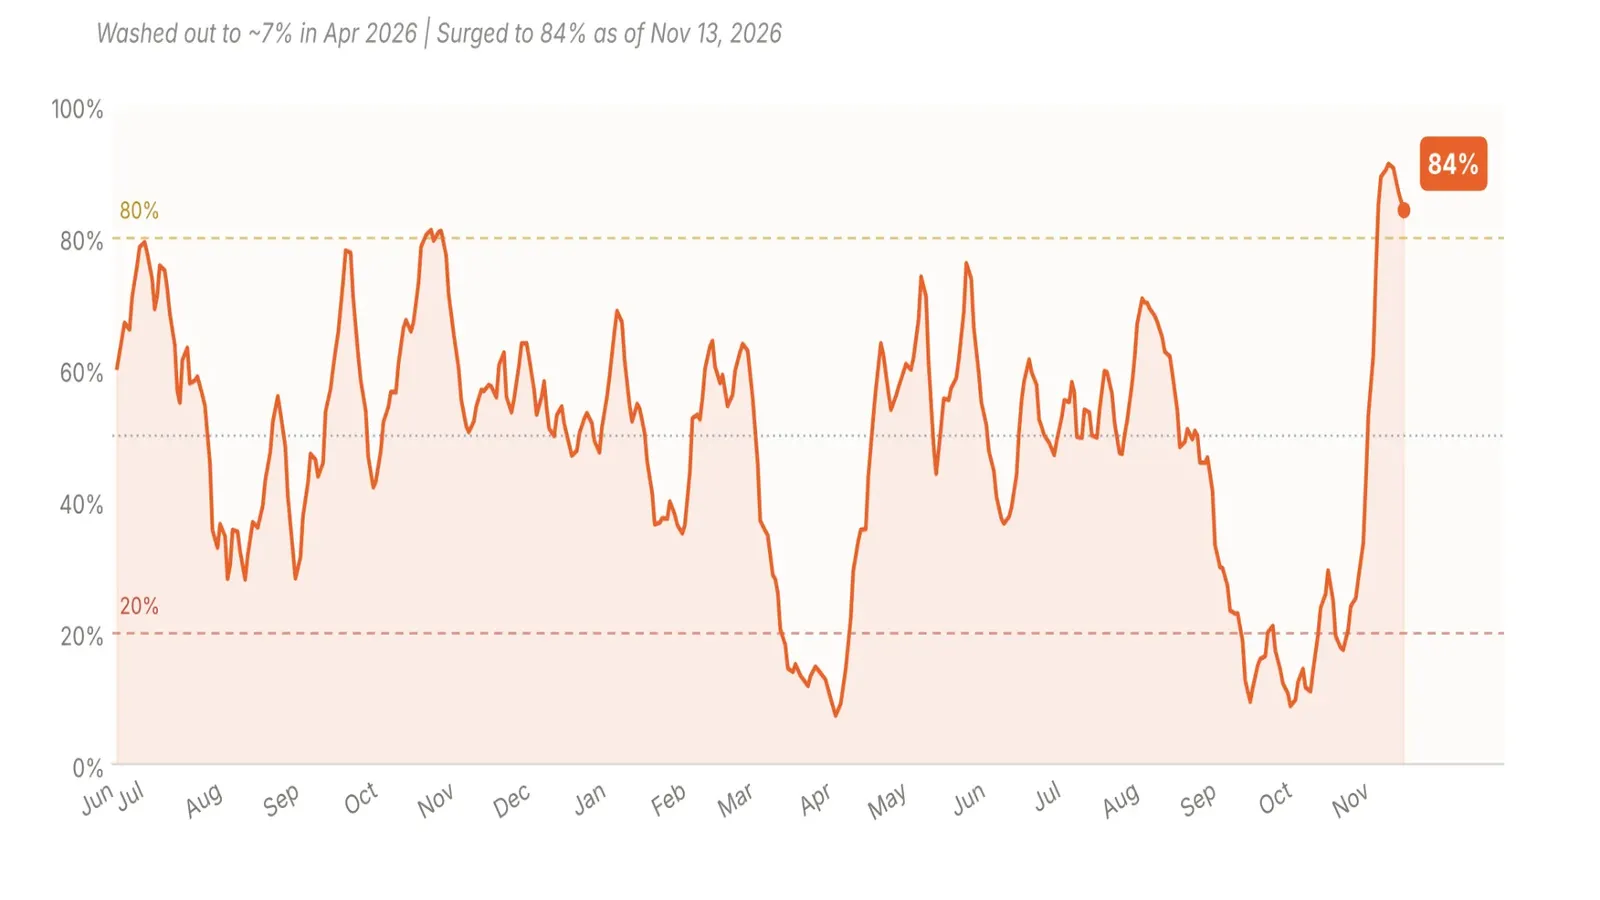
Market breadth remained strong, with 42 of 50 NIFTY50 stocks (84%) above their 50-day moving averages on 13 November, compared with 88% a week earlier. The four-percentage-point decline shows some cooling after the sharp rally, although participation remains above 50%.
Foreign investors positioning
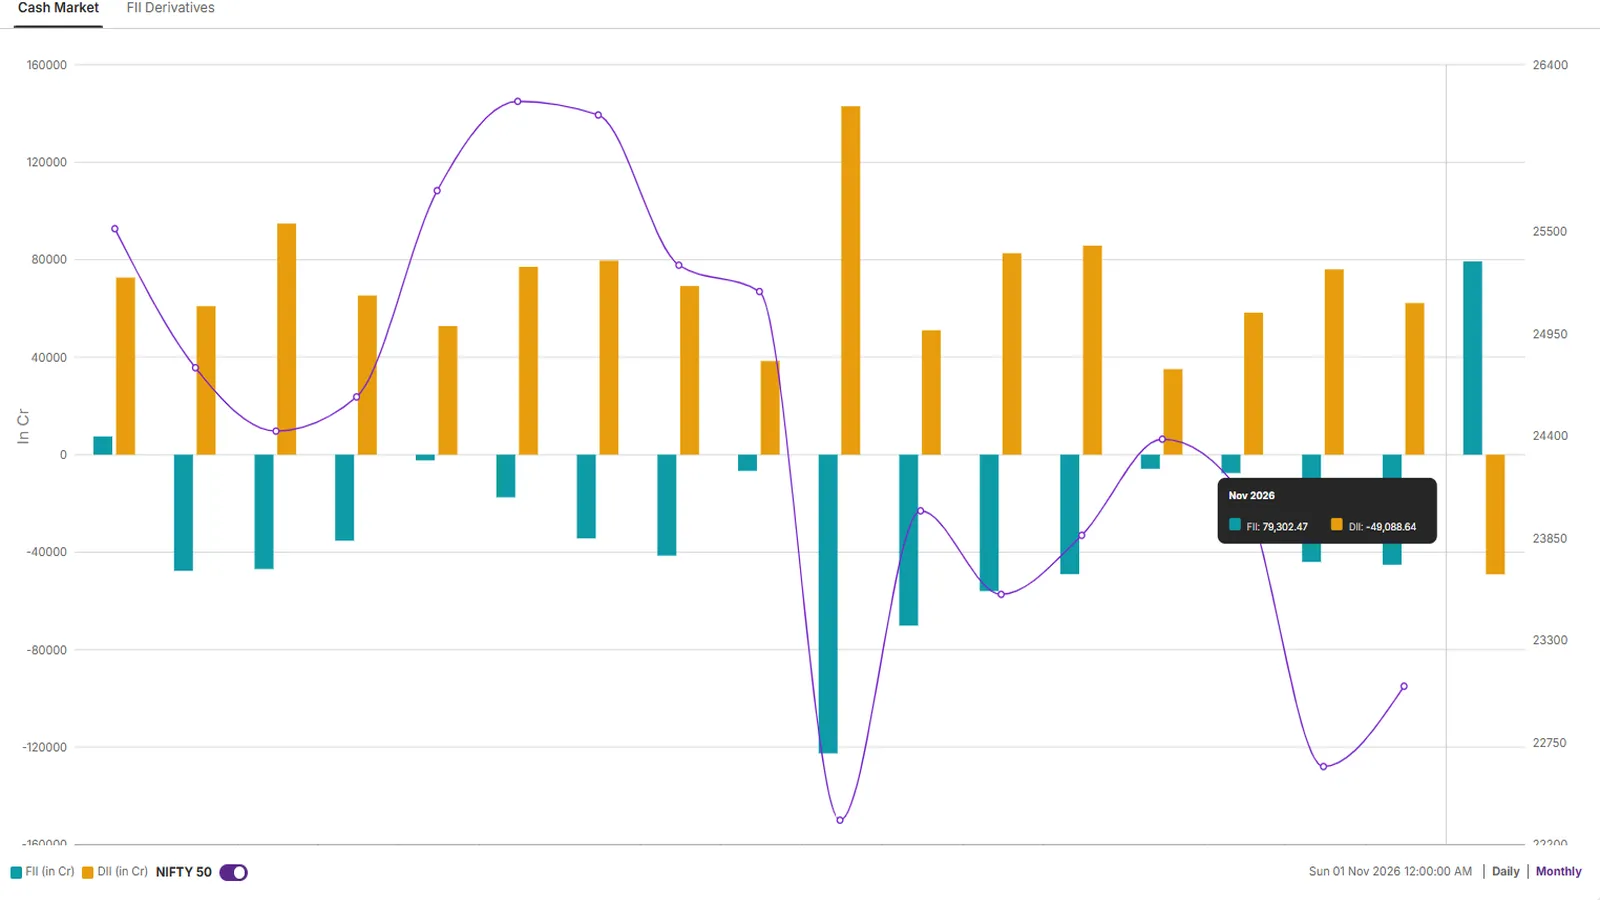
FIIs bought a net ₹33,342.45 crore in the cash market in the week ended 13 November, including the special Muhurat session on 8 November. This takes November month-to-date net buying to ₹79,302.47 crore. The continued foreign buying supported the market as the benchmark consolidated after the previous week’s sharp advance.
DIIs sold a net ₹24,892.12 crore over the same period, taking November month-to-date net sales to ₹49,088.64 crore. Foreign buying more than offset domestic selling, leaving combined net cash purchases of ₹8,450.33 crore for the week and ₹30,213.83 crore for November through 13 November.
NIFTY50 outlook
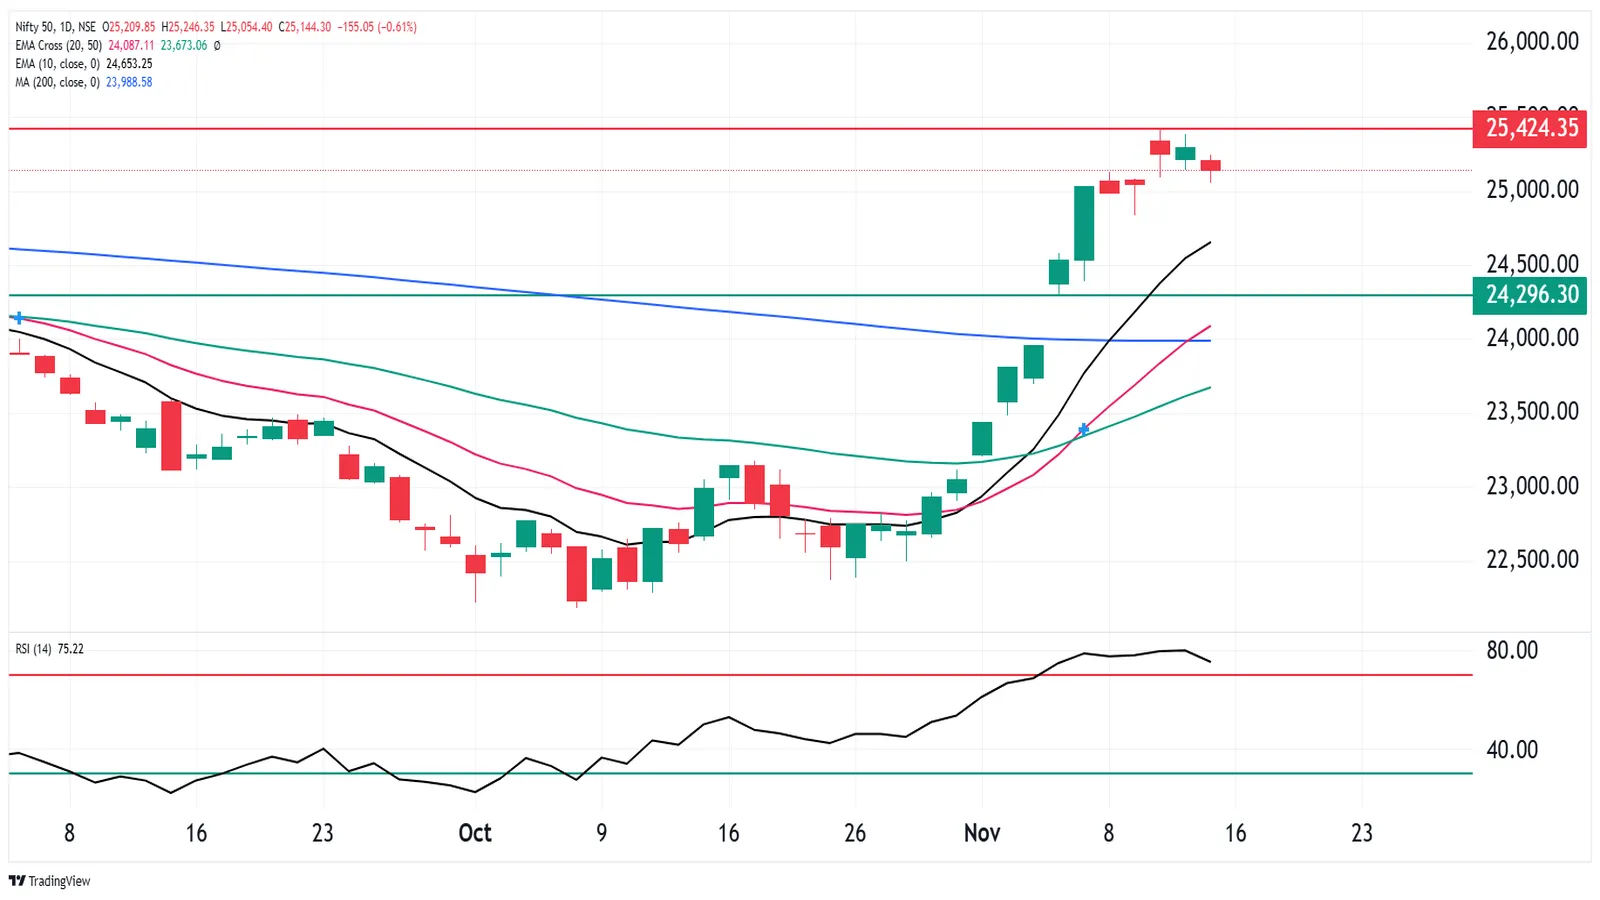
The NIFTY50 is consolidating following last week's sharp rally. The index remains above its rising 10, 20 and 50-day EMAs, as well as the 200-day SMA, signalling that the broader structure remains bullish. However, the RSI, which is down from near 80, is now at 75.22, showing that momentum is cooling from an overbought reading.
The recent high of 25,424 is immediate resistance. If the index closes above this level and sustains the breakout, the uptrend could continue. Conversely, if it closes below Friday’s low of 25,054, the pullback could deepen towards the 10-day EMA and then the support at 24,296. The 23,989–24,087 area, which contains the 200-day SMA and 20-day EMA, provides deeper support.
Related News
About The Author
Next Story

