
Personal Finance News
Inside Eminence SIF: 12 questions on Hybrid Long-Short Fund with AlphaGrep MF CEO Bhautik Ambani
16 min read | Updated on October 26, 2026, 15:12 IST


SUMMARY
AlphaGrep CEO says good risk management is ultimately about resilience rather than prediction. "We cannot eliminate uncertainty, but we can build portfolios that remain robust across a wide range of market environments."
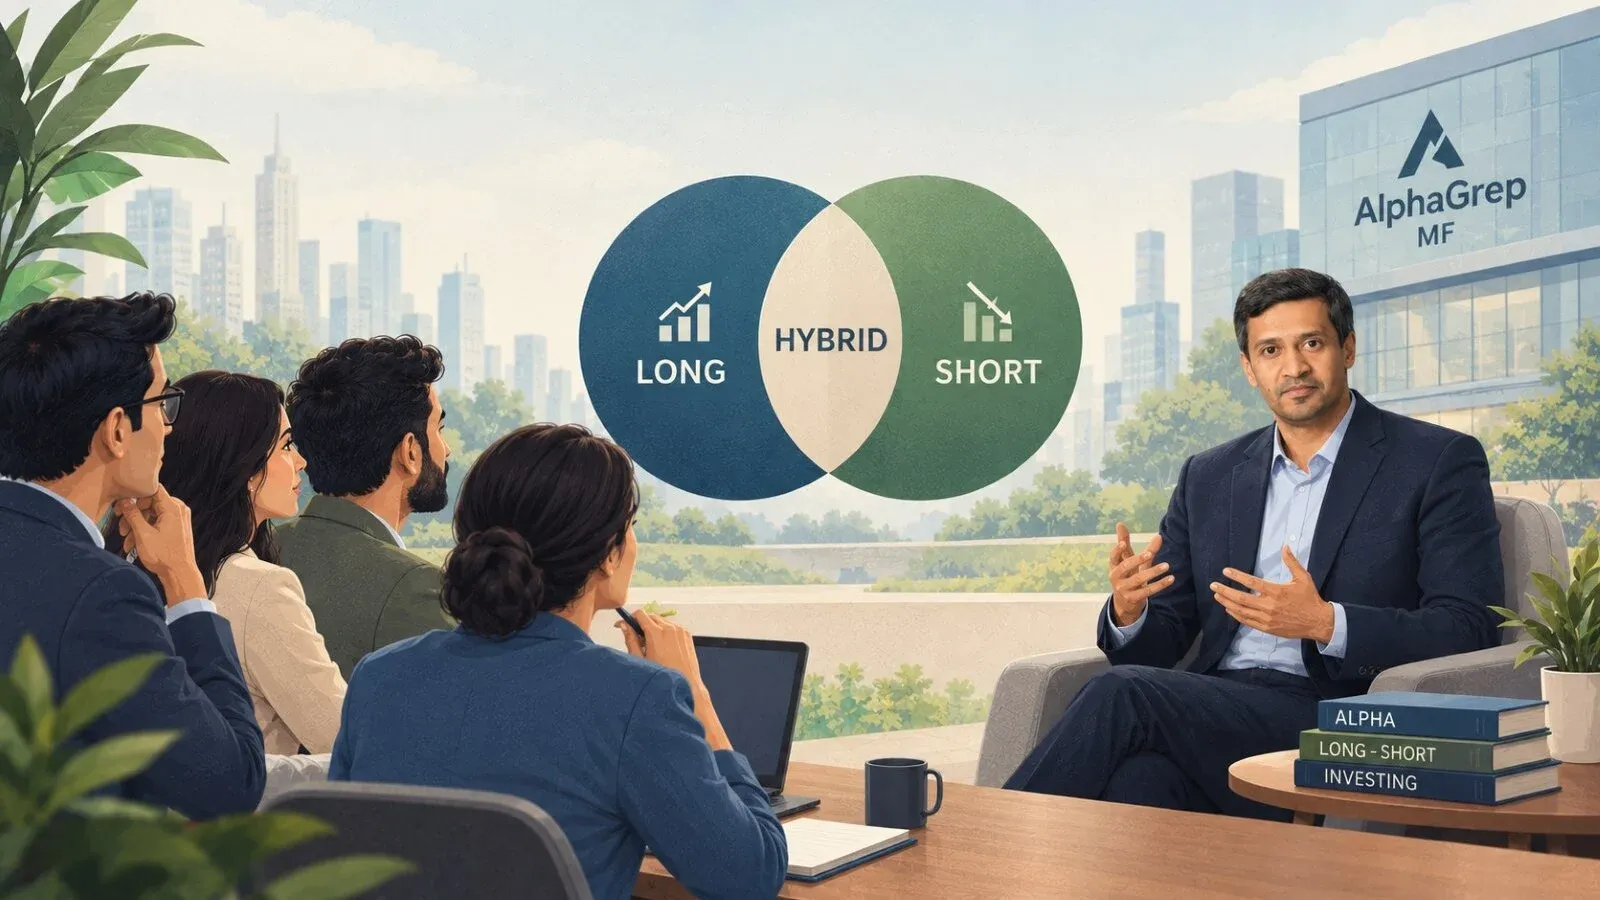
AlphaGrep MF CEO Bhautik Ambani says success for Eminence SIF will be defined by providing investors with a smoother investment journey across the full market cycle. | Representational image/AI generated
At its core, Eminence is built around an equity market-neutral long-short strategy—one that we've been running successfully in our AIF for around four years, and on our proprietary capital even before that. The philosophy hasn't changed; what has evolved over the years is the depth of our research, the breadth of our data and the sophistication of our execution.
The biggest advantage of a quantitative approach is consistency and scale. A discretionary manager can analyse a handful of companies in great depth. Our models evaluate hundreds of stocks simultaneously, combining information from financial statements, price action, derivatives markets and alternative data. Every investment decision is based on evidence that has been rigorously researched and tested rather than judgement or emotion.
AlphaGrep Group's research platform has been built over sixteen years. We don't rely on one model or one factor. Every research idea starts as a hypothesis, undergoes extensive testing across different market environments and only becomes part of the portfolio if it proves robust. We then combine hundreds of such independent signals into a diversified portfolio, while continuously controlling market, sector and factor exposures.
Technology is another important differentiator. We have built our own portfolio construction, execution and risk-management systems, allowing us to efficiently rebalance large portfolios while keeping transaction costs low. In strategies like arbitrage, execution quality itself becomes a meaningful source of alpha.
Ultimately, our edge isn't that we use computers instead of humans. It's that we have developed a disciplined investment process capable of analysing far more information, reacting more consistently and removing behavioural biases from investment decisions. That's difficult to replicate through a purely discretionary approach.
Our philosophy has always been that investment decisions should come from a repeatable process rather than changing market opinions.
In our Multi Asset Allocation Fund, asset allocation decisions are driven by quantitative models, while stock and commodity selection also follow systematic rules. Human judgement is reserved for exceptional situations such as corporate actions, liquidity events or market disruptions—not for overriding models simply because someone has a different market view.
Eminence follows the same philosophy.
The market-neutral long-short strategy, arbitrage book and covered-call framework are all driven by quantitative models with clearly defined risk controls. Human judgement plays a greater role in areas such as special situations and fixed income, where qualitative assessment can genuinely add value.
An important distinction is that we are not attempting to make large directional calls on where the equity market is headed. The flexibility lies in dynamically allocating capital across different investment styles depending on where we believe the best risk-adjusted opportunities exist.
As a result, we expect the strategy to maintain relatively low net market exposure through the cycle. We think of Eminence as an "arbitrage-plus" solution rather than a low-net-equity fund. The objective is to generate consistent returns with controlled volatility rather than participate fully in equity market rallies.
Successful quantitative investing is less about finding one magical factor and more about continuously discovering many independent sources of alpha.
Our research combines several layers of information. Traditional financial metrics remain important, but we also analyse technical indicators, derivatives data, market microstructure, sentiment and other alternative datasets. Increasingly, we use AI to help identify relationships and patterns that may not be immediately obvious through conventional research.
Every signal is evaluated independently before becoming part of a broader portfolio. Rather than relying heavily on a single investment style such as momentum or value, we combine a large number of relatively independent signals whose behaviour differs across market environments.
That diversification is one of the strongest defences against factor crowding.
We've seen how quickly crowded trades can unwind. Periods such as early 2025 reminded investors that strategies heavily concentrated in one style can experience sharp drawdowns when leadership changes. Our objective is not to predict which factor will outperform next, but to build a diversified research platform that can adapt as markets evolve.
Another important part of our research process is trying to disprove our own ideas. Models are stress-tested across different market regimes, subjected to out-of-sample and forward testing, and regularly reviewed because quantitative signals naturally decay over time. Research never really stops; the search for new sources of alpha is continuous.
The primary purpose of the short book is to support our market-neutral investment strategy. Rather than expressing a broad negative view on the market, we typically pair long positions in companies where we see attractive opportunities with short positions in stocks where our research suggests relatively weaker prospects. This allows stock selection, rather than market direction, to become the primary driver of returns.
The regulatory allowance for unhedged short positions provides flexibility, but it is not intended to become a directional bet. We expect the short book to remain firmly within the framework of a diversified market-neutral portfolio supported by strict exposure and risk limits.
One advantage of a multi-strategy approach is adaptability. Markets and regulations evolve, and investment processes have to evolve with them. We've experienced this before through changes in derivatives regulations and market structure. If the economics of one strategy become less attractive, capital can be reallocated towards other areas within the mandate, including arbitrage, covered-call strategies, special situations or fixed-income carry.
That flexibility allows the overall portfolio to remain resilient without becoming dependent on any single source of returns.
It's important to distinguish between the investment strategy and the investment vehicle. Eminence is not being built from scratch. The market-neutral long-short strategy that forms its core has already been run with real capital in our Category III AIF for around four years, and we have been deploying similar quantitative strategies on our proprietary capital for much longer. Our PMS has also been live for several years. That gives us confidence that the investment process has been tested not just in research, but in real markets.
At the same time, investors should recognise that the SIF is a different product with a different objective. The regulatory framework, leverage limits, liquidity profile and tax treatment are all different from an AIF. As a result, the portfolio construction and expected return profile are also different.
Rather than comparing returns across vehicles, I would encourage investors to focus on the things that genuinely carry over—the investment philosophy, the research capability, the robustness of the models, the risk-management framework and the experience of the team managing these strategies through different market environments.
One aspect we have always valued is capacity discipline. We've never believed that gathering assets should come at the expense of investment performance. Protecting the integrity of the strategy is far more important than maximising AUM, and that philosophy remains unchanged as we build our SIF platform.
Whenever a new category is launched, there is a temptation to judge it against traditional equity funds. We think that's the wrong comparison.
Eminence is designed as an arbitrage-plus strategy. Investors should expect it to behave differently from an equity fund because it is solving a different problem. The objective is not to maximise participation in rising markets, but to deliver relatively stable returns with low correlation to equities and shallower drawdowns across market cycles.
Naturally, the strategy will not outperform a fully invested equity portfolio during a strong bull market. That's a trade-off we are very clear about from the outset. Equally, in more volatile or declining markets, we would expect the strategy to demonstrate the value of maintaining low market exposure and multiple independent sources of return.
The regulatory benchmark is the prescribed hybrid index, but in practice we believe investors should judge the strategy on whether it consistently delivers attractive returns relative to the level of risk being taken. Consistency, capital preservation and diversification are likely to matter far more over time than outperforming an equity benchmark in any single year.
Ultimately, success for Eminence will not be defined by having the highest returns in one particular market environment, but by providing investors with a smoother investment journey across the full market cycle.
We think investors should start with the role a strategy plays in a portfolio rather than the label attached to it. Eminence is intended for investors who have a medium-term investment horizon and are looking for an alternative to traditional low-risk allocations such as arbitrage funds or short-duration debt funds, while accepting slightly higher risk in pursuit of better long-term outcomes.
It is not designed to replace an investor's core equity allocation, nor is it meant for someone seeking equity-like returns. Instead, it complements a broader portfolio by adding a source of returns that has relatively low dependence on market direction.
As portfolios become larger, diversification becomes increasingly important. Investors typically think in terms of growth assets and stability assets. We see Eminence sitting closer to the stability side of that spectrum—providing diversification while still seeking to generate returns above traditional cash management solutions.
The ₹10 lakh minimum means the product naturally caters to more experienced investors, but the underlying investment philosophy is straightforward: build a portfolio that is less dependent on whether the equity market happens to rise or fall over the next year.
Every investment strategy should be matched with the time horizon it is designed for. Eminence offers periodic liquidity and listed units, but it is not intended to be a substitute for a liquid fund where money may be needed at very short notice. Investors should approach it with at least a one-year investment horizon and view it as part of their strategic asset allocation rather than a tactical trading product.
That is also consistent with how the underlying investment strategies work. Arbitrage opportunities, market-neutral stock selection and special situations generate value over time, and investors are more likely to benefit when they allow the investment process to play out across different market conditions.
One of the advantages of the SIF structure is that it provides access to sophisticated investment strategies within a regulated mutual fund framework while still offering meaningful liquidity. For investors who understand the portfolio role it is intended to play, we believe that strikes a sensible balance between flexibility and long-term investing.
As with any investment, the product should not be evaluated purely on how quickly money can be redeemed, but on whether its characteristics align with the investor's objectives and the role it is expected to play within the overall portfolio.
Although all three products come from the same investment philosophy, they are designed to solve very different portfolio needs.
Our Multi Asset Allocation Fund is a core portfolio solution. It dynamically allocates across equities, fixed income and commodities using quantitative models to adapt to changing market conditions. The objective is to deliver equity-like wealth creation over the long term while reducing the volatility that investors typically experience in pure equity portfolios. It's a strategy we see investors holding through complete market cycles.
At the other end is our Category III AIF, which is designed for sophisticated investors seeking alternative strategies with greater flexibility. The regulatory framework allows higher leverage and a broader opportunity set, making it suitable for investors who are comfortable with a more institutional alternative investment approach.
Eminence sits between these two. It is not trying to replace either product. Instead, it occupies a distinct role as an arbitrage-plus solution built around a market-neutral long-short core, complemented by arbitrage, covered strategies, special situations and a conservative fixed-income portfolio.
In many ways, the three products complement one another. The Multi Asset Fund addresses strategic asset allocation, Eminence seeks to generate consistent returns with low market dependence, and the AIF offers greater flexibility for investors looking for a broader alternative investment mandate.
Rather than asking which product is better, investors should ask which problem they are trying to solve within their portfolio.
Cost matters, but cost should always be evaluated alongside the value being delivered. We are looking to cap the BER at 1.50% at the onset. The applicable expense ratio will be disclosed in accordance with SEBI regulations, and the exit load will be 0.50% for the first 30 days, NIL thereafter. The more important question, however, is whether investors are comparing strategies that are genuinely similar.
A market-neutral portfolio involving long-short investing, arbitrage, derivatives, risk management and continuous portfolio optimisation is fundamentally different from a traditional long-only portfolio. Evaluating two products purely on headline expense ratios can therefore be misleading if the underlying investment objectives and risk profiles are very different.
Similarly, PMS and AIF structures often involve performance-linked fees and operate under entirely different regulatory and tax frameworks. SIFs bring sophisticated investment strategies into a mutual fund structure with greater transparency, lower minimum investments than AIFs and more investor-friendly taxation.
Ultimately, investors should evaluate what they receive after costs—not simply what they pay before costs. The combination of returns, volatility, drawdowns, diversification and tax efficiency is a much more meaningful measure of value than expense ratio alone.
For us, risk management is not something that sits alongside the investment process—it is embedded within it. Every investment decision begins with an understanding of the risks we are taking. Before we think about expected returns, we ask how different market scenarios could affect the portfolio and whether those risks are adequately diversified.
The portfolio itself is diversified across a large number of long and short positions, while limits are maintained at multiple levels—including sector exposure, factor exposure, single-stock concentration, portfolio beta and liquidity. This ensures that no single theme or market event can disproportionately influence portfolio performance.
We also manage risk across multiple investment styles rather than relying on one strategy to generate returns. The long-short portfolio, arbitrage opportunities, covered strategies, special situations and fixed income each have their own risk budgets and operate within clearly defined exposure limits. If the opportunity set changes, capital can be reallocated dynamically without fundamentally altering the portfolio's overall objective.
Technology plays an important role as well. Our portfolio management, execution and risk systems have been developed in-house, giving us real-time visibility into exposures across strategies. Equally important, however, is human oversight. Markets occasionally experience events that models cannot anticipate—such as exchange disruptions or unexpected liquidity events—and experienced investment professionals remain responsible for governance and operational decision-making.
Good risk management is ultimately about resilience rather than prediction. We cannot eliminate uncertainty, but we can build portfolios that remain robust across a wide range of market environments.
One of the advantages of a quantitative investment process is that every strategy begins with clearly defined assumptions and measurable expectations. That means we are constantly comparing live performance against what the research suggested should happen under similar market conditions. A temporary period of underperformance is not unusual—every investment strategy goes through cycles. The more important question is whether the underlying behaviour remains consistent with the original investment thesis.
If the evidence suggests that market conditions have temporarily changed, we may choose to remain patient while continuing to monitor the strategy closely. However, if we conclude that the assumptions behind the model are no longer valid, we reduce capital allocation, modify the model or retire the strategy altogether.
We think of research as a continuous process rather than something that ends once a model is deployed. Markets evolve, data evolves and investor behaviour evolves. A successful quantitative platform therefore has to evolve continuously as well.
Perhaps the biggest misconception about quantitative investing is that models simply run on autopilot. In reality, a robust quantitative investment process demands constant research, ongoing validation and disciplined governance. Models generate investment decisions, but experienced people remain responsible for ensuring those models continue to deserve capital.
Related News
About The Author
Next Story

