
Personal Finance News
8th Pay Commission arrears: What the 5th, 6th and 7th CPCs did, and what employees want now

4 min read | Updated on October 13, 2026, 18:35 IST


SUMMARY
Much before the 8th Pay Commission, the 7th CPC managed to break the precedents on arrears set by 5th and 6th CPCs with its choice of effective date, which was January 1, 2016.
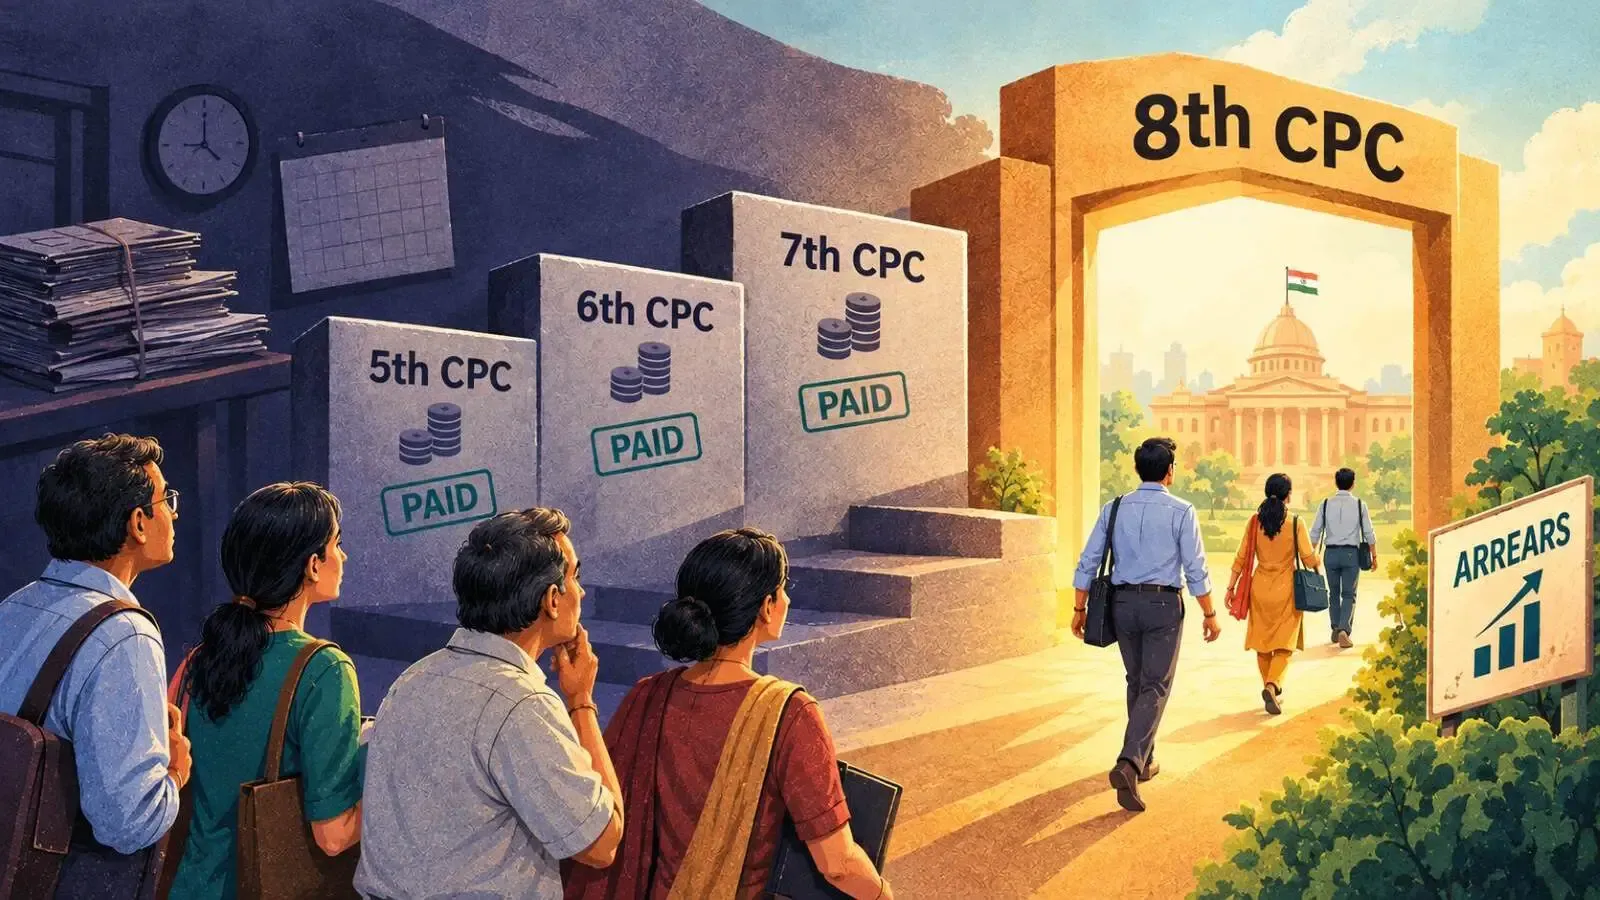
The higher the DA at the time of pay revision, the larger can be the share of the fitment as per 7th CPC formula. | Representational image/AI generated
Of the past three CPCs, the implementation of the 5th and 6th CPCs led to payment of huge arrears, causing short-term macroeconomic stress. The 7th CPC noted this, saying, "The awards of the previous Pay Commissions, both V as well as the VI, involved payment of arrears. If awards are made with an arrears component then the cumulative impact of arrears would temporarily increase government expenditure on PAP, thereby causing an appreciable shock, albeit for a short time."
It further said that this "shock impacts both fiscal stability and the price level through demand and supply channel."
However, the 7th CPC attempted to avoid any large economic shock, saying, "The Seventh CPC recommendations entail, at best, payments of marginal arrears and we do not therefore envisage any macroeconomic shock on this score," the report noted.
In defence, the payment of arrears in 5th and 6th CPCs also raised defence revenue expenditure.
“The implementation of the V CPC entailed payment of arrears. The first instalment of arrears was paid in 1997-98 and the second instalment in 1998-99,” the 7th CPC report said, adding that in those two years the share of pay and allowances in defence revenue expenditure rose to around 45% from 40-41%.
The 7th CPC managed to break the precedents set by 5th and 6th CPCs with its choice of effective date, which was January 1, 2016.
Did 7th CPC agree to staff side's demand?
No. The staff side had then asked for the early implementation of 7th CPC with effect from January 1, 2014, citing “substantial erosion in the value of wages owing to non-merger of DA, which has crossed the 100 percent mark in January 2014.”
However, the 7th CPC refused, saying it was constituted in 2014 and that “the ten year period gets over on 01.01.2016,” it “does not agree with the demand of early implementation”. The 7th CPC eventually recommended “that the date of effect should be 01.01.2016.”
How fitment factor ties to arrears to the pay structure
The 7th CPC's fitment factor of 2.57 was not just a flat raise. The report noted, “Of this multiple, 2.25 provides for merging of basic pay with DA, assumed at 125 percent on 01.01.2016, while the balance is the real increase,” which worked out to 14.2%.
The higher the DA at the time of pay revision, the larger can be the share of the fitment that is merely neutralisation. This is why the effective date, and the arrears it implies, are inseparable from the fitment debate.
Why this matters now
This matters now because the 10-year cycle since the 7th CPC ended on December 31, 2025, and the staff side has already asked for an effective date of January 1, 2026. While this demand aligns with the precedent already set by the 7th CPC, the implementation timeline of the 8th CPC is still a mystery.
More so because the 8th CPC is expected to submit its report by May 2027 as mandated by its official gazette notification, the government may take some more time to actually implement the report, or suggest changes. In such a case, even if the 8th CPC report gets government nod later in 2027, employees are likely to be entitled to arrears with effect from January 1, 2026. However, until then, they would be eagerly waiting for an official confirmation.
Related News
About The Author
Next Story

