Market News
Week ahead: Muhurat trading, India-US Inflation, Crude oil prices, FIIs activity among key market triggers to watch

6 min read | Updated on November 08, 2026, 13:18 IST

SUMMARY
Over the next week, investors will be keeping a close eye on a number of key events, including India’s October inflation figures, US consumer and producer inflation figures, the Muhurat trading session, a shortened domestic trading week, and another round of India-US earnings reports.
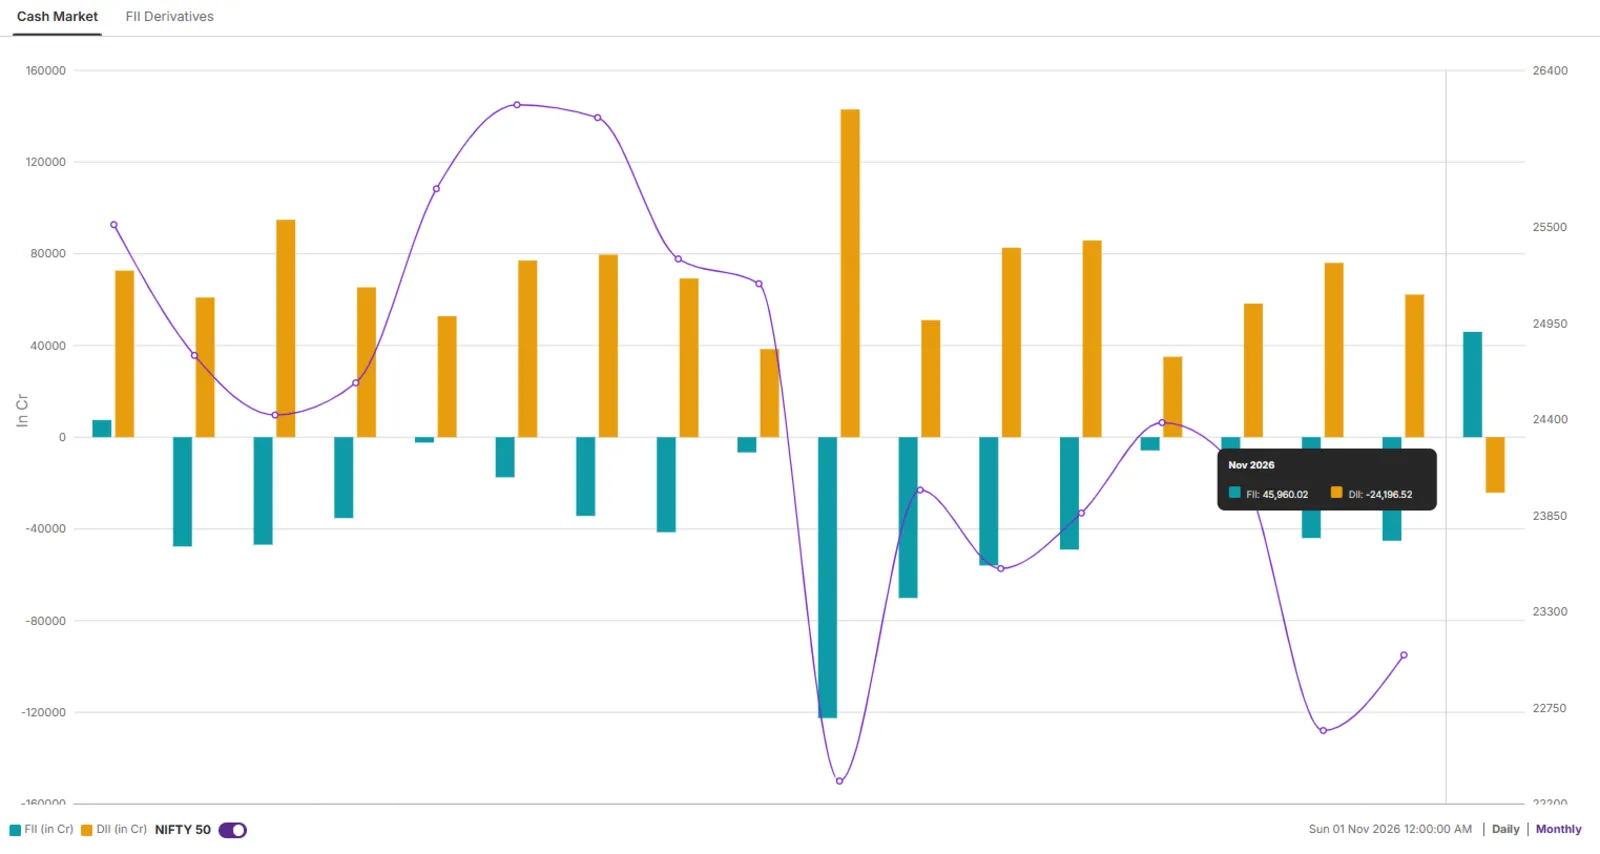
FIIs bought a net ₹45,960 crore in the cash market between November 2 to 6.
Indian markets rose in all five sessions, marking their strongest week in almost six years. The NIFTY50 increased by 1,977 points (8.5%) to close at 25,030. Meanwhile, the SENSEX advanced 6,568 points (8.8%), to reach 81,028.
The move was driven by falling crude prices, sustained foreign buying, strong results from large companies, and buying in private banks and Reliance Industries. India also remained relatively resilient during the global technology sell-off because its benchmark indices have limited exposure to capital-intensive AI infrastructure companies.
The rally was broad but clearly led by large caps. The Nifty 500 gained 7.1%, while the Nifty Midcap 150 rose 5.8% and the Nifty Smallcap 250 added 3.7%. Midcaps and smallcaps therefore participated but lagged the NIFTY50. The narrower leadership reflected the concentration of foreign buying in liquid index stocks.
Sectorally, Capital Markets (+10.7%), Financial services (10.4%), Real-Estate (+10.1%)realty, Consumer Durables (+10.0%), Oil and Gas (+9.5%), Automobiles (+9.4%) and Private Banks (+9.0%) outperformed the NIFTY50’s 8.5% weekly gain. Every major sector finished higher, but IT, Media, Defence, Healthcare and Pharmaceuticals lagged.
India’s October inflation figures, released on Thursday 12 November, will reveal whether rate expectations have shifted. Market participants put inflation at 5.9%, up from 5.5% in September and close to the RBI’s upper tolerance limit of 6%. A reading higher than expected could strengthen the case for a rate hike in December.
The main US release is October CPI on Tuesday, November 10. The inflation is expected to slow to 0.3% month on month from 0.6%, while core inflation is expected to ease to 0.2% from 0.3%. This means, headline inflation is expected to remain around 3.7%, with core inflation easing to about 2.5% from 2.6%. October Producer Price Index (PPI) is due on Friday, November 13, with headline producer prices expected to rise 0.4% month on month and core PPI 0.3%, both slower than September.
The inflation data will be read against a stronger US labour market. October payrolls rose by 1.65 lakh and unemployment fell to 4.1%, lifting the market-implied probability of a December Fed rate increase to about 80%.
The US calendar is lighter than the previous week, but still includes important technology and AI-related results. CoreWeave is scheduled to report on Tuesday, November 10. Cisco Systems and Applied Materials are scheduled to report after the US close on Thursday, 12 November. Their outlooks will provide new insights into enterprise technology demand, semiconductor equipment spending, and the sustainability of AI-related capital expenditure.
Market breadth
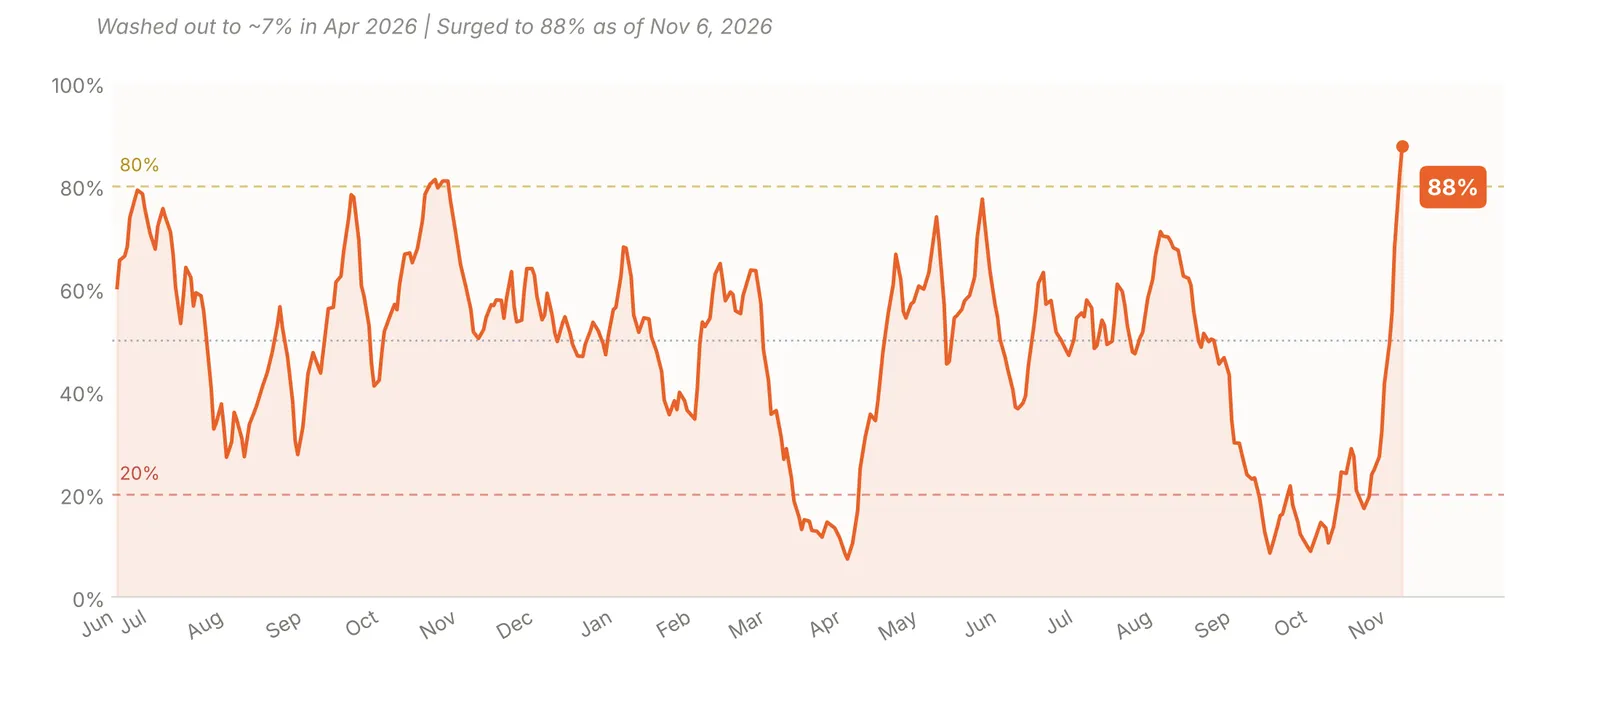
NIFTY50 breadth strengthened sharply by 6 November, with 44 of 50 stocks (88%) closing above their 50-day moving averages. That took the measure above the chart’s 80% marker, up from about 7% in April. Participation extended beyond the benchmark, with 428 Nifty 500 stocks rising and 69 falling over the week. Large caps still led the rally.
Foreign investors positioning
Foreign institutional investors (FIIs) bought a net ₹45,960.02 crore in the cash market during 2–6 November, buying in all five sessions after net sales of ₹45,161.71 crore in October.
Domestic institutional investors (DIIs) sold a net ₹24,196.52 crore over the same period, reversing October’s net buying. Foreign buying more than offset domestic selling, leaving the two groups with combined net cash purchases of ₹21,763.50 crore.
NIFTY50 outlook
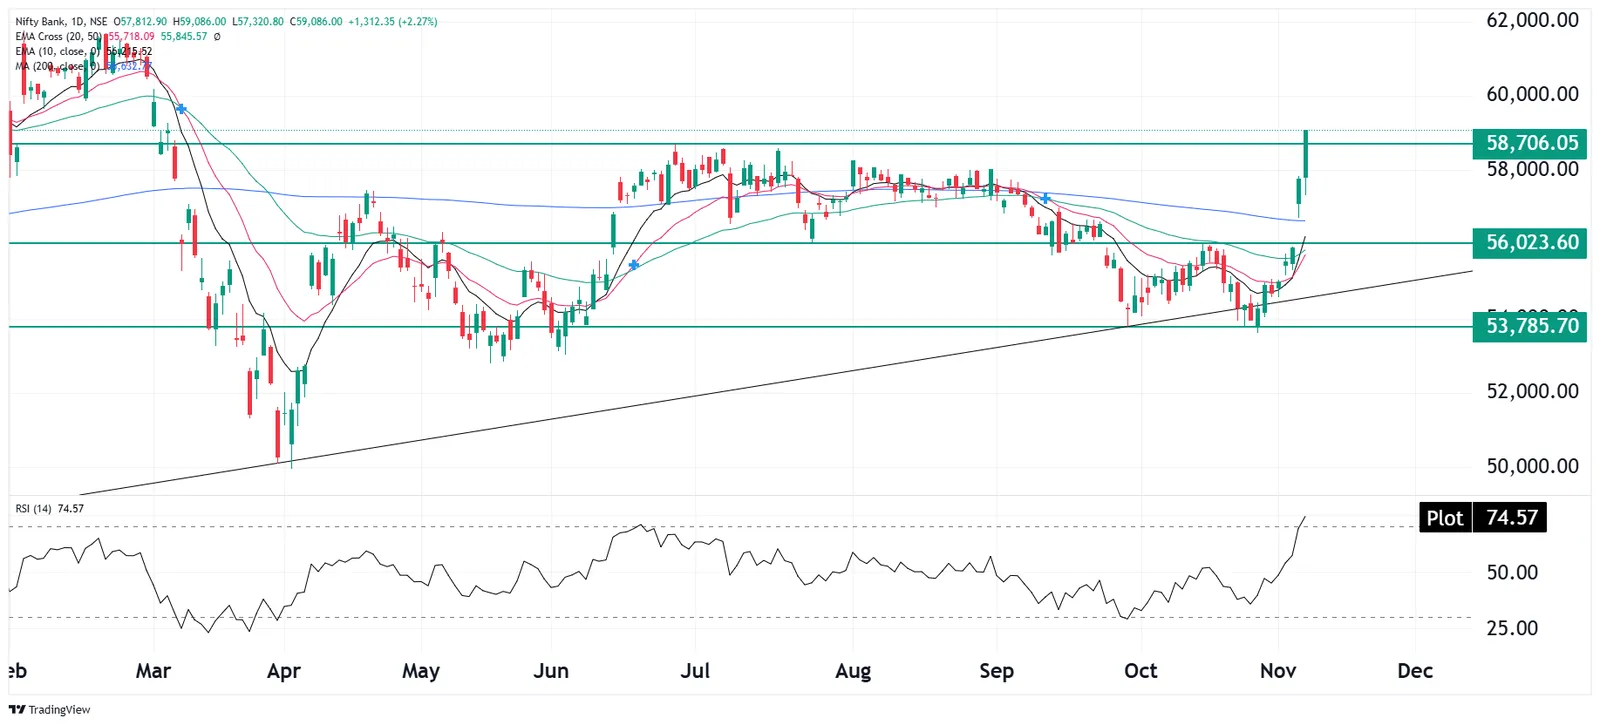
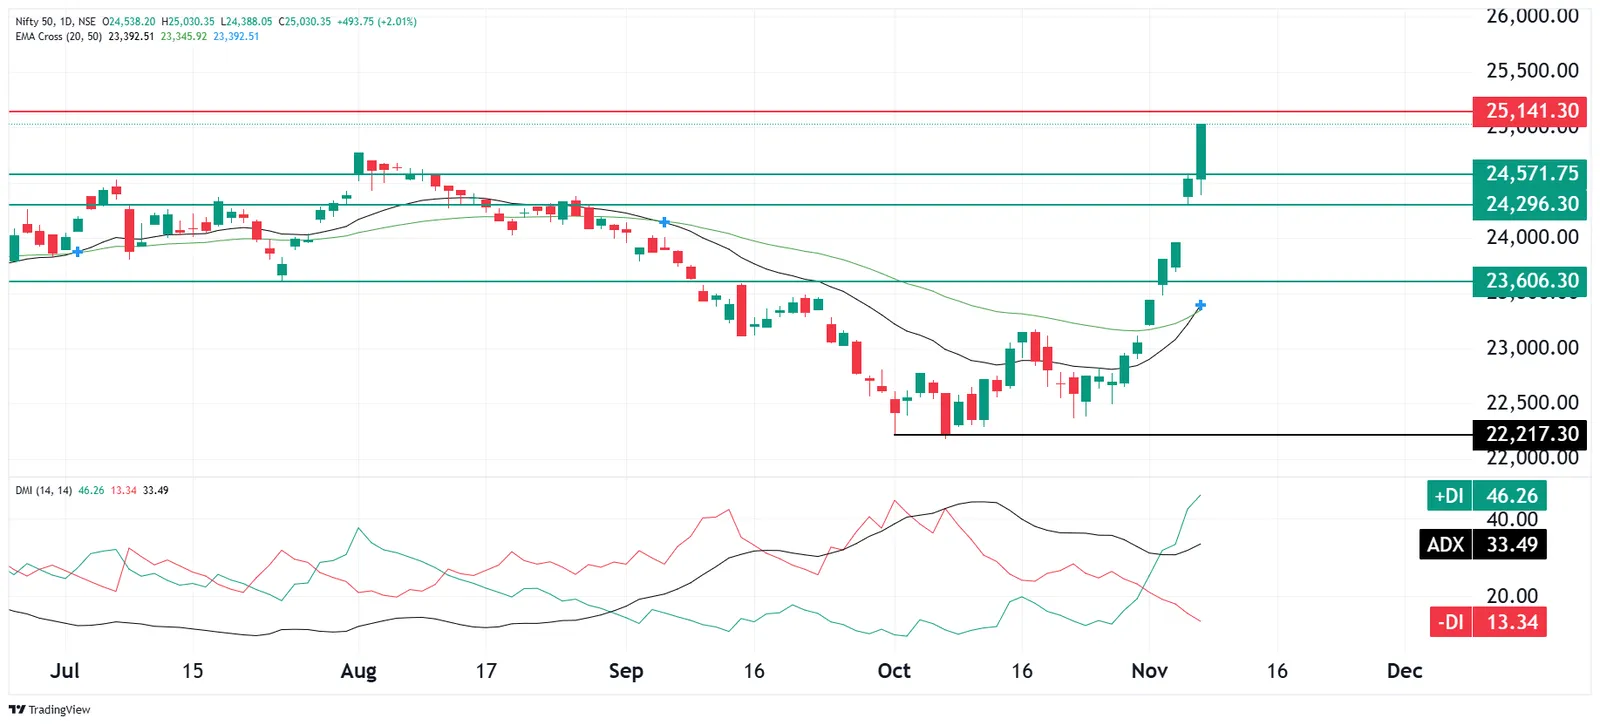
Over the week, the NIFTY50 gained 8.5%, closing at 25,030 on 6 November, just below the 25,048 resistance level. The 20-day EMA crossed above the 50-day EMA and the ADX rose to 33.49, with the +DI well above the −DI. This points to a strengthening uptrend.
If the index closes above 25,141 and holds that level, the rally could continue. On a pullback, the first support is at 24,571. A daily close below this level would bring the next significant support level of 23,606 into focus.
Related News
About The Author
Next Story