
Market News
Week ahead: India and US Inflation, HDFC Bank earnings, Trump's diesel deal and FIIs activity among key market triggers to watch

5 min read | Updated on October 11, 2026, 21:19 IST


SUMMARY
In the week ahead, India and US inflation data will test interest-rate expectations as major IT companies and banks report earnings. Indian benchmarks have ended an eight-week losing streak, but higher crude prices and elevated US bond yields remain important risks.
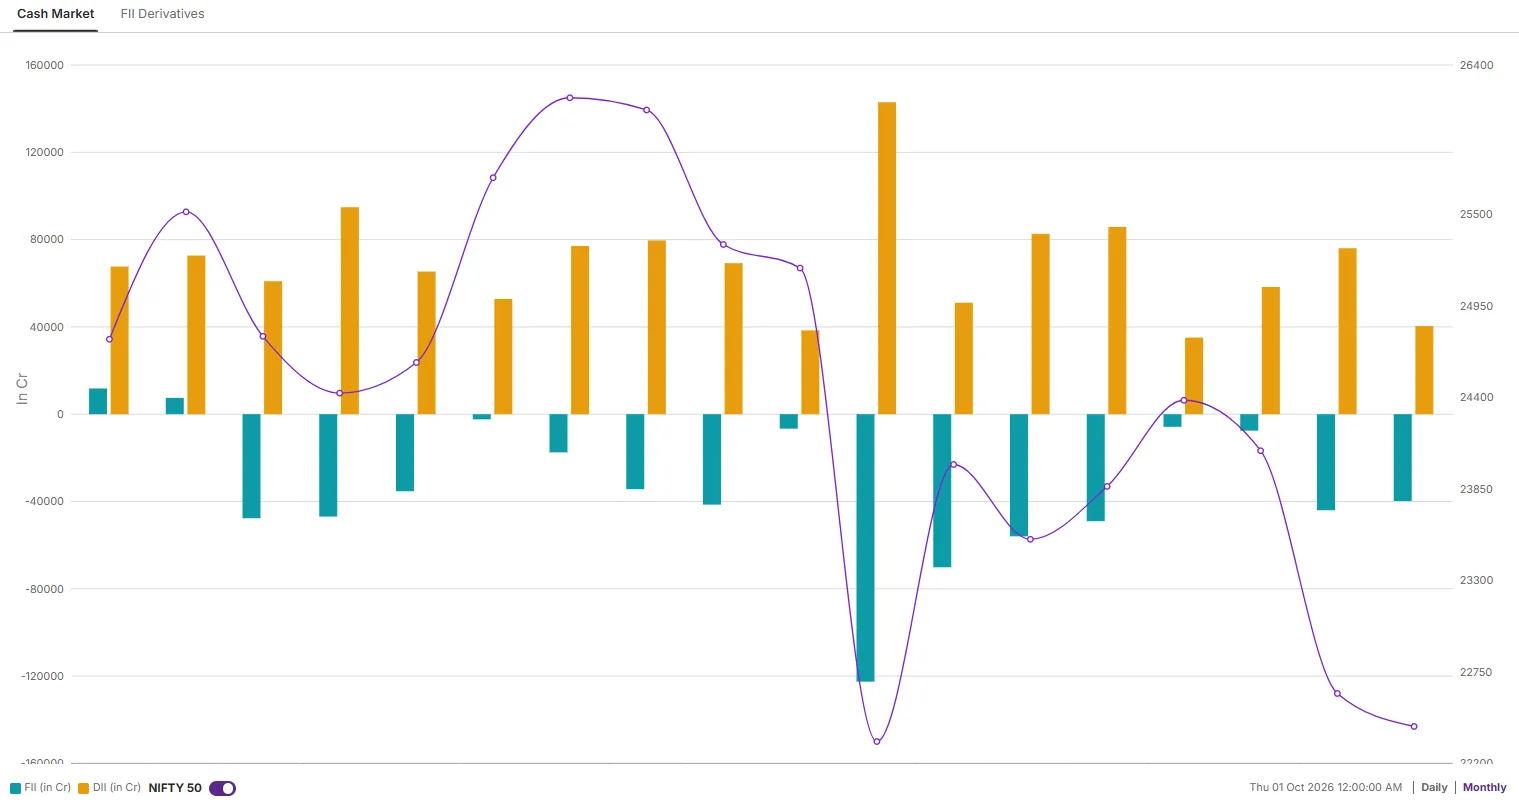
FIIs remained net sellers for the week and sold shares worth ₹30,294 crore.
Indian equities recovered on Friday to finish the week with modest gains. The NIFTY50 index closed at 22,520, up 0.4% for the week. The SENSEX ended at 72,472, gaining 0.7%. Friday’s advances reversed much of Thursday’s decline. The recovery ended eight consecutive weekly losses, with IT and financial shares providing support.
However, the week remained volatile. The RBI’s rate hike, expensive crude and foreign selling weighed on sentiment. On 8 October, the NIFTY50 slipped to a fresh 52-week low of 22,179 before recovering on Friday. Broader shares also joined the last-day rebound, with the Nifty Midcap 150 rising 1.5% and the Nifty Smallcap 250 gaining 0.5% on Friday. However, on a weekly basis the broader market ended the week on a negative note.
Sector performance was uneven. FMCG rose 2.4%, Private banks 1.9%, Financial services 1.6% and IT 0.9%, all outperforming the NIFTY50’s 0.4% gain. Realty fell 3.7%, Metals 3.6% and Automobiles 2.0%. Financial shares benefited from quarterly business updates and the absence of additional liquidity withdrawal measures alongside the RBI hike.
Against this backdrop, shares of Punjab National Bank, Kotak Mahindra Bank, Federal Bank and Axis Bank saw traction and jumped in the range of 3.5% to 7%.
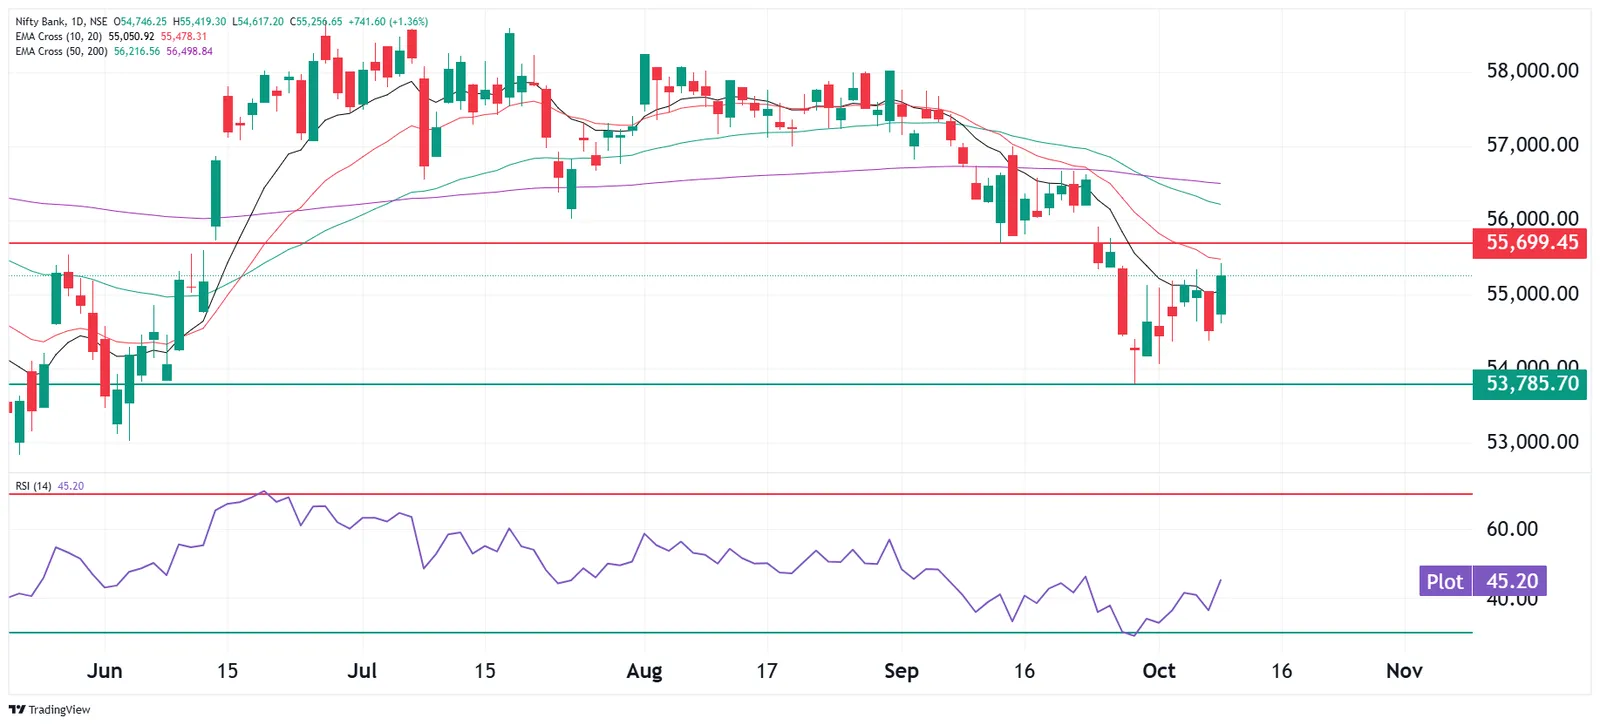
Meanwhile, September CPI in the US is due on 14 October, with market participants expecting headline inflation at 3.7% year-on-year and core inflation at 2.5%. Meanwhile, September payrolls increased by just 29,000, against expectations of 90,000, strengthening the case for an October pause in further rate hikes.
Additionally, US bond yields will remain important for Indian equities and the rupee. The 10-year Treasury yield eased to around 5.24% on 9 October after reaching a 24-year high earlier in the week, with stronger auction demand helping the retreat. Persistently high yields can pressure equity valuations and emerging-market flows.
Next week, attention will be on how quickly US production restarts and whether US-Iran talks ease supply worries. For India, Brent above $100 keeps pressure on the oil import bill, the rupee and inflation.
Market breadth
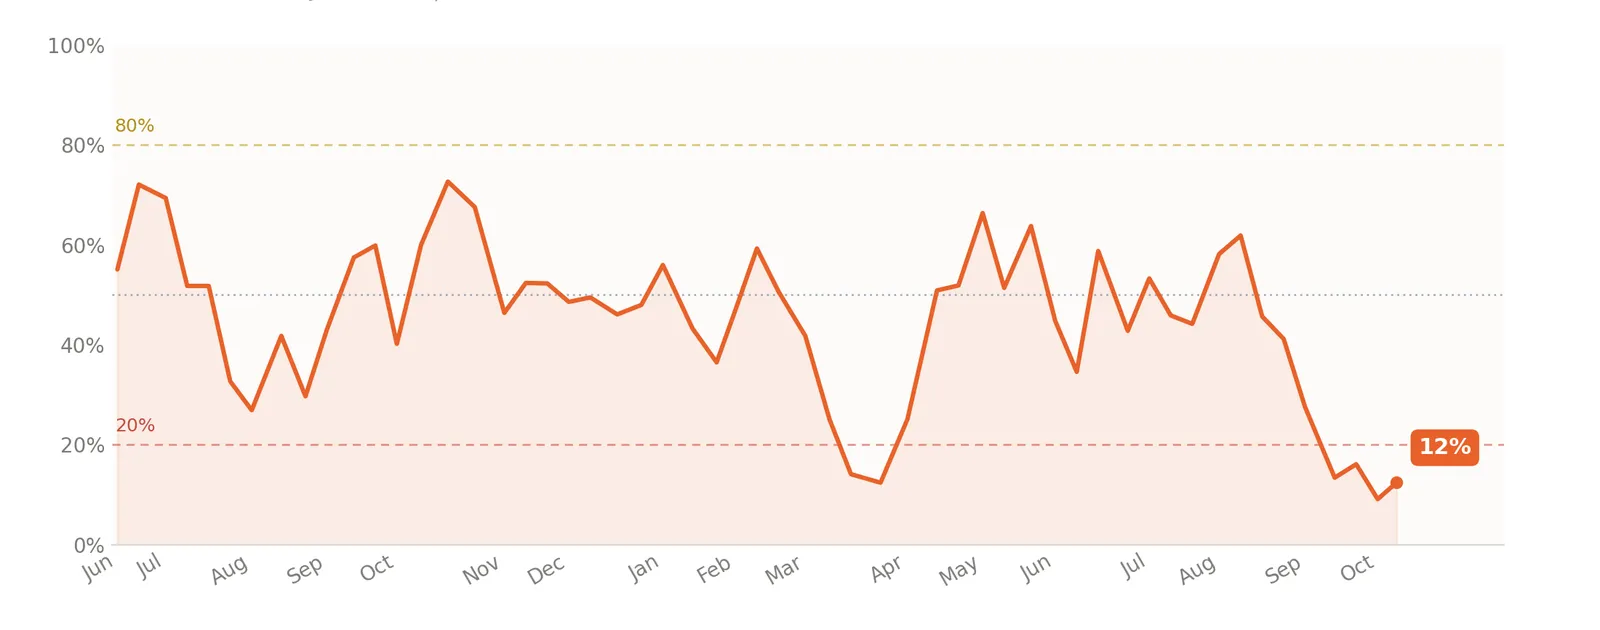
Market breadth remains weak, with only 12% of NIFTY50 stocks trading above their 50-day moving average as of 8 October. This means just 6 out of 50 stocks were above the average, while the remaining 44 were below or at it. Although the reading improved from the chart’s recent low of around 9%, participation remains limited. A stronger recovery would need more constituents to move above their 50-day average.
Foreign investors positioning
Foreign investors remained net sellers for the week and sold shares worth ₹30,294 crore. Meanwhile, the Domestic institutions continued buying across the displayed periods and bought shares worth ₹30,313 crore, providing an offset to foreign selling.
NIFTY50 outlook
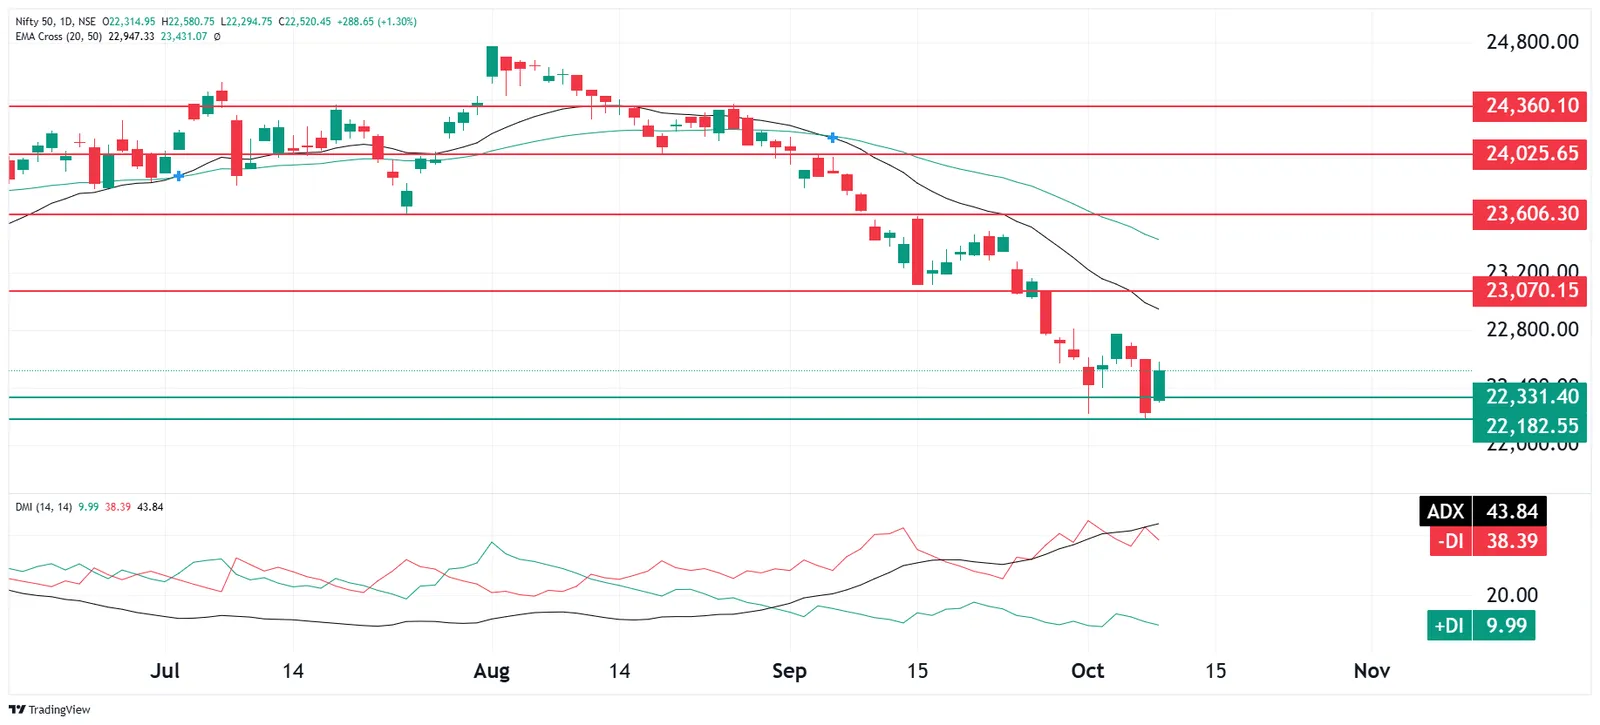
NIFTY50's daily chart continues to show lower highs and lower lows. Friday’s candle formed a bullish harami, suggesting a possible recovery that needs confirmation. The index remains below its falling 20-day EMA and 50-day EMA. Meanwhile, ADX at 43.84 indicates that the downtrend remains strong despite the rebound.
Immediate support stands near 22,330, followed by 22,180. The immediate resistance sits around 22,950–23,070 zone. If NIFTY50 closes above 22,580 on a daily basis, then the recovery could extend towards 22,950–23,070. Sustaining above that zone would strengthen the recovery. If the index closes below 22,330, then a retest of 22,180 becomes more likely.
About The Author
Next Story

