
Market News
Q2 earnings, US Midterm elections, Crude oil above $113 and Muhurat trading among key market triggers to watch next week
5 min read | Updated on November 01, 2026, 10:54 IST

SUMMARY
In the coming week, investors will track the US midterm elections, US activity and labour-market data, and a heavy India-US earnings calendar. Domestic equities enter the week after a broad rebound led by pharmaceuticals and healthcare. Elevated crude prices and Middle East supply risks remain major external headwinds for the domestic markets.
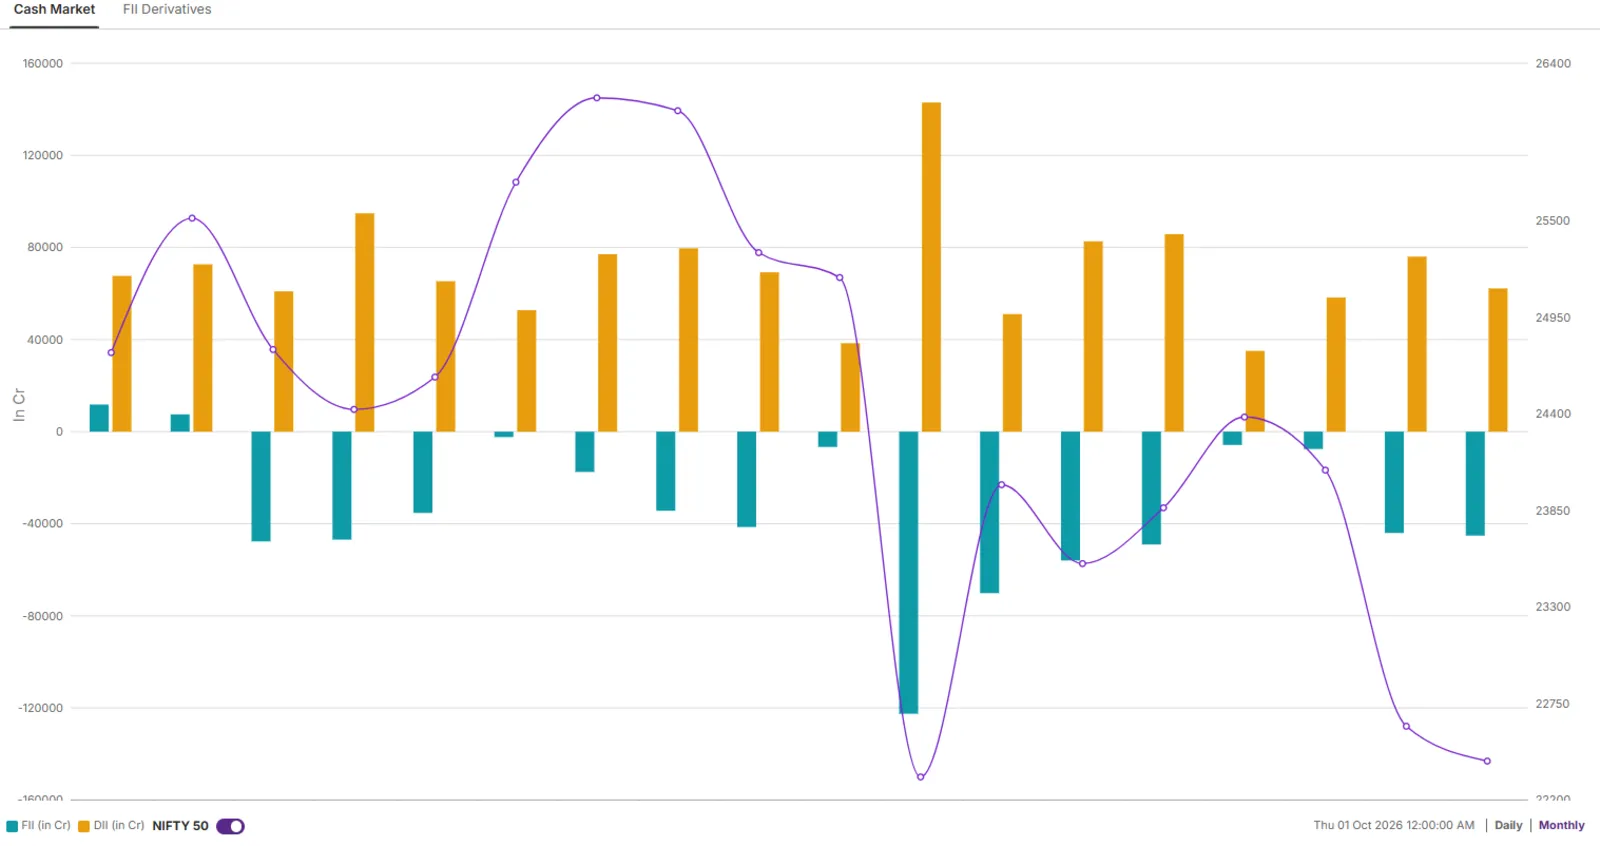
FIIs sold shares worth ₹45,161 crore in October, indicating continued caution towards Indian equities.
Indian equities ended a volatile week with strong gains. The NIFTY50 rose 2.00%, to 23,053. The Sensex gained 1.8%, to 74,459. The benchmarks recovered from early-week weakness and strengthened after the US Federal Reserve held rates steady. Better quarterly earnings and buying in pharmaceuticals, healthcare and technology stocks also supported sentiment. However, elevated crude prices and Middle East tensions remained a restraint.
The rally extended beyond the large-cap benchmarks. The Nifty Midcap 150 gained 2.2% and the Nifty Smallcap 250 advanced 2.3% for the week. The stronger small-cap move showed wider risk participation, although Friday’s session saw profit-taking in the broader market.
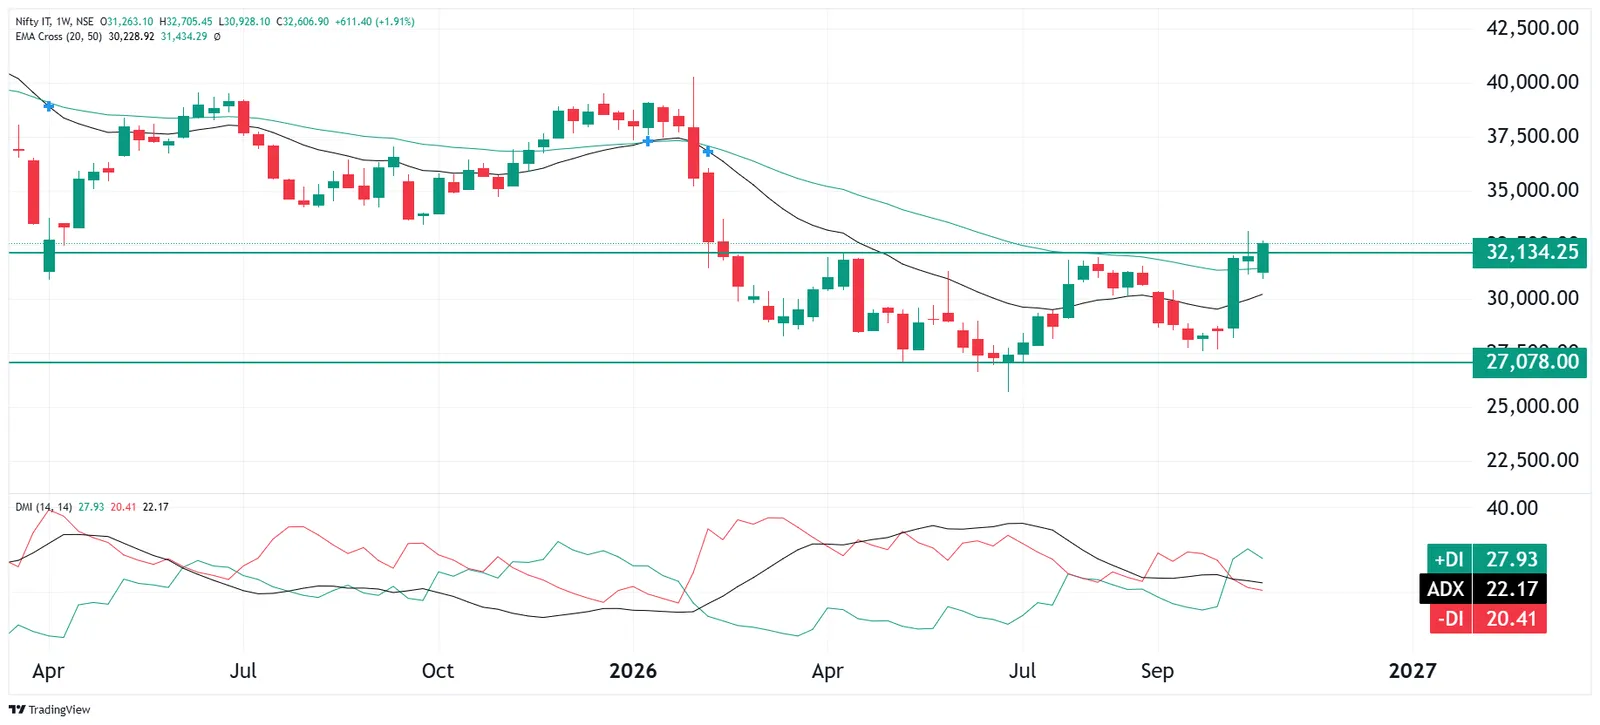
Pharmaceuticals (+7.0%) and healthcare (+6.9%) were the clear leaders. Media (+4.4%), Capital markets (+4.0%) and Realty (+3.7%) outperformed the NIFTY50. Oil and Gas (-0.7%) was the only major sector to finish lower. Banks (+0.7%) and Financial Services (+1.2%) gained but lagged the benchmark, while IT (+1.9%) finished slightly below the NIFTY50’s weekly return.
The sector now faces a fresh global headwind. On Friday, the Nasdaq Composite fell 2.8% and the S&P 500 declined 1.8% as disappointing updates from Intel and Amazon intensified the selling. The decline came after Indian markets closed, leaving its impact on domestic IT stocks to be tested in the coming week.
Meanwhile, October auto sales updates will also be in focus as markets open for November. Investors will track passenger-vehicle volumes from Maruti Suzuki, Hyundai, Tata Motors and Mahindra & Mahindra, alongside two-wheeler sales from Hero MotoCorp, Bajaj Auto and TVS Motor. Domestic dispatches, exports and commentary on dealer inventories will help assess demand ahead of Diwali.
The US calendar begins with the midterm elections taking place on Tuesday, November 3. On Wednesday, November 4, ADP private payrolls are expected to rise by about 75,000 and the ISM services index is expected at 54.8, broadly unchanged from 54.9.
The US employment report is due on Friday, November 6. The expectation is for non-farm payrolls to rise by about 65,000 after a 29,000 increase in September. The unemployment rate is expected to remain at 4.2%
For India, Brent above $110 raises the import bill and can add pressure to the rupee and inflation. Persistently high crude would be negative for fuel-intensive sectors such as aviation, paints, chemicals and logistics.
Market breadth
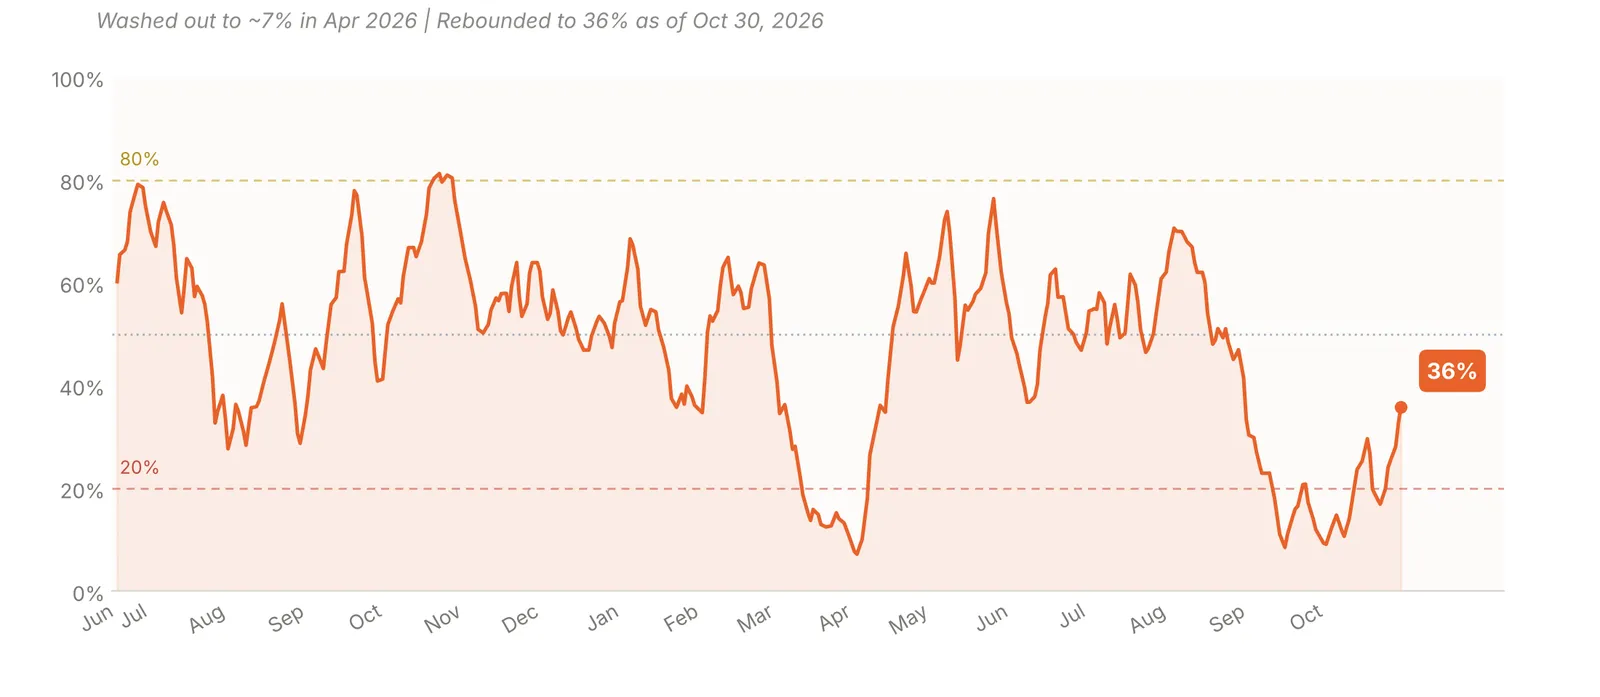
Market breadth is recovering, but participation remains narrow. The supplied NIFTY50 breadth indicator rose to 36% as of October 30, recovering from its recent lows but remaining below the 50% midpoint. This suggests improving strength beneath the index, although the rebound has yet to gain broad confirmation. A sustained move above 50% would strengthen confidence in the recovery, while a reversal would leave the rally dependent on fewer stocks.
Foreign investors positioning
FIIs sold shares worth ₹45,161 crore in October, indicating continued caution towards Indian equities. Persistent foreign selling remains a headwind, even as the market attempts to recover.
DIIs provided a strong counterbalance, buying shares worth ₹62,220 crore during the month. Their purchases exceeded FII selling by ₹17,059 crore, helping absorb the outflows. Continued domestic support remains important, while a sustained return of foreign buying would strengthen the recovery.
NIFTY50 outlook
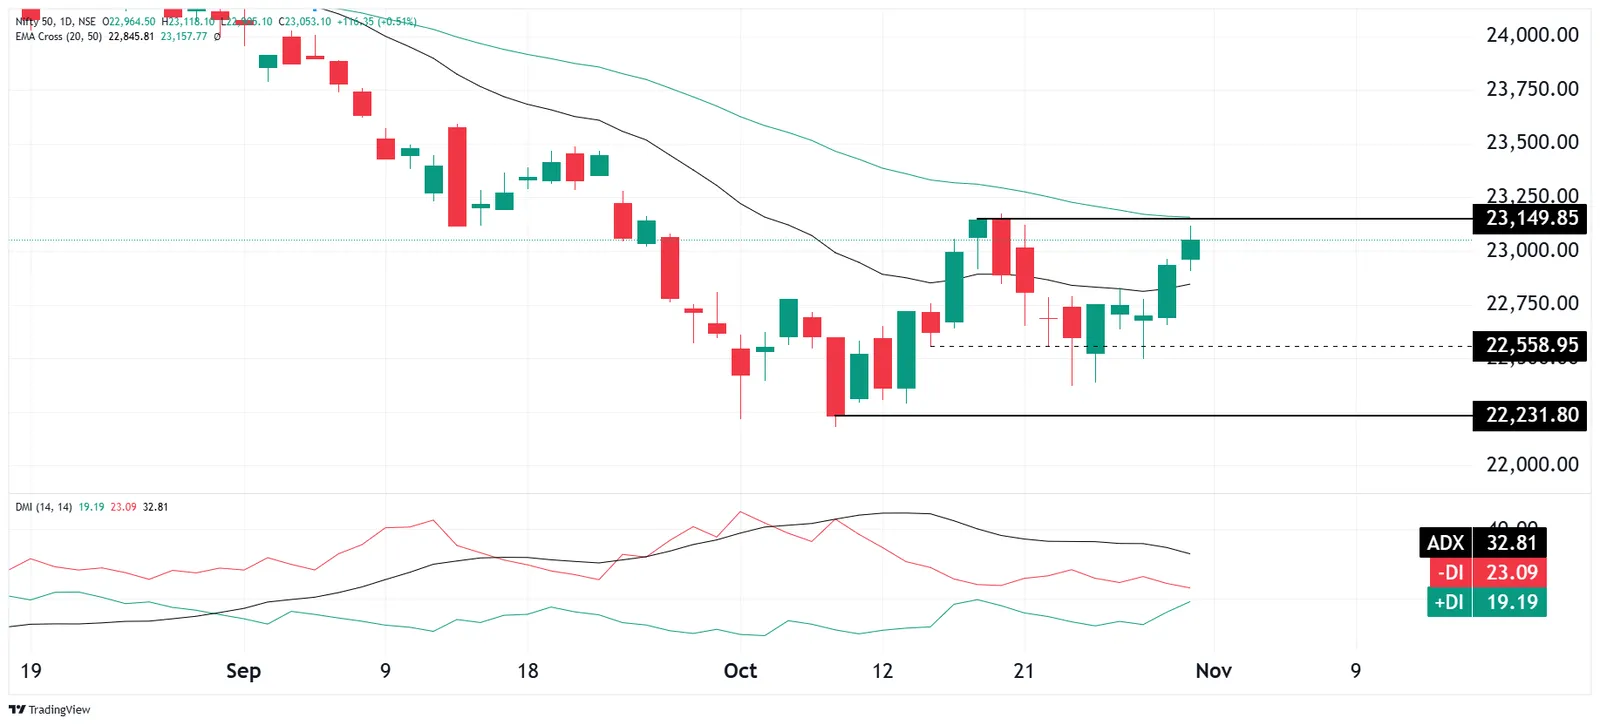
NIFTY50 index reclaimed its 20-day EMA and extended the recovery from October’s lows. However, the index remains below its 50-day EMA, which coincides with resistance around 23,150. Momentum is improving, but ADX currently at 32.81, suggests the earlier downtrend is losing strength, while a bullish reversal remains unconfirmed.
If NIFTY50 sustains above 23,150–23,160, the recovery could extend towards 23,250 and 23,450–23,500. If it fails to clear this hurdle, consolidation between resistance and the 20-day EMA is possible. A break below 22,845 would weaken the near-term recovery and bring 22,559 into focus.
About The Author
Next Story

