Market News
Jio Platforms listing, US Fed meeting, Crude oil above $116 and NIFTY monthly expiry among key market triggers to watch next week
5 min read | Updated on October 25, 2026, 11:04 IST


SUMMARY
In the week ahead, the US Federal Reserve’s interest-rate decision, the Jio Platforms listing, NIFTY monthly expiry and a heavy India-US earnings calendar will guide markets.
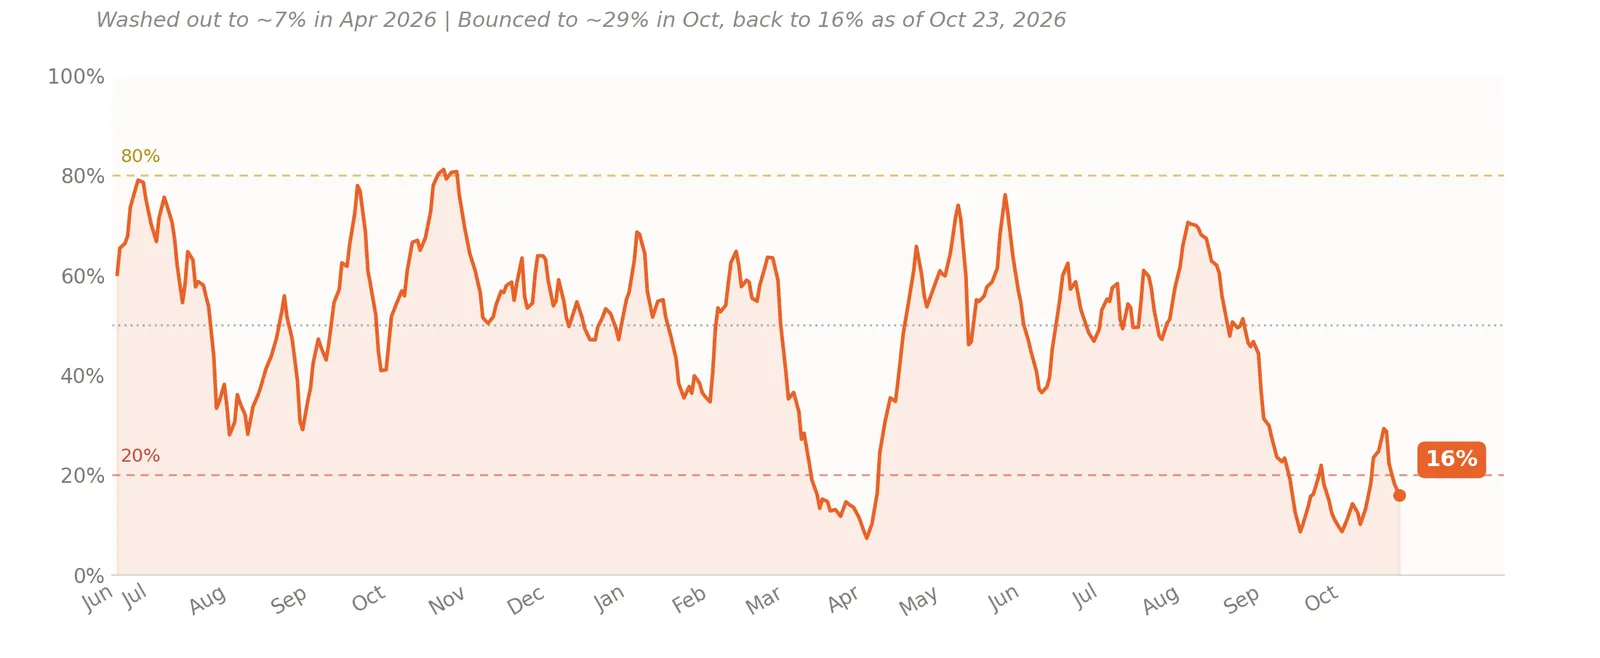
NIFTY50 breadth indicator slipped to 16% as of October 23, reversing its recovery to about 29% earlier in October.
Indian equities ended a two-week winning streak during the shortened trading week. The NIFTY50 fell 2.3% to 22,600, while the Sensex declined 2.1% to 73,123. The market ended lower in all four trading sessions, with Brent crude moving above $117 a barrel and foreign investors continuing to sell, while mixed September-quarter earnings reduced risk appetite. The Dussehra holiday kept the exchanges closed on Tuesday.
The decline was considerably sharper outside the large-cap indices. The NIFTY Midcap 150 index fell by 5.2%, while the NIFTY Smallcap 250 index dropped by 7.2%. This showed that selling pressure was widespread and that investors were reducing their exposure.
Meanwhile, India VIX rose by 20% during the week, reflecting higher demand for downside protection. The volatility index remained above its 50-day exponential moving average. Several mid- and small-cap stocks recorded double-digit declines, while IT stocks were the main pocket of relative strength.
The main outperformers against the NIFTY50’s 2.3% decline were IT (+0.2%), PSU Bank (-0.3%), Oil & Gas (-1.6%), Pharma (-1.7%), Healthcare (-1.8%) and Infrastructure (-1.96%). IT was the only major sector to finish in positive territory. The underperformers were Bank Nifty (-2.7%), Auto (-3.5%), FMCG (-4.3%), Energy (-4.6%), Realty (-5%), Metals (-5.4%), Capital Markets (-5.9%), Consumer Durables (-6.4%), Defence (-7%) and Chemicals (-7.1%).
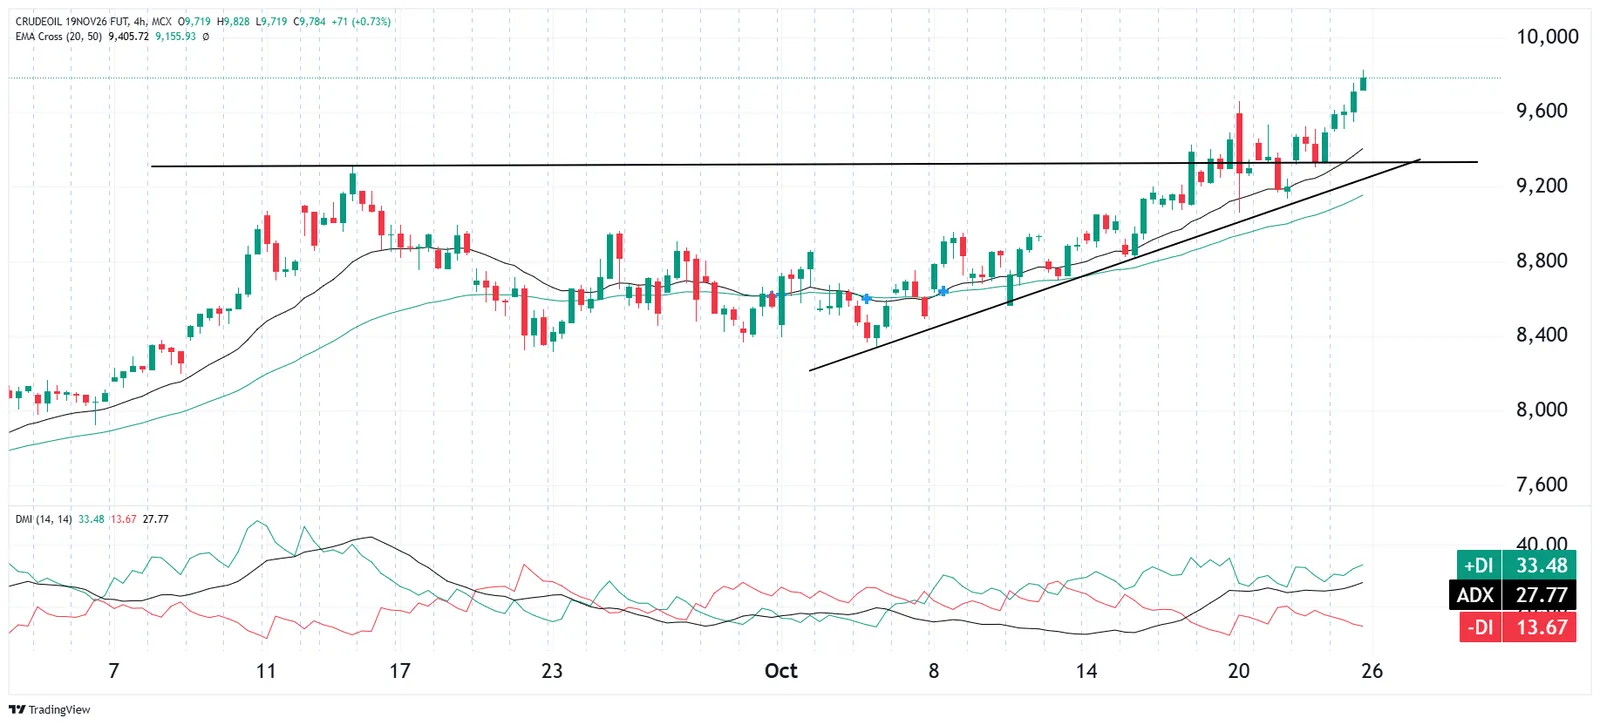
That puts Indian Oil, BPCL and HPCL in focus for fuel-marketing margins, InterGlobe Aviation for jet-fuel costs, and Asian Paints, Berger Paints, Apollo Tyres and CEAT for crude-linked inputs. Upstream producers sit on the other side. ONGC gained 2.4% and Oil India 0.6% in the week ended October 23.
Meanwhile, in the United States, the Federal Reserve meets on October 27–28 and announces its decision on Wednesday. Market participants expect the Fed to hold the federal-funds target at 3.75–4.00% after September’s rate increase. The policy statement and Chair Kevin Warsh’s press conference will be examined for guidance in December, when markets expect another increase.
United States: Alphabet and Microsoft report on Wednesday, followed by Amazon on Thursday. Their capital-expenditure plans and returns from AI investment will be central to global technology sentiment.
Market breadth
The NIFTY50 breadth indicator slipped to 16% as of October 23, reversing its recovery to about 29% earlier in October. It is back below the chart’s 20% threshold, signalling weak participation and confirming the fragility of the recent rebound. Although above April’s roughly 7% low, breadth remains subdued. A sustained improvement in participation would strengthen the case for a durable recovery, while continued weakness would leave index rebounds vulnerable to selling.
Foreign investors positioning
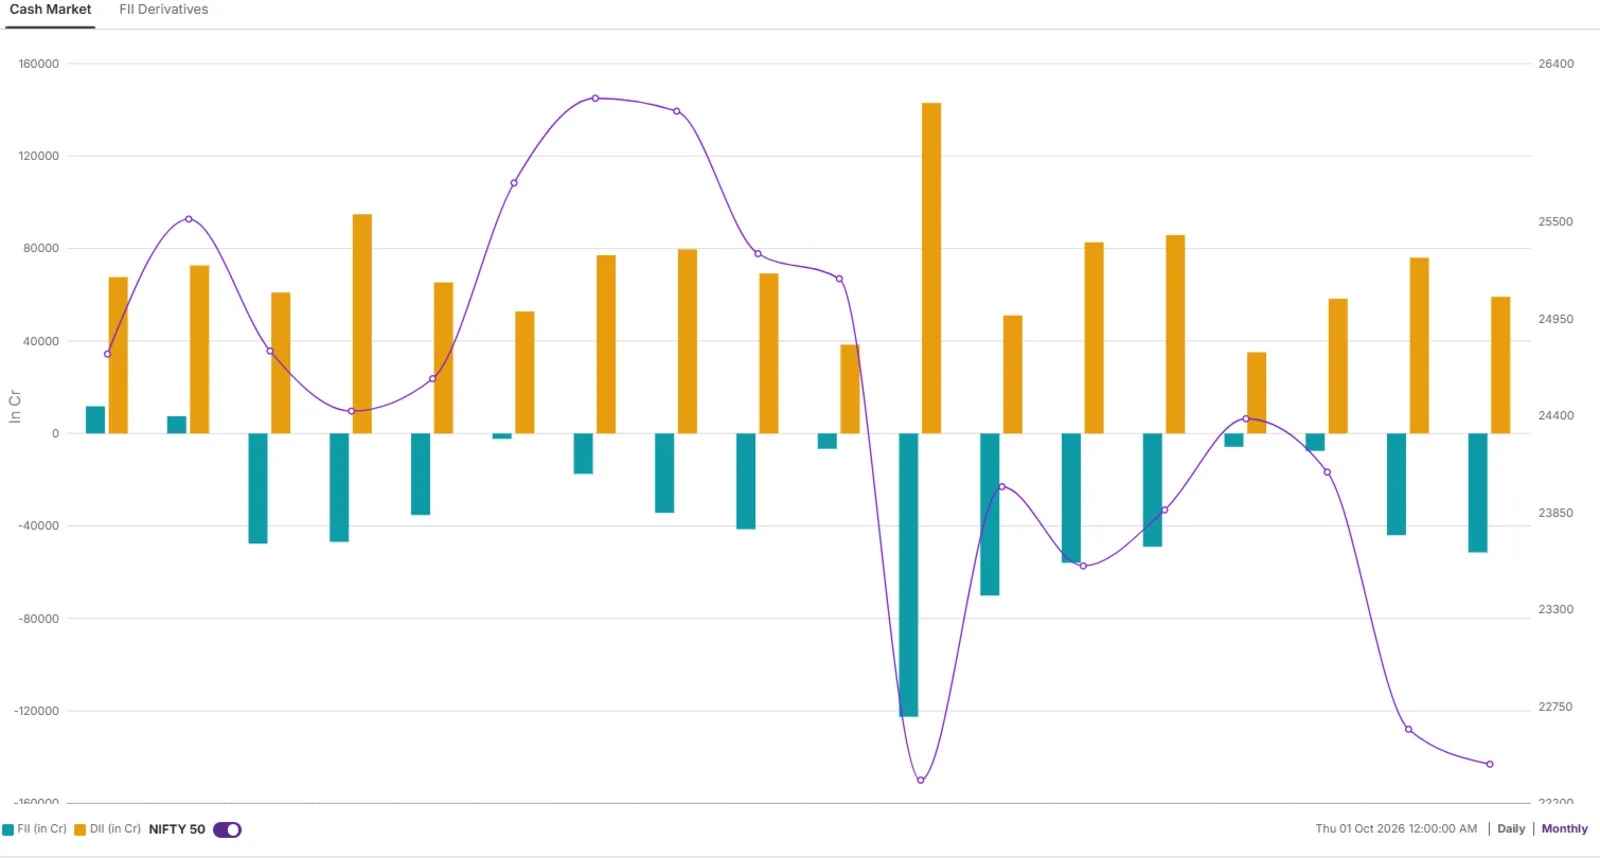
Foreign institutional investors remained net sellers in October, offloading shares worth ₹51,000 crore, following roughly ₹44,000 crore of selling in September. Meanwhile, Domestic institutional investors provided a substantial counterweight, with approximately ₹59,000 crore of net buying in October so far.
NIFTY50 outlook
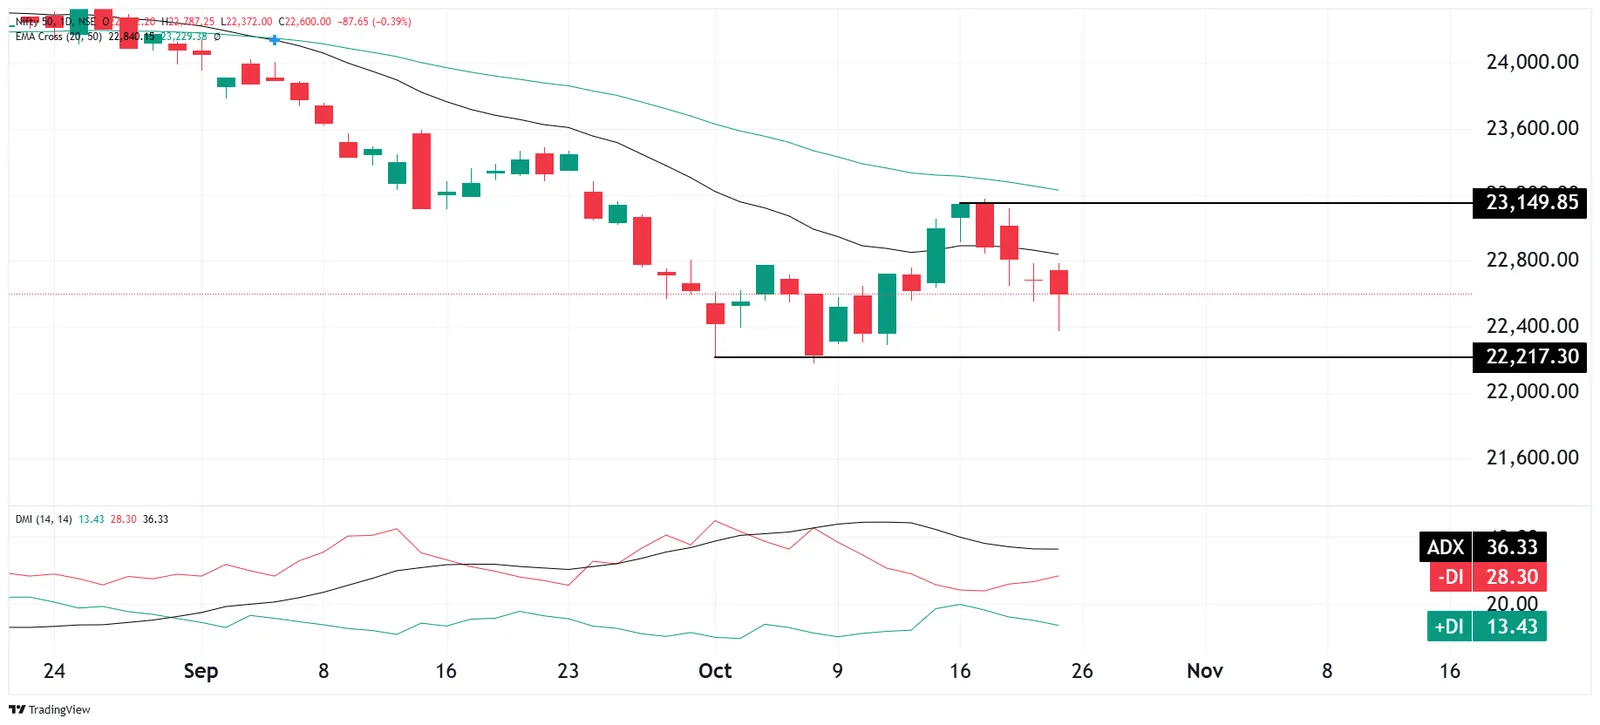
NIFTY50’s recovery stalled near 23,150, followed by four consecutive declines. The index remains below its falling 20-day EMA and 50-day EMA, keeping the broader bias bearish. The directional indicators reinforce this view, while ADX remains elevated at 36.33, although its recent easing suggests the trend’s strength has moderated.
If NIFTY50 breaks below 22,372, then the marked support near 22,217 comes into focus. A sustained break below that zone would increase the risk of a move towards 22,000. If the index reclaims 22,800–22,840, then a recovery towards 23,150 becomes possible.
About The Author
Next Story